NN, Inc. Crushes Estimates And Raises Guidance A Third Time, But Adjusted Profits Still Run Well Ahead Of GAAP
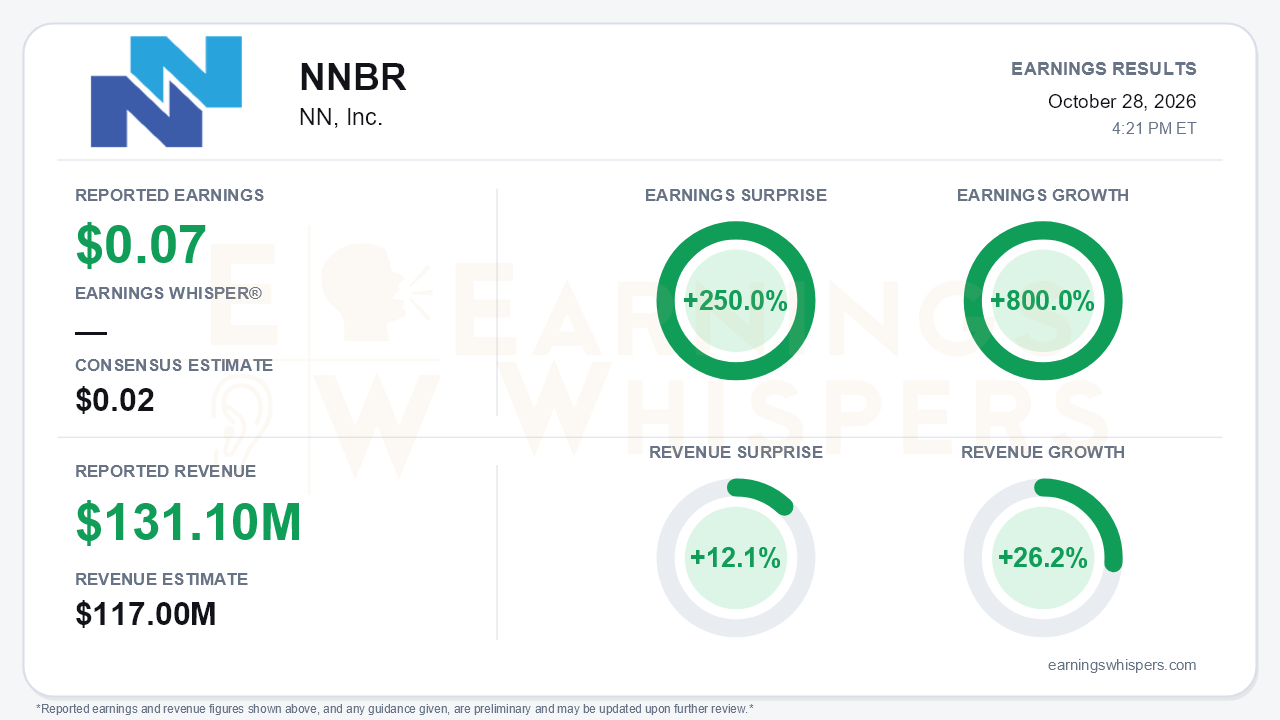
NN, Inc. delivered the kind of quarter turnaround bulls have been waiting for. Adjusted earnings of $0.07 per share beat the $0.02 consensus by 250.0% and grew 800.0% from the prior year's $0.01 adjusted loss. Revenue of $131.1 million topped the $117.0 million consensus by 12.1% and rose 26.2% year over year, a sharp acceleration from the roughly 12% growth NN posted in the first quarter. Management raised full-year guidance for the third straight time and finished cleaning up a capital structure that had constrained the company for years. That is the central story. The central tension is that the profitability narrative still lives almost entirely in adjusted figures, while GAAP results are moving in the opposite direction at the operating line.
The quality of the beat deserves scrutiny. GAAP loss from operations widened to $3.3 million from $2.2 million, which the company attributed to new-business headcount and professional fees tied to its strategic initiatives. The bridge to $8.5 million of adjusted operating income relies on $3.9 million of facility costs, $2.9 million of personnel and startup costs, and $1.6 million of professional fees, all sharply higher than a year ago. GAAP net loss narrowed to $4.6 million, or $0.13 per share, but that improvement leaned on a $2.8 million Brazil tax and insurance settlement and higher income from the China joint venture. The adjusted per-share figure also adds back $0.07 of preferred dividends. The top line has its own caveat. Higher selling prices from raw-material pass-through were cited first among the drivers of growth, so some of the 40.6% surge in Power Solutions reflects precious-metal inflation rather than volume alone.
The operating trends still look real. Adjusted EBITDA rose 49.7% to $18.5 million, and the 14.1% margin compares with 11.9% in the first quarter and 11.6% for 2025. Mobile Solutions, the weak link earlier in the year, grew 15.3% after barely growing in Q1. On the call, management sized data center revenue at about a $35 million run rate, up from essentially zero, against a $100 million goal. Liquid-cooling machine capacity is set to rise from an average of 19 in Q3 to 55 by Q1 2027. Defense reached about $62 million with a newly disclosed munitions contract, and marquee robotic-surgery OEM orders could nearly triple a $13 million medical business. The quoted pipeline stands at $750 million, with win rates of 25% to 28%.
The guidance progression carries the most weight:
- **2026 revenue:** now $480 million to $500 million, up from $445 million to $465 million at the start of the year.
- **2026 adjusted EBITDA:** now $64 million to $68 million.
- **2026 new business wins:** now $110 million to $130 million.
- **2029 targets:** lifted to $625 million in revenue and $87 million in adjusted EBITDA.
The raise was characterized as in line with estimates, however, and the full-year range implies fourth-quarter sales of roughly $102 million to $122 million, below Q3's level. Management also plans to curtail about ten near-zero-margin auto customers within a roughly $200 million auto base. That pruning should help margins but will dampen reported growth. Equipment lead times and PPAP validation gate the data center ramp. No 2027 guidance was offered.
The balance-sheet transformation is real but not free. Weighted shares jumped to 78.1 million from 49.6 million, so per-share leverage to EBITDA growth is diluted. The quarter-end balance sheet still showed $35.6 million of Series D preferred. Management said that tranche was subsequently redeemed at a $5 million discount, cutting net debt plus preferred from $261 million to $139 million pro forma. Long-term debt rose to $165.9 million, and the ABL and term loan remain the stated next fix. Operating cash flow improved to $16.9 million year to date despite a $17.4 million receivables build.
Investor sentiment moved meaningfully, flipping from negative (-0.18) to modestly positive (+0.08) in the Earnings Whispers survey. Price action has been less enthusiastic. At $3.80, shares sit 14.0% below the $4.42 open following the August report, though they remain roughly 41% above a $2.69 200-day moving average. The stock has cooled over the past quarter while staying well above its longer-term trend, and AVWAP readings remain positive.
The bottom line is that NN produced its most convincing quarter of the turnaround: accelerating sales, expanding adjusted margins, a third guidance raise, and a capital stack finally free of preferred stock. Bears still have legitimate ammunition. GAAP operating losses widened, part of the revenue growth is metal pass-through, the share count is far larger, and the guidance implies a softer fourth quarter as auto pruning begins. The next test is whether startup costs fade fast enough for GAAP results to start catching up with the adjusted story.
Read our earnings preview for NN, Inc.: https://www.earningswhispers.com/article/NNBR/20967
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-16 | |
| Oct-15 | |
| Oct-08 | |
| Oct-02 | |
| Sep-22 | |
| Sep-15 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-23 | |
| Jul-20 |
