NeoGenomics Faces A Tough Third-Quarter Comp After Three Straight Guidance Raises
NeoGenomics heads into its third-quarter report with momentum, a rising stock and a problem that is partly self-inflicted. The quarter laps the peak of a high-volume, low-value contract the company chose to exit, which will flatter pricing metrics while weighing on test counts. Management has raised its full-year revenue outlook three times in a row, so the question is no longer whether the clinical business is healthy. It is whether the company can keep clearing a bar it keeps raising.
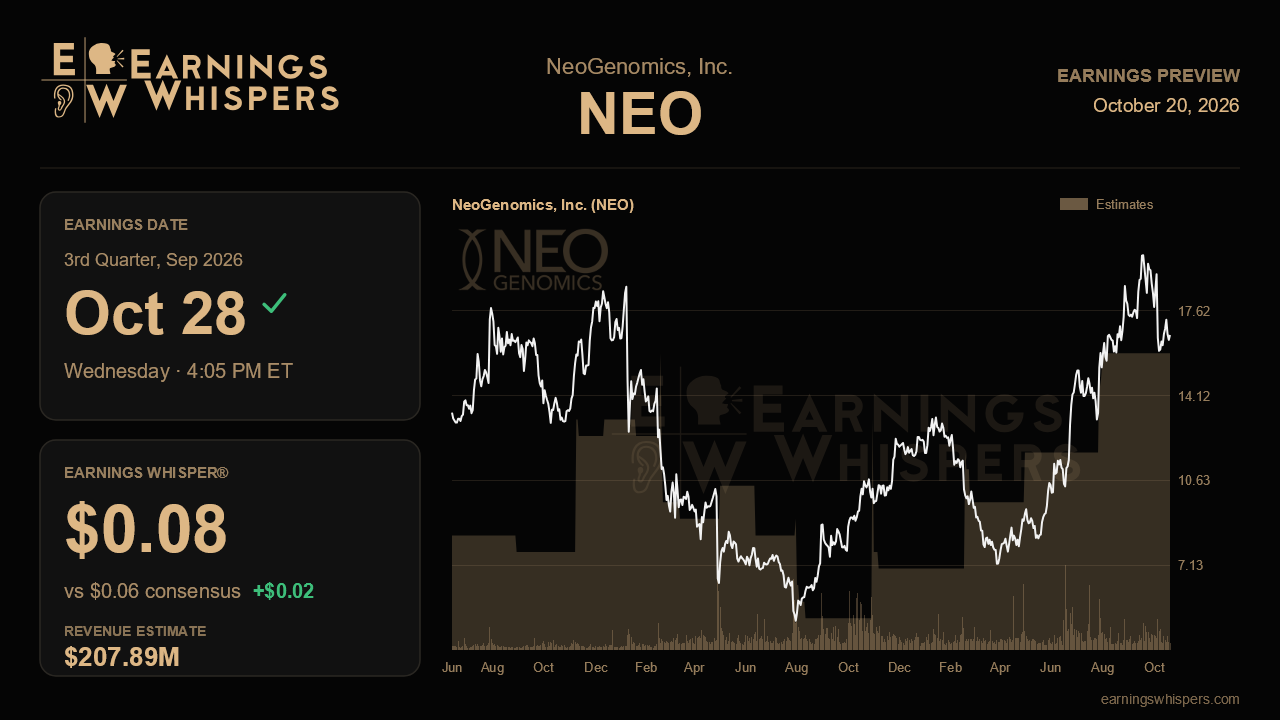
Wall Street expects adjusted earnings of $0.06 per share on revenue of $207.9 million, up 10.7% from $187.8 million a year ago. That growth is steady rather than spectacular, and it matches the roughly 11% pace NeoGenomics has posted for several quarters. Management guided to about $209 million, so consensus sits slightly below the company's own number. That leaves room for a modest beat, which has been the pattern: second-quarter revenue of $201.7 million came in about $4 million ahead of guidance. The earnings bar matters more. The company lost a penny per share last quarter, so even the consensus figure implies a sharp swing in profitability. The whisper number of $0.08 suggests some investors expect gross margin leverage to carry through. Two cents is small in absolute terms but meaningful against such a low base.
The last call made a clear case. Clinical revenue grew 14%, average revenue per test jumped 12% on a richer mix of next-generation sequencing work and better collections and managed-care pricing, and adjusted gross margin expanded 260 basis points to 48.1%. NGS revenue rose 26%, and management lifted its full-year NGS growth target to the mid-20s. To validate that story, this report needs evidence that pricing gains are lasting rather than a one-quarter jump, and that margin expansion holds near second-quarter levels as Lab of the Future efficiencies and the shift of the Pantracer liquid biopsy test to the NovaSeq X platform take hold. Clinical volume growth slowed to 2% from 6% in the first quarter. A further slowdown is expected because of the contract exit, but a soft volume number paired with weaker pricing would be harder to excuse.
The weak spot is pharma services, only about 5% of revenue but a source of repeated disappointment. Pharma revenue fell 26% last quarter despite record bookings, because contracts signed in 2025 have converted to revenue more slowly than usual. Management cut its full-year non-clinical outlook to a high-single-digit decline and pushed any recovery to 2027. Stabilization here would help credibility; another downgrade would raise doubts about how much those bookings are really worth. Longer term, any progress on the three RadarST MRD submissions pending with Medicare's MolDX program, or early traction for the newly approved PTEN companion diagnostic in prostate cancer, would support the growth story beyond this year.
Sentiment has turned meaningfully, moving to moderately bullish from bearish heading into the last report. The stock has gained 6.2% since then, ahead of the S&P 500's 3.6%, and at $16.42 it trades well above its 200-day moving average of $12.58. It is also about 19% below its post-earnings high of $20.15, which suggests the market has already given back some early enthusiasm. That keeps expectations elevated but not stretched.
The full-year guidance math frames the central issue. The current $802 million to $806 million range, combined with first-half results and the third-quarter outlook, implies fourth-quarter revenue roughly flat to slightly below the third quarter. Another raise would signal that pricing and NGS strength can outrun tougher comparisons. If NeoGenomics instead holds the range while margins slip or pharma weakens further, the market may conclude that the run of upgrades has stalled.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-15 | |
| Oct-14 | |
| Oct-06 | |
| Oct-05 | |
| Oct-05 | |
| Sep-01 | |
| Aug-26 | |
| Aug-26 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 | |
| Jul-20 | |
| Jul-09 | |
| Jul-07 |
