NeoGenomics Tops Consensus But Misses The Whisper As NGS Acceleration And A Third Guidance Raise Collide With Thin Cash Conversion
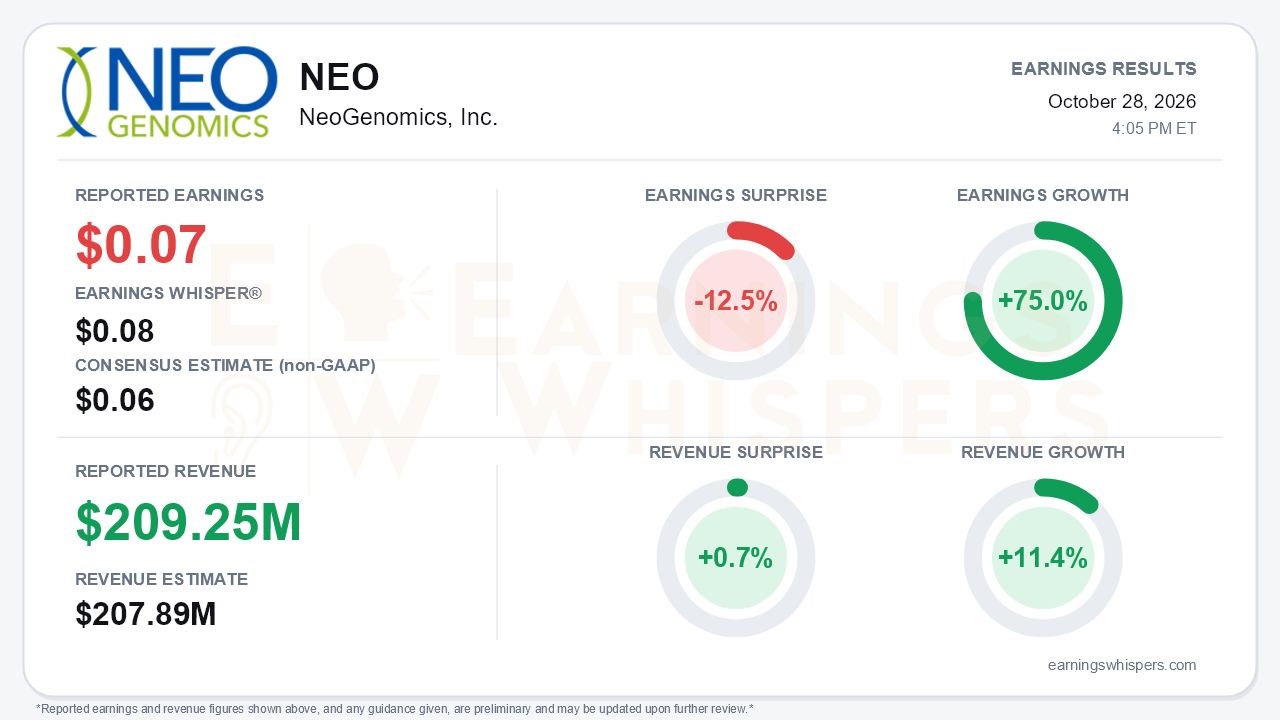
NeoGenomics (NASDAQ: NEO) delivered the kind of quarter that looks better operationally than its headline grade suggests. Adjusted earnings of $0.07 per share beat the $0.06 consensus but fell short of the $0.08 Earnings Whisper number, a 12.5% miss against the whisper. Revenue of $209.25 million topped the $207.89 million consensus by 0.7% and grew 11.4% year over year. Earnings grew 75.0%, while adjusted EBITDA rose 53% to $18.7 million. That marks a third straight quarter of faster EBITDA growth, after 27% in the first quarter and 36% in the second. Management also raised full-year revenue and EBITDA guidance for the third consecutive time. The central tension is that the top line and margins are clearly improving, while per-share earnings and cash generation trail that progress.
The quality of the EPS figure deserves scrutiny. Adjusted net income nearly tripled to $10.5 million from $3.6 million, a stronger improvement than the 75% per-share growth implies. The gap comes from the adjusted diluted share count, which jumped to 155.2 million from 134.1 million because the new convertible notes are now included on an if-converted basis. On a GAAP basis, the net loss narrowed to $7.5 million, or $0.06 per share, from $27.1 million, or $0.21. Part of that improvement reflects the absence of last year's $7.1 million impairment and lower IP litigation costs. The operating progress is real, however. GAAP gross margin expanded 340 basis points to 46.2%. Operating expenses fell 3% even as sales and marketing spending rose 27%.
Beneath the headline, growth is coming almost entirely from mix and pricing rather than volume. Clinical revenue rose 13%, but clinical test volume grew just 1.8%. Average revenue per test climbed 11.3% to $530. NGS is the engine. NGS revenue growth accelerated to 29% from 26% in each of the first two quarters and 23% in the fourth quarter of 2025. NGS volumes rose 17%, up from 14% in the second quarter, and large-panel volumes grew more than 25%. Adjusted gross margin reached 48.6%, extending a sequential climb from 46% in the first quarter and 48.1% in the second. Management lifted its full-year NGS outlook to more than 25% growth, or roughly $250 million. It also raised its gross-margin expansion target to well over 150 basis points. The company now guides to revenue of $807-$809 million and adjusted EBITDA of approximately $60 million.
The forward catalysts center on RaDaR ST. The test added Medicare coverage for immunotherapy response monitoring, its third covered indication. It also won a first regional commercial plan covering all MolDx-reimbursed indications, effective December 15. Two more indications are pending, which management said would expand access to over 40% of the tumor-informed MRD market. Management's tone turned more expansive. It plans to grow the sales force beyond 160 and lift R&D to roughly 7% of revenue. It also expects margin benefits in late 2027 and 2028 from moving heme NGS to NovaSeq X.
Bears have legitimate ammunition, however.
- **Non-clinical revenue:** The segment fell 10% to $15 million, and its outlook was cut for a third time, to a low-double-digit decline. The company may exit some legacy pharma contracts.
- **Cash conversion:** Accounts receivable swelled to $213 million from $159 million at year-end. Nine-month operating cash flow was just $2.9 million, and cash slipped to $139 million after a roughly $10 million DOJ settlement and disruption from the Xifin revenue-cycle conversion.
- **2027 headwinds:** Preliminary PAMA rates imply a low-to-mid single-digit million-dollar EBITDA headwind. Management also expects growth in average revenue per test to normalize toward mid-single digits, which matters for a story that has leaned heavily on pricing.
- **Leadership change:** The CEO handoff to Warren Stone on January 4 adds execution risk. Management framed it as continuity.
The market setup reflects improving, though not euphoric, expectations. Investor sentiment moved from mildly negative (-0.14) at the prior report to mildly positive (+0.13), a meaningful shift. Shares closed at $17.27 on the day before the report, up 11.7% from the opening price after the July release and nearly 36% above the 200-day moving average of $12.71. However, the stock entered the report about 14% below the 52-week high of $20.15 set on October 6, having given back a portion of its run before earnings. That retreat may help explain why the whisper sat above consensus. The Earnings Whispers trend signals are mostly positive, with sequential growth, momentum, and AVWAP readings all favorable.
The bottom line is that NeoGenomics is executing a credible mix-shift story. NGS growth is accelerating, gross margin is expanding sequentially, and guidance keeps moving higher. The whisper miss stems more from per-share dilution and elevated expectations than from operational weakness. Still, muted volumes, receivables piling up during the billing-system transition, and pricing headwinds heading into 2027 mean the next leg depends on RaDaR ST reimbursement translating into volume, and on collections catching up with revenue.
Read our earnings preview for NeoGenomics, Inc.: https://www.earningswhispers.com/article/NEO/20965
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-15 | |
| Oct-14 | |
| Oct-06 | |
| Oct-05 | |
| Oct-05 | |
| Sep-01 | |
| Aug-26 | |
| Aug-26 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 |
