KKR Real Estate Finance Faces Book Value Test As Strategic Review Hangs Over Trough Quarter
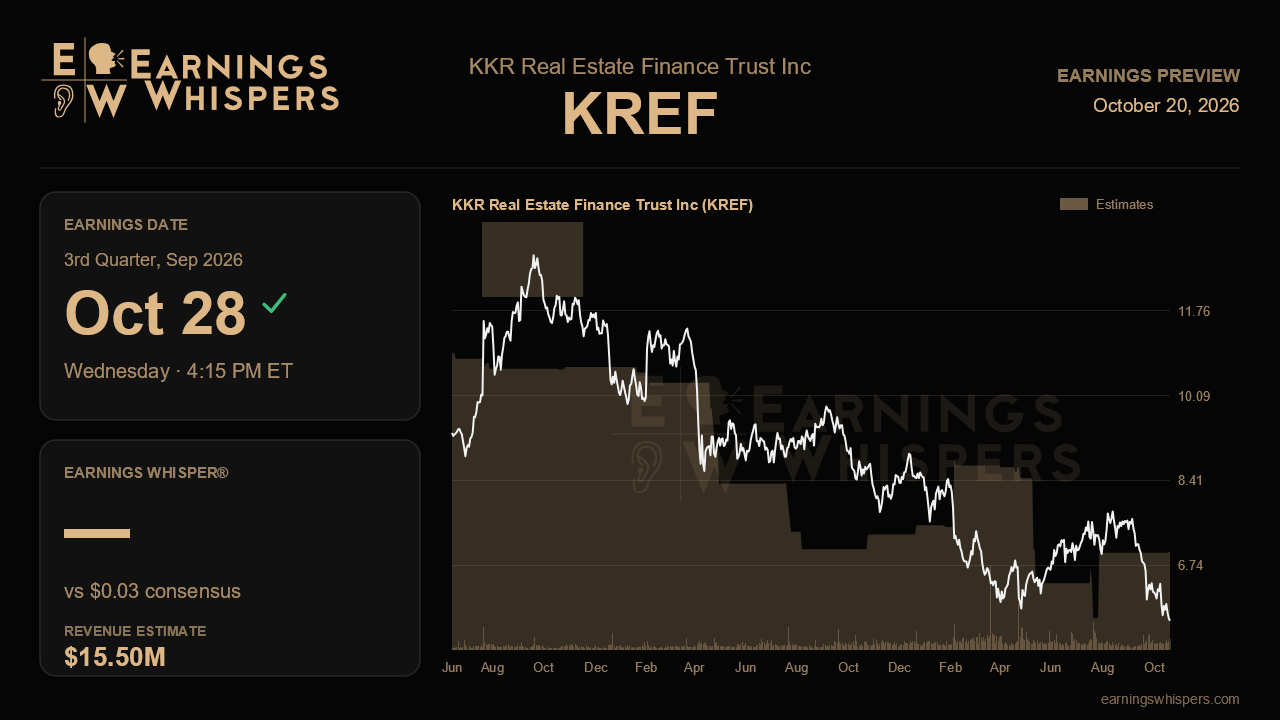
For a mortgage REIT, the most important number is rarely earnings per share. It is book value, and at KKR Real Estate Finance Trust that figure has been sliding for a year. Book value per share fell from $13.78 to $10.24 over four quarters, including a 13.7% drop last quarter alone. Management told investors the worst of the damage is now behind them. The third-quarter report, due after the close on October 28, is the first real chance to check that claim. It also arrives with an independent board committee weighing strategic alternatives.
The Street is setting a very low bar. Consensus calls for earnings of $0.03 per share, an improvement from the $0.60 loss last quarter and from the $0.06 loss a year ago. The 150% growth figure looks impressive, but it mostly reflects how weak the comparisons are. Revenue tells a harsher story. Analysts expect about $15.5 million, down roughly 86% from $108.0 million a year earlier and far below last quarter's $85.5 million. That fits management's warning that earnings would bottom later in 2026 and stay depressed for several quarters. The company has offered no formal guidance. Even so, a $0.03 estimate sits well below the reduced $0.10 quarterly dividend. Last quarter, distributable earnings before realized losses only matched that payout, so coverage remains a live concern.
The most useful evidence will come from credit and portfolio mix rather than the headline. Last quarter, a Chicago office loan and a Carrollton multifamily loan were downgraded to the weakest risk rating. A Dallas multifamily loan also slipped, and the Boston life science loan was taken back as real estate owned. If this quarter shows few new downgrades and only modest additional reserves, the claim that book value impairment has peaked gains credibility. Another meaningful drop in book value would undercut it badly and raise questions about the remaining legacy book. Management also set clear year-end targets. It wants roughly half the portfolio in 2024 through 2026 vintage loans, up from 32%, and legacy office below 10%, down from 18%. Hitting those goals requires visible progress now.
Repayments are the funding engine behind that rotation. The company raised its 2026 repayment outlook to more than $2.0 billion and had collected $1.2 billion in the first half. Continued inflows would support more than $700 million of liquidity and help bring leverage down from 4.3 times toward the 3.5 to 4.0 times target. On the upside, the OpenAI lease at the Mountain View property was expected to begin partial occupancy this quarter. Confirmation that the move-in is on schedule would support the plan to market the asset within about a year. It would be one of the few concrete value-creation stories in the portfolio.
The market is not giving management much benefit of the doubt. Shares have fallen about 25% since the last report while the S&P 500 gained nearly 3%. At $5.69, the stock trades well below its 200-day moving average of $6.99. It sits only about 3% above its post-earnings low of $5.52. That is also below the $7.24 average price of the company's post-quarter buybacks, which are now subject to the strategic review committee. Sentiment has also soured, with bearish readings deepening from about 28% to roughly 36% ahead of the report.
That skepticism means a merely acceptable quarter could steady the shares, but only if the balance sheet cooperates. Any update on the strategic review, even a procedural one, will draw attention. The central question, however, is simpler. If book value holds near $10 and credit migration slows, management's argument that the reset is largely complete survives. If book value falls again, the earnings trough becomes much harder to call a bottom.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-20 | |
| Oct-14 | |
| Sep-18 | |
| Sep-17 | |
| Aug-20 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 | |
| Jul-21 | |
| Jul-21 | |
| Jul-17 | |
| Jul-16 | |
| Jul-13 | |
| Jul-07 |
