Heritage Faces A Tougher Quarter As Reserve-Release Tailwind Fades And Growth Gets Tested
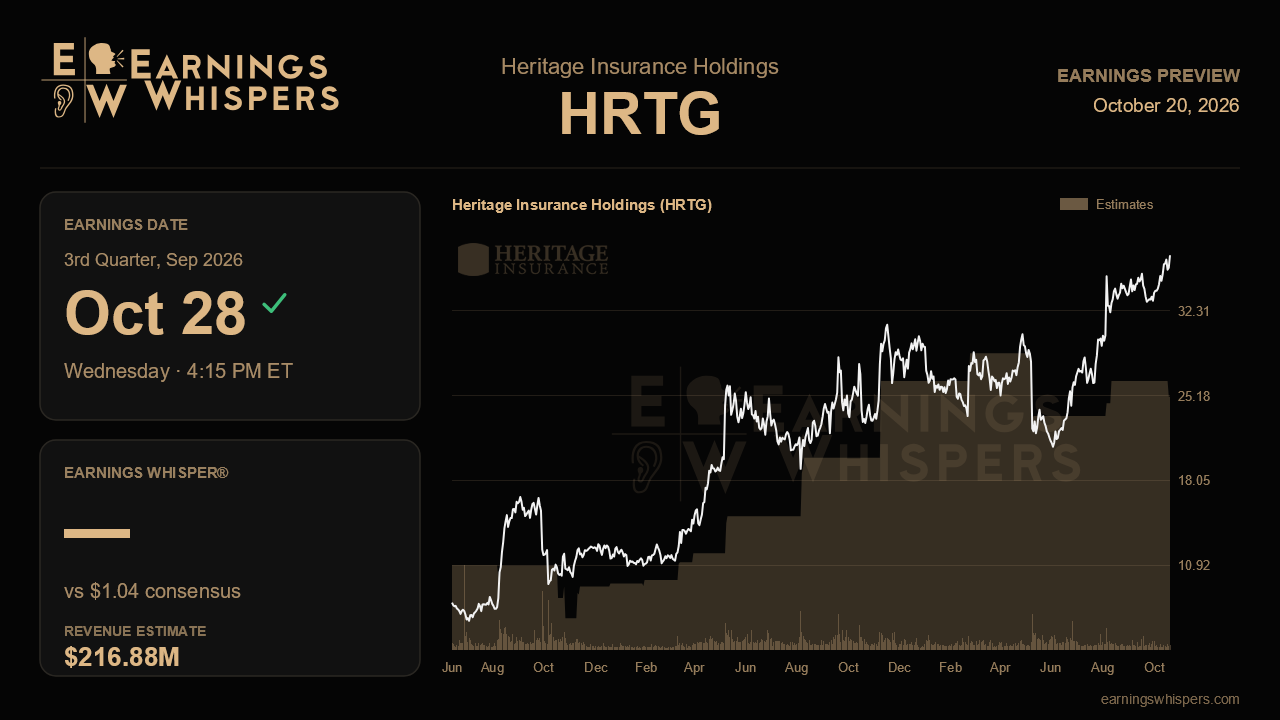
Heritage Insurance Holdings heads into its September-quarter report with a credibility test of a different kind. Last quarter's $2.05 per share was flattered by $23.4 million of favorable prior-period reserve development, and the Street is now bracing for a far more ordinary result. The question is whether the underlying engine management described, rising policy counts, strong new business and a cleaner balance sheet, can carry earnings once the one-time cushion is stripped away.
Consensus calls for earnings of $1.04 per share on revenue of about $216.9 million. That revenue figure would be up only 2.1% from a year ago and barely above last quarter's $214.2 million, so the top line is essentially treading water. Earnings, by contrast, are expected to fall roughly 36% from the $1.63 earned in the year-ago quarter. Heritage has not offered formal numeric guidance, but management did steer investors toward a net loss ratio that is roughly flat excluding reserve development. That framing matters: if the Street's estimate assumes little or no favorable development, then a clean quarter near consensus would actually confirm that core underwriting is holding up, while any additional releases would be upside.
The more important tension sits inside the premium base. On the last call, management showed that personal-lines new business remains strong after years of deliberate shrinkage, and that commercial residential policy count turned positive, up 4.9%. Yet commercial residential in-force premium fell 12.7% year over year, a steeper slide than the 7.8% decline the prior quarter, as Heritage walked away from underpriced accounts amid new Florida competition. Management said that pricing pressure appears to be leveling off. This report should show whether that is true. A moderating premium decline in commercial residential, alongside continued policy growth, would validate the idea that discipline is a choice rather than a symptom of lost demand. Another deterioration would raise the question of how long revenue can stay flat while the company refuses to chase price.
The second swing factor is the accident-year loss ratio. Management warned that single-digit Florida rate decreases will earn in over time, nudging current-year losses higher. Investors should look for evidence that this drift is gradual and offset by the stabilizing frequency and severity trends that justified last quarter's release. For a Florida-heavy insurer, the September quarter also carries meaningful weather exposure, so catastrophe losses relative to the reinsurance program can easily overwhelm the rest of the story. Early traction in the Texas excess and surplus line, along with commercial growth in Hawaii, New York and New Jersey, would help show that new geography can eventually fill the Florida gap, though those efforts are meant to scale over several years and should not be expected to move this quarter's numbers much.
Capital deployment rounds out the checklist. Operating cash flow reached $166.5 million in the first half, debt-to-capital fell to 13%, and the board expanded the buyback authorization to $50 million. Evidence that repurchases are actually being executed would support per-share value even if earnings compress.
The market has leaned toward giving Heritage the benefit of the doubt. Shares are up 4% since the last report while the S&P 500 slipped 0.5%, and at $35.93 the stock trades well above its 200-day moving average of $28.18, with its entire post-earnings range of $31.15 to $37.30 sitting above the prior quarter's ceiling. Sentiment, however, is little changed and still modestly bearish, suggesting enthusiasm is not running hot. That leaves the report centered on a single issue: whether Heritage can show that its underwriting margins and growth inflection are durable without leaning on reserve releases. If it can, the turnaround narrative graduates to a growth story; if not, last quarter will look like a peak.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-19 | |
| Sep-17 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-24 | |
| May-28 | |
| May-08 | |
| May-07 | |
| May-07 | |
| Apr-21 | |
| Mar-12 | |
| Mar-10 | |
| Mar-09 |
