Heritage Insurance Crushes Estimates On Reinsurance Savings, But Florida Commercial Erosion And Delayed Premium Inflection Cloud The Top Line
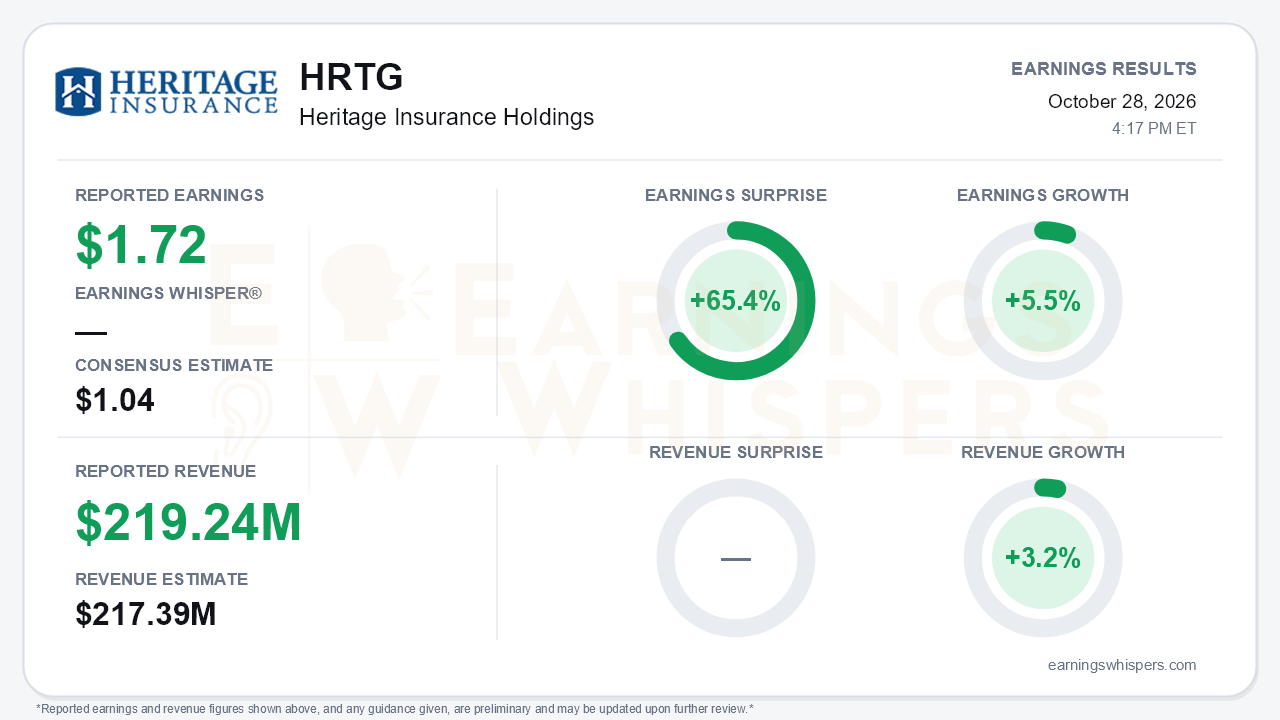
Heritage Insurance Holdings (NYSE: HRTG) delivered a large earnings beat in a quarter that brought catastrophe losses back. Diluted EPS of $1.72 topped the $1.04 consensus by 65.4% and rose 5.5% from $1.63 a year ago. Revenue of $219.24 million edged past the $217.39 million estimate by 0.9% and grew 3.2%. Those numbers show an insurer whose margins and balance sheet are compounding faster than its business is growing. That is the central tension. Heritage absorbed $15.8 million of pre-tax catastrophe losses, versus none a year earlier, and still grew earnings per share. But gross premiums written fell again, and the premium inflection management promised earlier in the year has not arrived.
The quality of the beat deserves scrutiny. Net income rose only 1.4% to $51.1 million, and pre-tax income actually slipped to $67.7 million from $68.3 million. EPS growth came from three sources:
- a 4.0% reduction in diluted shares;
- an effective tax rate 1.7 points lower;
- $14.0 million of favorable prior-year reserve development, up from $5.0 million a year ago.
Revenue growth was also not a demand story. Gross premiums earned fell 2.5%. Net premiums earned rose 5.4% only because ceded premiums dropped 11.8%. That drop reflects the first full quarter of savings from the June catastrophe reinsurance program, which saves about $63 million on a treaty-year basis, along with a smaller northeast quota share. EPS growth of 5.5% is also a clear deceleration from the 18.5% year-to-date pace.
Beneath that, underwriting genuinely improved. Total weather losses rose to $33.6 million from $13.8 million, yet the combined ratio held at 73.0%. On the call, management noted that the loss ratio excluding catastrophes, weather and prior-year development improved about 4 points. The expense ratio fell to 33.4% from 34.6% a year ago and 35.2% in Q1. Net investment income climbed 17.3% to $11.4 million on a larger asset base. Capital metrics are excellent:
- book value per share reached $20.22, up 42.9% year over year;
- statutory surplus rose to $474.9 million from $439.4 million last quarter;
- debt-to-capital improved to 10.5%.
Annualized ROE fell to 35.1% from 49.2%, but only because average equity grew 42.2%.
The top line is where bears have legitimate ammunition. Florida commercial residential premiums in force fell about 16%, worsening from declines of 12.7% in Q2 and 7.8% in Q1. Management expects Florida commercial renewal rates to fall another 10% to 18% in 2027. Gross premiums written fell 3.1%, versus a 2.6% decline in Q1. In Q1, management said written premium would turn positive by Q2 or Q3 and for the full year; that expectation was not reaffirmed. Personal lines policy-count growth, previously framed for "coming quarters," is now targeted for 2027. That growth will also face more than 20 new Florida entrants expected to shift from depopulation takeouts to voluntary writing next year. Personal lines are stabilizing: Q3 policy losses were less than half the year-ago decline, and average premium rose about 5%. Still, that is stabilization, not growth.
The forward catalysts are mostly on the cost side. Management indicated 2027 reinsurance pricing could fall another 5% to 8%, and the NBIC net quota share will be trimmed another 5% to 7% at year-end. Both should support net premiums earned even if gross premiums keep shrinking. Diversification is early-stage but real:
- Texas excess and surplus lines launched in July and wrote 86 policies, and management said it could scale faster than California, which took about four years to reach $40 million;
- New Jersey commercial in-force premium is up 12% year to date;
- South Carolina commercial launched.
On capital, the board authorized a new $50 million buyback for 2027. However, Q3 repurchases slowed to $3.3 million from $10 million in Q1, and unrealized bond losses widened by $22.7 million year to date.
Investor sentiment remains negative but improved modestly, moving to -0.21 from -0.28. The shares have barely moved since the last report, up 0.6% to $34.73 from the $34.54 post-report open. They still sit about 22% above the 200-day moving average of $28.51, so the market has preserved prior gains without extending them. Price and AVWAP trend readings remain positive, consistent with a stock that has consolidated rather than broken down.
The bottom line is that Heritage's earnings engine is being driven by cheaper reinsurance, disciplined underwriting, buybacks and reserve releases rather than by premium growth. That formula produced a sizable beat and a rapidly growing book value. However, Florida commercial erosion is accelerating, the premium inflection has slipped into 2027, and favorable development is a variable rather than a recurring tailwind. Further reinsurance savings can extend the margin story. The next leg likely depends on whether Texas, out-of-state commercial and personal lines can offset a deteriorating Florida market.
Read our earnings preview for Heritage Insurance Holdings: https://www.earningswhispers.com/article/HRTG/20948
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-19 | |
| Sep-17 | |
| Aug-05 | |
| Aug-05 | |
| Jul-24 | |
| May-28 | |
| May-07 | |
| May-07 | |
| Apr-21 | |
| Mar-12 | |
| Mar-10 |
