FormFactor Must Show Its Margin Leap Survives The HBM-To-DDR Mix Shift
FormFactor heads into its third-quarter report having done something it had never done before: crossing a 50% gross margin while running at better than a $1 billion annual revenue pace. The question now is not whether the probe card maker can post a record quarter. Management has all but promised one. The question is how much of the current profitability is durable, and how much rests on one-time help and a memory mix that is moving in the wrong direction.
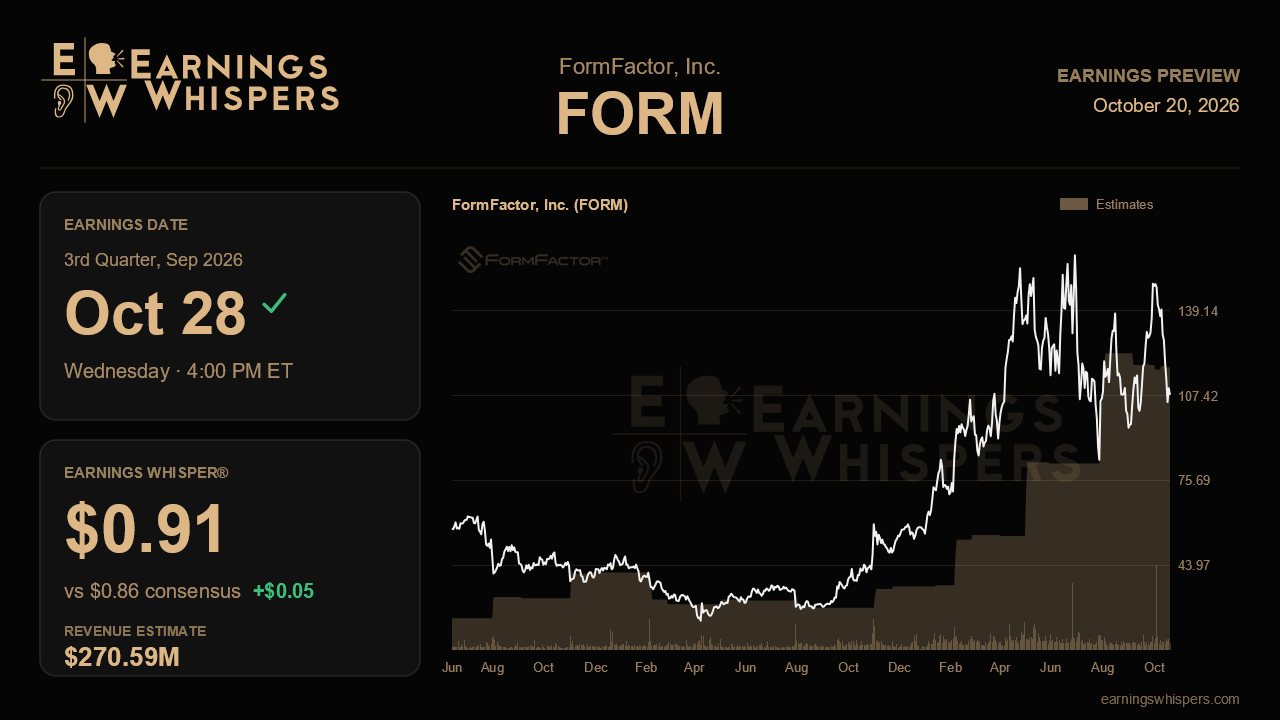
Wall Street expects non-GAAP earnings of $0.86 per share on revenue of $270.6 million, which would be about 33.5% growth from the $202.7 million reported a year ago. Those figures sit almost exactly at the midpoint of management's guidance of $0.77 to $0.95 per share and $260 million to $280 million in revenue. In other words, analysts have simply adopted the company's own outlook. The Earnings Whisper of $0.91 is a bit more demanding, pointing toward the upper half of the range and suggesting that the real bar is a beat, not an in-line print. Given that FormFactor topped its second-quarter revenue midpoint by $18.2 million, that expectation is understandable, though it leaves less room for error than the consensus implies.
Gross margin is the number that deserves the closest reading. Management guided to roughly 54% for the quarter, up from 53.3% last time, but it was candid that around 300 basis points of that comes from non-recurring tariff refunds worth $7 million to $9 million. The second quarter also got a lift from precious-metal reclaim. Strip those out and the underlying baseline is closer to 51%. A reported margin near 54% will look impressive, but the more telling signal is whether the core business holds around that 51% level while DRAM revenue stays flat and shifts from high-value HBM probe cards toward lower-value DDR. Memory makers are redirecting scarce wafer starts to chase DDR pricing, and evidence that this mix swing is costing more margin than expected would challenge the story of a structurally higher profit base.
The offsets are the newer growth engines, and this report should show whether they are arriving on schedule. GPU probe cards, which spent much of last year in qualification, were said to be shipping production units at the world's largest foundry in the second half. Co-packaged optics revenue was lifted from a $10 million to $20 million range to well above $20 million for the year, with more than $20 million expected by the end of the third quarter. HBM demand broadened to two customers using SmartMatrix. Confirmation that the CPO milestone was hit and that GPU revenue is contributing would validate the thesis that FormFactor is diversifying beyond memory cycles. Any slippage would matter more than a few cents of EPS, because these programs underpin the new 2030 target of $1.6 billion in revenue, 55% gross margin and $5 in EPS. Comments on supply constraints and the Farmers Branch site, slated to come online this quarter with ramp inefficiencies through 2027, will shape how investors model the bridge to that target.
Sentiment has warmed noticeably, rising from essentially neutral before the last report to modestly bullish now. The stock is up 8% since the prior release, about twice the S&P 500's gain, yet at $110.16 it trades below its 200-day moving average of $112.20 and far from its post-earnings high of $151.18. That pattern suggests investors embraced the narrative initially and then grew cautious, leaving the shares nearer the lower half of a wide range.
Ultimately, the report hinges on whether FormFactor can show that new GPU and optics revenue is filling the gap left by a less favorable memory mix, keeping underlying margins near 51% once the one-time benefits are set aside. If it can, the record numbers will look like a foundation rather than a peak.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-12 | |
| Oct-12 | |
| Oct-07 | |
| Oct-02 | |
| Oct-01 | |
| Oct-01 | |
| Sep-30 |
FormFactor Stock Jumps As Chip-Gear Firm Gets Fresh Buy Rating
FORM +9.59%
Investor's Business Daily
|
| Sep-30 | |
| Sep-30 | |
| Sep-30 | |
| Sep-21 | |
| Sep-15 | |
| Sep-14 | |
| Aug-12 |
