FormFactor Beats Again And Lifts Its Margin Baseline, But Maxed-Out Capacity Flattens The Near-Term Ramp
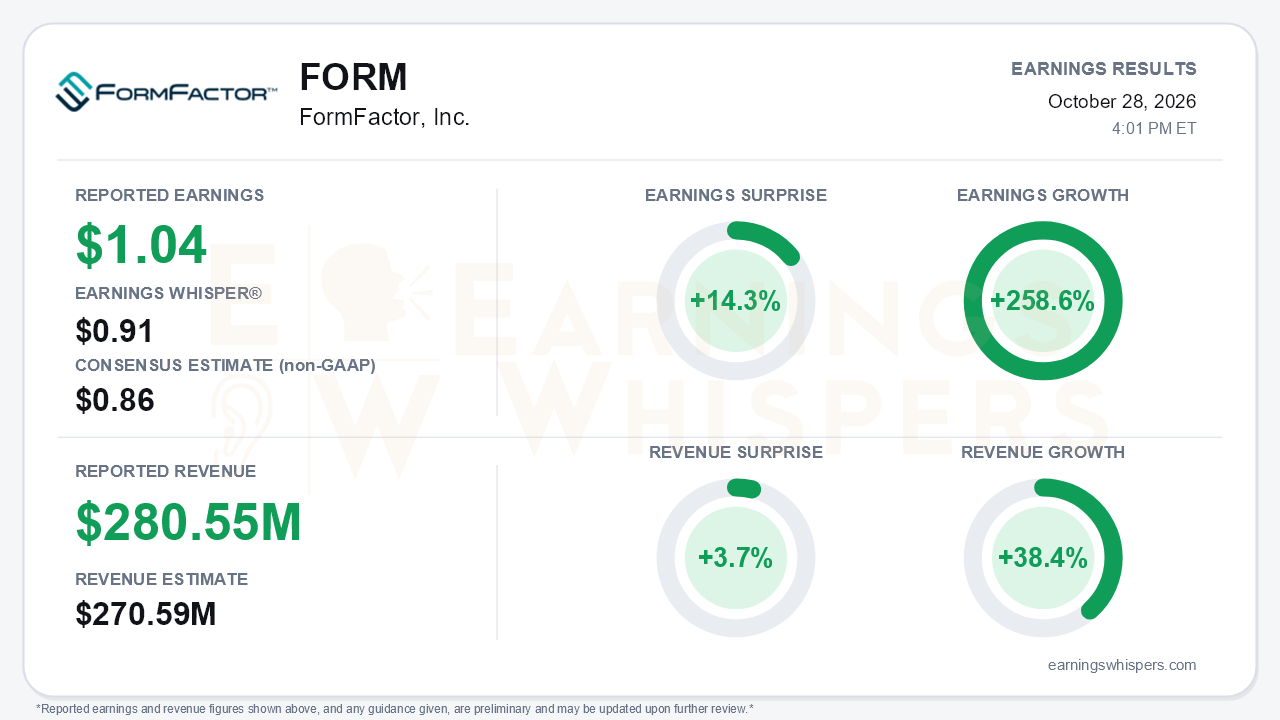
FormFactor delivered another clean beat in the third quarter. Non-GAAP earnings of $1.04 per share topped the $0.86 consensus by 14.3% and cleared the $0.91 Earnings Whisper number. Revenue of $280.55 million beat the $270.59 million consensus by 3.7%. Earnings grew 258.6% year over year and revenue grew 38.4%, and revenue landed above the top of management's $260-280 million guidance range. It was the company's fourth straight quarterly revenue record, following $215.2 million, $226.1 million and $258.2 million in the prior three quarters. The central tension is that this is a business running into a physical ceiling. Management said its existing manufacturing footprint is approaching capacity limits. The fourth-quarter outlook of $285 million, plus or minus $10 million, implies only modest sequential growth, and non-GAAP EPS guidance of $0.95 sits below the quarter just reported. Earnings Whispers characterizes the outlook as in line, not a raise.
The quality of the beat deserves some scrutiny on margins. Non-GAAP gross margin jumped to 56.5% from 53.3% in the second quarter, 49% in the first quarter and 41.0% a year earlier. According to the call, however, roughly 380 basis points of that came from non-recurring items, including tariff refunds and favorable quantum subcomponent costs. That explains why fourth-quarter gross margin guidance steps down to 54%. Still, the more important number moved the right way. Management lifted its underlying baseline non-GAAP gross margin to about 53%, from roughly 51-51.5% on the prior call, which is a structural improvement rather than a one-time windfall. GAAP results were also strong: net income of $73.8 million, or $0.93 per share, versus $0.20 a year ago, despite $6.4 million in factory start-up costs and continued restructuring charges. Operating cash flow of $104.3 million and free cash flow of $64.8 million were the best of the year. Deferred revenue rose to $36.6 million from $24.0 million, another sign of firm demand.
Beneath the headline, the demand picture broadened. Foundry & Logic grew about 10% sequentially on data center CPUs and is guided higher again in the fourth quarter. One data center CPU customer is approaching 10%-of-revenue status on agentic AI demand. GPU probe cards progressed from near-qualification in the first quarter to multi-million-dollar shipments to a leading foundry, setting up potential GPU and custom ASIC share gains in 2027. Systems revenue hit a record $59.5 million, up 23% sequentially, with 61% gross margin, driven by co-packaged optics. Management has now raised its 2026 Triton/CPO revenue expectation for the fourth time this year, from an initial $10-20 million to more than $30 million. The soft spot was memory: HBM revenue declined on a mix shift toward DDR, and the call acknowledged market chatter about HBM de-specification.
The forward catalysts are substantial. The Farmers Branch factory shipped its first production unit ahead of schedule, pulling first revenue into the fourth quarter. It is expected to exit 2027 with roughly $400 million of annual probe card capacity. After quarter-end, Teradyne expanded its partnership with FormFactor and made a $300 million equity investment. Combined with nearly $400 million in cash and investments, that gives the company ample funding for the build-out.
The risks are equally clear. 2027 gross margin is guided roughly flat at about 53%, because ramp inefficiencies at Farmers Branch offset volume leverage, with accretion coming only after the initial ramp. 2026 Farmers Branch capex was cut to $100-110 million from $140-170 million, but that reflects timing rather than scope, so the spending shifts into 2027. CPO demand also remains concentrated in a single ecosystem.
The market setup is more complicated than the surprise implies. Shares entered the report at $106.85, up just 4.8% since the open after the July report. That modest net gain hides extreme volatility. The stock bottomed at $92.05 on September 3, surged to $151.18 by October 2, and then surrendered most of that spike to sit 29.3% below the high and 5.8% below its 200-day moving average. Investor sentiment improved from essentially neutral to modestly positive, a constructive but hardly euphoric shift. The Earnings Whispers trend readings lean positive on sequential growth and momentum, while AVWAP remains negative, consistent with a stock whose fundamentals have outrun its recent price action.
The bottom line is that FormFactor's quarter strengthened the long-term story more than the near-term numbers. A higher margin baseline, accelerating photonics and GPU traction, an early Farmers Branch start and Teradyne's $300 million vote of confidence all improve the setup. However, investors must now accept a digestion period. Capacity constraints cap fourth-quarter growth, one-time margin benefits roll off, and 2027 margins stay flat during the ramp. With the stock well off its October peak, the debate is less about demand and more about how quickly new capacity converts that demand into earnings.
Read our earnings preview for FormFactor, Inc.: https://www.earningswhispers.com/article/FORM/20936
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-22 | |
| Oct-20 | |
| Oct-12 | |
| Oct-12 | |
| Oct-07 | |
| Oct-02 | |
| Oct-01 | |
| Oct-01 | |
| Sep-30 |
FormFactor Stock Jumps As Chip-Gear Firm Gets Fresh Buy Rating
FORM +9.59%
Investor's Business Daily
|
| Sep-30 | |
| Sep-30 | |
| Sep-30 |
