Encompass Health Aims For A Fourth Guidance Raise As Street Stays Below Its Outlook
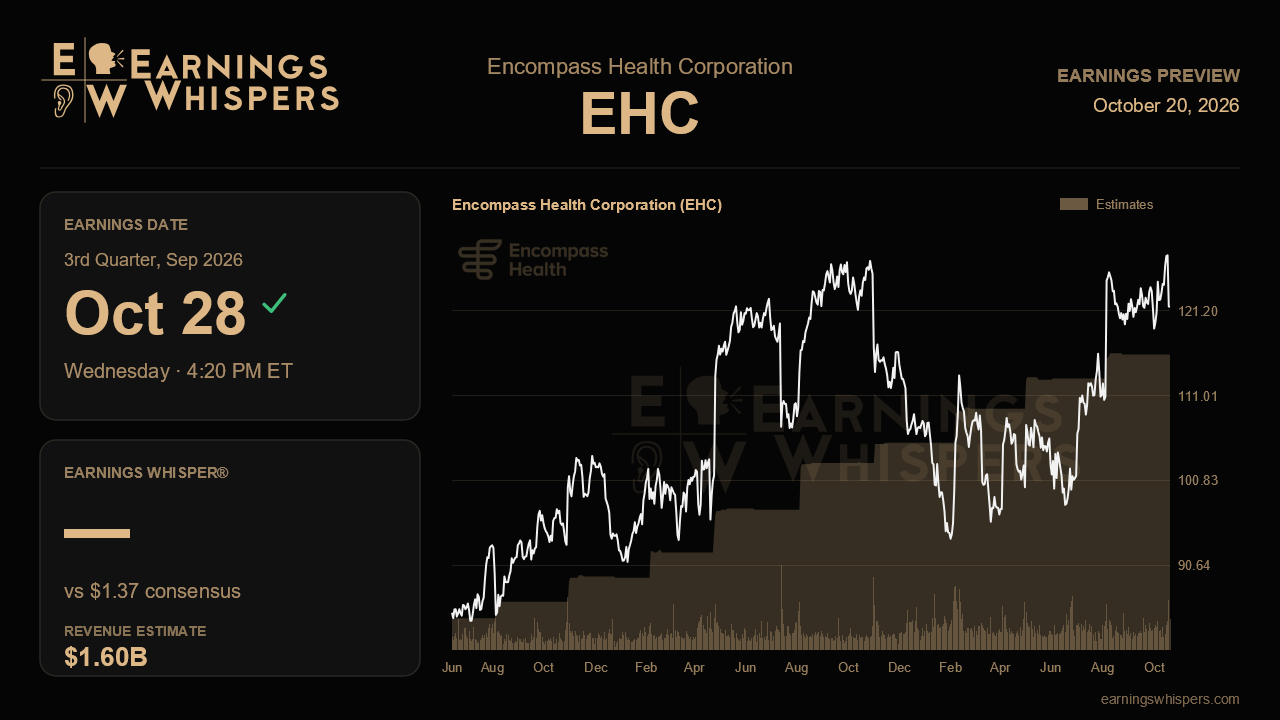
Encompass Health has raised its full-year outlook three times in a row, and yet Wall Street still does not quite believe it. Heading into its third-quarter report after the close on October 28, the consensus full-year earnings estimate of $5.96 per share sits below the bottom of management's own $6.02 to $6.25 range. That gap is the central tension of this report. Either analysts are building in a cushion for seasonal softness and cost pressures, or the rehabilitation hospital operator is about to make them catch up again.
For the quarter itself, the Street expects earnings of $1.37 per share on revenue of about $1.60 billion, up 11.4% and 8.3%, respectively, from a year ago. That is solid, high-single-digit top-line growth with modest operating leverage, roughly in line with the pace management delivered in the second quarter, when revenue climbed 9.6% and adjusted earnings rose 10.7%. The sequential step down from last quarter's $1.55 is consistent with the usual summer dip in inpatient volumes. Full-year revenue consensus of $6.43 billion sits in the lower half of the $6.41 billion to $6.49 billion guidance, which suggests analysts are less skeptical about demand than about how much of it reaches the bottom line.
The volume story is the place to start. Last quarter the company posted record occupancy of 77.4%, nearly three points higher year over year, and the usual seasonal decline from the first quarter to the second was notably shallower than in prior years. Same-store discharge growth also accelerated to 2.8% despite tougher comparisons. If third-quarter occupancy holds up similarly well against its normal summer slide and discharge growth stays near that level, the case for another raise gets much stronger. A sharper seasonal drop, or discharge growth slipping back toward the low 2% range, would suggest the first half was flattered by unusually favorable conditions.
Costs are the counterweight. Management lifted its salary and benefits per employee growth assumption to 3.5% to 4.0% as more staff move up its career ladder, and it acknowledged that savings from reducing contract labor have largely run their course. The upside is retention: nursing turnover fell to a 12-year low and therapist turnover to a five-year low. Margins this quarter will show whether stable staffing is offsetting higher wages. The provider tax benefit was also trimmed by roughly $11 million after retroactive Florida Medicaid adjustments, so any further slippage there would hurt credibility. Managed care adds another layer, with the admit-and-appeal approach to Medicare Advantage denials winning about 89% of adjudicated cases and now being scaled, while Veterans Affairs volume jumped a third last quarter. Continued progress on both would show the company is turning a structural payer headwind into incremental volume.
Forward-looking commentary matters too. Medicare pricing of roughly 2.3% took effect October 1, the same day North Carolina's certificate-of-need repeal opened what management called a major new growth market, with 15 targeted markets and three parcels already under contract. Updates on that pipeline and any early framing of 2027 will shape how investors value the longer runway beyond this year.
The stock has not rewarded the last beat-and-raise. Shares are down 2.5% since the prior report, trailing the S&P 500 by two points, and at $121.71 sit in the lower half of a post-earnings range of $118.39 to $129.96, though still well above the 200-day moving average. Sentiment remains bearish but slightly less so than a quarter ago. That leaves a reasonably low bar for a positive reaction if results confirm the trend. Ultimately, the report hinges on whether occupancy and discharge momentum stay strong enough through the seasonally weak quarter to absorb rising wage costs and justify a fourth consecutive increase in guidance.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-19 | |
| Oct-06 | |
| Oct-01 | |
| Sep-24 | |
| Sep-15 | |
| Aug-10 | |
| Aug-10 | |
| Aug-05 | |
| Aug-05 | |
| Jul-23 | |
| Jul-09 | |
| Jun-24 | |
| Jun-11 | |
| Jun-09 |
