Encompass Health Raises Guidance A Third Time As EBITDA Growth Accelerates, But Investor Sentiment Sours
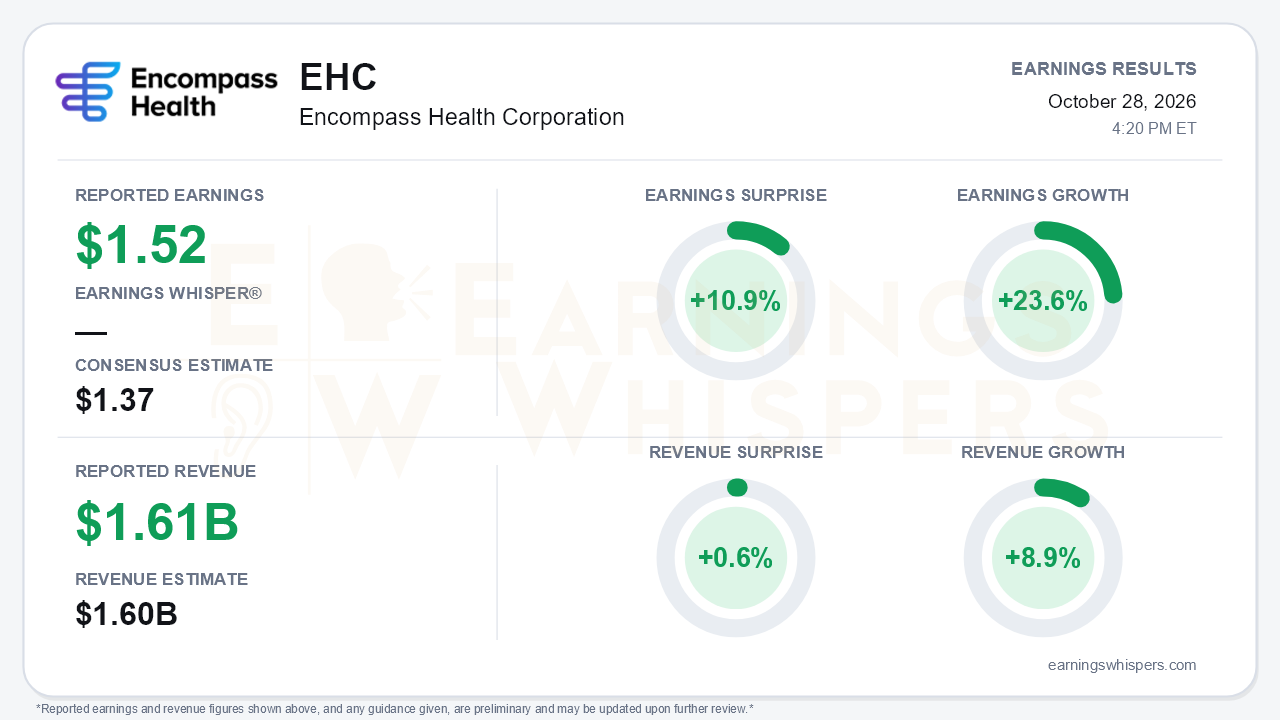
Encompass Health delivered a third-quarter beat that was stronger in profit than in revenue. Adjusted earnings came in at $1.52 per share against a $1.37 consensus, a 10.9% surprise. Revenue of $1.61 billion edged past the $1.60 billion estimate by 0.6%. Earnings growth accelerated to 23.6% year over year from 10.7% in the second quarter. Revenue growth, however, eased to 8.9% from 9.6% in Q2 and 9.0% in Q1. That divergence is the central story. The top line is growing steadily rather than accelerating, while operating leverage is improving. Adjusted EBITDA rose 15.5% to $346.6 million after 9.2% growth in Q2, and management raised full-year guidance for the third consecutive quarter.
The quality of the beat holds up well under scrutiny, though not every dollar came from operations. GAAP diluted EPS from continuing operations was $1.51, nearly identical to the adjusted figure, so the quarter was not built on add-backs. The share count did help. Diluted shares fell to 99.7 million from 102.3 million, supported by $203.7 million of buybacks year to date versus $81.7 million a year ago. That flattered per-share growth relative to the 18.8% increase in income from continuing operations attributable to the company. More impressive is what the quarter absorbed. A $9.2 million reversal of a Florida Medicaid directed-payment accrual and a bad-debt rate that climbed to 2.7% from 2.3% would normally pressure results. EBITDA still grew nearly twice as fast as revenue. Third-quarter adjusted free cash flow jumped 51.2% to $263.4 million. The year-to-date gain is a more modest 8.9%, which suggests some quarterly timing benefit.
The operating drivers were broad-based:
- **Volume:** Discharges rose 5.7%, with same-store growth of 3.0%.
- **Pricing:** Net patient revenue per discharge increased 4.0%, driven by acuity. Neuro grew 9.3% and stroke 5.1%.
- **VA:** VA volume grew 21%, the sixth straight quarter at 20% or better.
- **Managed care:** The pricing assumption was raised 125 basis points at the midpoint to 3.5%-4%.
- **Labor:** Premium labor declined for a 16th consecutive quarter, and contract labor fell to 0.9% of FTEs, the lowest since late 2020.
There are softer spots. Medicare Advantage discharges fell 1.1%. Turnover ticked up to 20.7%. Management also signaled diminishing returns from further premium-labor reductions and moderating pricing growth as acuity and payer-mix gains anniversary in Q4.
The forward catalysts are increasingly about capacity. North Carolina's certificate-of-need repeal took effect October 1. The company has prioritized 15 markets and now has six parcels under contract, up from three last quarter. The first two small-format hospitals were named in Conroe and Richmond, Texas, with roughly 200 potential locations identified. The announced pipeline beyond 2026 has grown each quarter this year to 15 hospitals and 654 beds. Management said it could reach the top of, or exceed, its 6-10 hospitals-per-year range. The Medicare Advantage admit-and-appeal strategy is expanding to all hospitals for stroke patients, with an 87% overturn rate. A new stroke guideline favoring inpatient rehabilitation over skilled nursing adds a demand tailwind.
Bears have legitimate ammunition, though. The bigger risk is the expansion of the Review Choice Demonstration into Palmetto's jurisdiction JJ on January 1, 2027. That will cover 75 more hospitals, with 100% prepayment review in the first cycle, and management raised concerns about the contractor's administrative capacity. Combined with the billing-system conversion that inflated bad debt and pushed receivables up $89.5 million year to date, that sets up potential cash-flow and bad-debt volatility in the first half of 2027. The expected contribution from 2026 net provider taxes has shrunk from about $21 million to about $3 million. Pre-opening costs were also guided higher, to $20-24 million.
The market setup is more complicated than the surprise implies. Investor sentiment entered the report negative and deteriorated further, falling from -0.27 to -0.41. That is a meaningful move toward skepticism despite repeated guidance raises. Shares sat at $122.09 at the time of the report, down 2.2% from the open after the August report, so the stock has made no net progress over a quarter of solid execution. It nonetheless remains 11.3% above its 200-day moving average of $109.68, and the longer-term price trend is still positive, while the AVWAP reading is negative. That pattern reflects a stock holding its broader uptrend but struggling to attract fresh buying.
The bottom line is that Encompass Health's third quarter strengthened its fundamental case. Profit growth accelerated, guidance moved higher again, and the development pipeline is widening on the back of regulatory openings in North Carolina and the new small-format model. Investors' souring mood is not irrational. Slowing revenue growth, fading pricing tailwinds, and a 2027 prepayment-review overhang give skeptics a credible counterweight to this quarter's operating leverage.
Read our earnings preview for Encompass Health Corporation: https://www.earningswhispers.com/article/EHC/20928
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-26 | |
| Oct-22 | |
| Oct-22 | |
| Oct-20 | |
| Oct-19 | |
| Oct-06 | |
| Oct-01 | |
| Sep-24 | |
| Sep-15 | |
| Aug-10 | |
| Aug-10 | |
| Aug-05 |
