Community Health's Uninsured Surge Puts Freshly Cut EBITDA Guidance To An Early Test
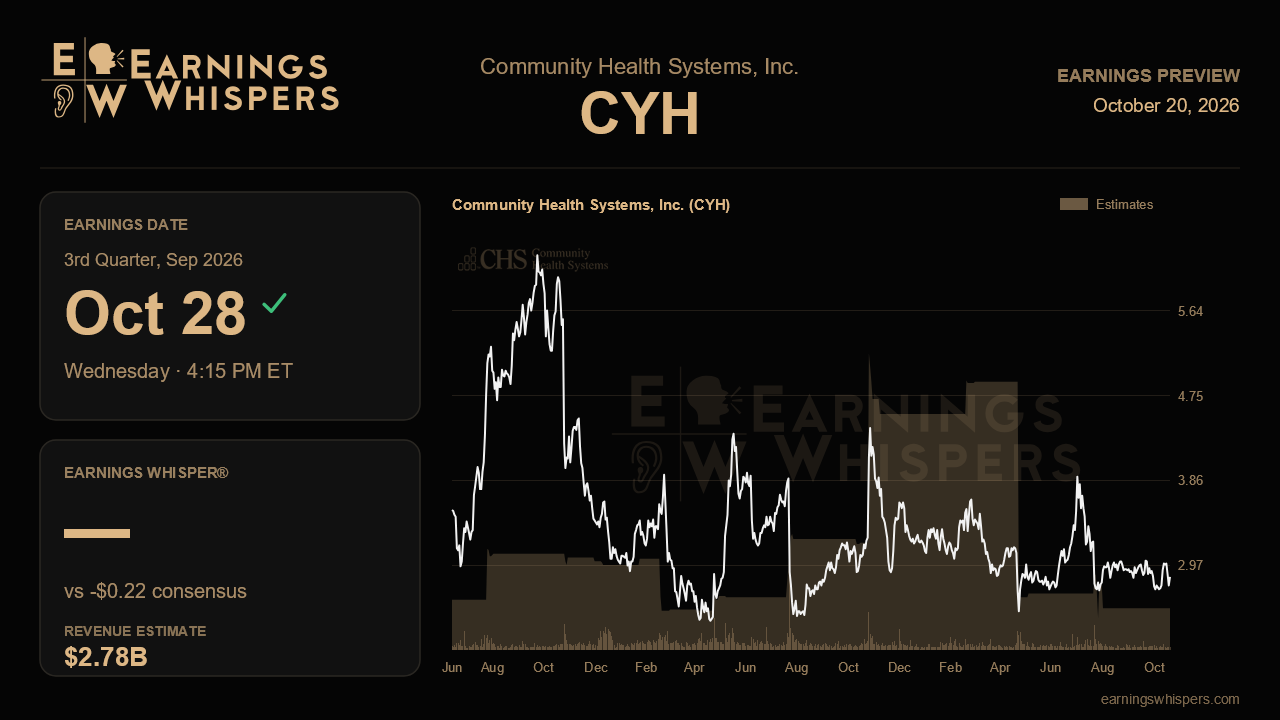
Three months ago, Community Health Systems did something it had avoided all cycle: it lowered its full-year EBITDA outlook. The culprit was not a lack of patients. Same-store adjusted admissions actually rose 2.9%, the best reading in a year. The problem was who those patients were. Roughly half of the growth came from uninsured and self-pay visitors who pay little or nothing, while higher-margin elective surgeries kept slipping. The third-quarter report, due after the close on October 28, is the first chance to see whether that reset was conservative enough or merely the first step down.
The Street is braced for a loss of about $0.22 per share on revenue near $2.78 billion. That compares with a profit of $1.27 a year ago on $3.09 billion in sales, a 117% earnings decline and a roughly 10% revenue drop that partly reflects the company's ongoing divestitures, including the $110 million sale of four Arkansas hospitals. Sequentially, the bar is a modest step down from the second quarter's $0.19 loss and $2.83 billion in revenue. Management's revised framework calls for $1.3 billion to $1.375 billion in adjusted EBITDA and $11.4 billion to $11.6 billion in net revenue for the year, down from an initial $11.6 billion to $12.0 billion. The revenue consensus looks consistent with a company tracking toward the lower half of that range, so the debate is less about the top line than about how much of it converts to profit.
Payer mix is the swing factor. Management lifted its estimated annual hit from the expiration of enhanced ACA subsidies to $50 million to $75 million, from $20 million to $30 million just one quarter earlier, conceding that disenrolled patients keep coming through the emergency room. Self-pay climbed to about 6% of visits, with the step-up concentrated in the second quarter. If that share stabilizes and net revenue per adjusted admission returns to positive territory after slipping 0.5%, the cut guidance starts to look prudent. If self-pay keeps rising, the volume story becomes a liability rather than a strength, since each additional uncompensated visit carries real cost.
Costs deserve equal scrutiny. Contract labor fell and supplies held near 14.2% of revenue, but medical specialist fees jumped 19% year over year to 5.6% of revenue, well above the company's 5% to 8% growth forecast and accelerating for four straight quarters. Another double-digit increase would undercut the cost discipline argument. On the positive side, state-directed payment programs in Georgia, Florida and Indiana have added $65 million to $70 million of previously unguided EBITDA, and management flagged possible further Florida upside. Elective surgery trends also merit attention: June brought positive surgical growth, yet inpatient surgeries fell 3.8% for the quarter amid weak consumer confidence. A sustained rebound in orthopedic and cardiac cases would be the cleanest sign of genuine recovery.
Cash and balance sheet details round out the test. Operating cash flow swung back to $87 million in the second quarter after a heavy first-quarter outflow, but insurers are slowing payments through pre-payment audits, and leverage edged up to 6.7 times even after tendering roughly $600 million of notes. Rising receivable days would make deleveraging harder.
Sentiment has warmed from deeply bearish before the last report to roughly neutral, yet the stock has slipped 2.1% since then, trailing the S&P 500 by nearly six points. At $2.76, it sits below its 200-day average of $3.06 and toward the lower end of its post-earnings range of $2.63 to $3.08. That suggests limited conviction rather than a high bar. Ultimately, the report turns on one question: did the uninsured surge plateau in the third quarter, leaving the trimmed EBITDA range intact, or does management need to cut again?
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-14 | |
| Sep-03 | |
| Sep-02 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 | |
| Jul-14 | |
| Jul-08 | |
| Jun-24 | |
| Jun-11 | |
| Jun-01 | |
| Jun-01 |
