Community Health Systems Misses Badly As Payor Mix Erodes, Cuts Guidance Again And Pulls Medium-Term Targets
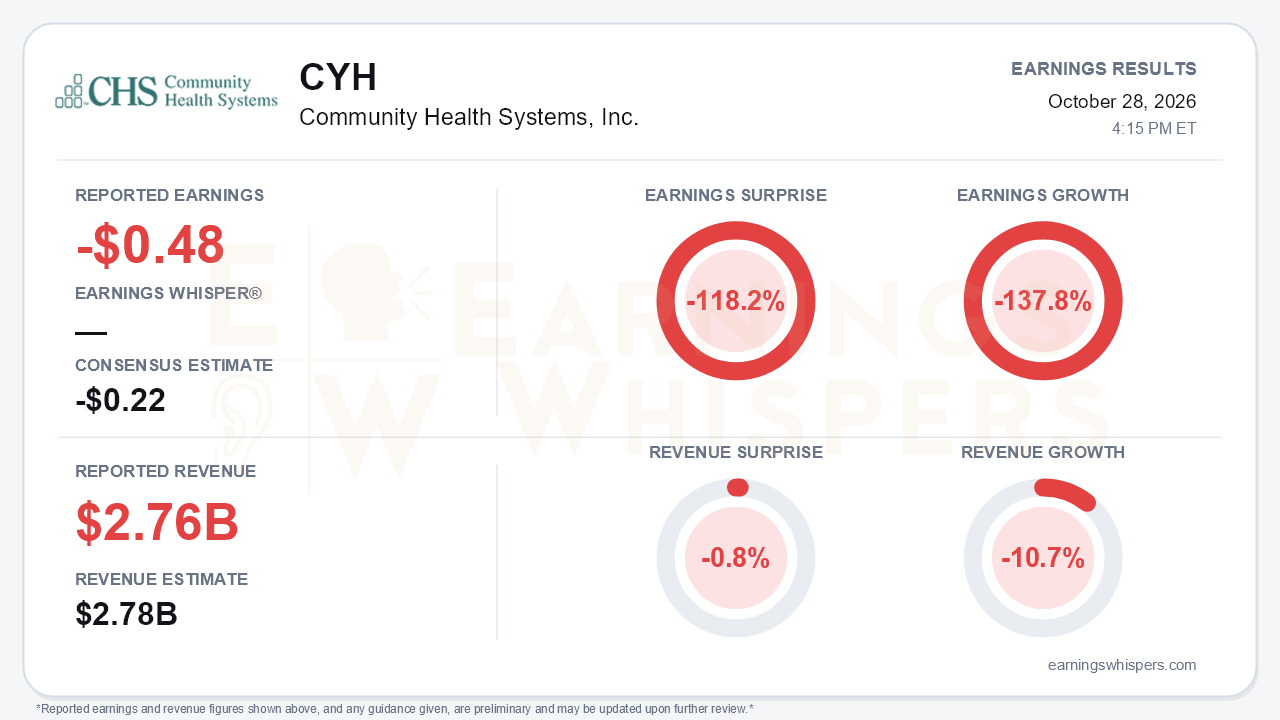
Community Health Systems delivered a quarter in which volumes improved but almost nothing else did. The hospital operator posted an adjusted loss of $0.48 per share, well short of the -$0.22 consensus. That is a 118.2% earnings miss, and it marks a swing from adjusted income of $1.27 a year ago, a 137.8% decline. Revenue of $2.757 billion missed the $2.78 billion consensus by 0.8% and fell 10.7% year over year. On a GAAP basis, the company lost $0.63 per share versus a $0.96 profit last year. The central tension is that CHS is treating more patients while earning less on each of them. Management then cut full-year guidance for the second straight quarter and withdrew its medium-term targets for reassessment.
The headline revenue decline is mostly a portfolio story. CHS has divested ten hospitals so far in 2026, and same-store revenue actually rose 3.8%. The profit picture is the real problem. Adjusted EBITDA fell to $280 million from $376 million, and margin compressed to 10.2% from 12.2% a year ago and 11.7% in the second quarter. Some of that comparison reflects divestitures and a $28 million legal settlement in the prior-year period. Even so, the call analysis put the core decline at roughly 7%. Other operating expenses jumped to 29.3% of revenue from 26.9%, driven by higher medical specialist fees and supplemental reimbursement program expense. Income from operations dropped 39.9%. The one bright spot was cash: operating cash flow of $155 million more than doubled from $70 million.
Beneath the surface, the volume recovery is real but low quality. Same-store adjusted admissions rose 3.6%, accelerating from 2.9% in Q2 and -0.5% in Q1. Surgeries turned positive at +2% after several negative quarters, and clinic visits grew 7.9%. However, net revenue per adjusted admission rose only 0.2%, versus 3.7% in the first quarter. Management said roughly half of the volume growth came from uninsured patients, while higher-margin orthopedic and general surgery electives were deferred. CEO Kevin Hammons acknowledged in the release that payor mix and acuity "did not develop as expected." The estimated EBITDA hit from ACA exchange disenrollment keeps climbing: $20-30 million in February, $50-75 million in Q2, and $80-90 million now. Medical specialist fees rose 13%, far above the 5-8% plan.
The guidance trajectory is what bears will focus on. Full-year adjusted EBITDA guidance is now $1.225-1.275 billion. That is down from $1.3-1.375 billion in July and $1.34-1.49 billion at the start of the year. Revenue guidance has slid from $11.6-12.0 billion to $11.3-11.5 billion. Operating cash flow guidance of $100-300 million compares with $600-700 million originally. The latest cut was reportedly in line with estimates, which suggests the Street had partly anticipated it. Still, removing the medium-term targets removes a valuation anchor. Leverage rose to 7.2x from 6.6x at year-end, despite $810 million of debt reduction. Divestiture proceeds are being absorbed by shrinking EBITDA rather than translating into balance-sheet progress.
Management did offer a 2027 bridge. The pieces include:
- a roughly 5% net Medicare outpatient rate increase;
- solid commercial rate updates;
- expected recovery of deferred electives once deductibles reset;
- $25-30 million in Rural Health Transformation Program awards;
- more than $100 million of annualized structural cost savings.
Operational indicators are also improving. Physician turnover is down more than 40%, and contract labor and wage rates came in below plan. Against that, the company faces Medicaid work requirements and provider-tax cuts under OBBBA, persistent slowdowns in payer claim payments, and an unrecognized Florida supplemental payment program.
Investor sentiment remained negative but improved meaningfully, rising from -0.50 to -0.36 heading into the print. That may reflect expectations that the bad news was largely priced in. The stock, at $2.66, is down 5.7% since the open following the July report and sits 12.6% below its 200-day moving average of $3.04. Price and AVWAP trend readings remain negative. The market had been discounting further deterioration before this guidance cut arrived.
The bottom line is that CHS answered the volume question but not the profitability question. Rising admissions, a return to surgical growth, and better quarterly cash flow give management something to build on. However, deteriorating payor mix, escalating exchange headwinds, rising specialist costs, a third consecutive guidance cut, and 7.2x leverage mean the turnaround now rests almost entirely on 2027 tailwinds. Until those tailwinds show up in revenue per admission and EBITDA margin, skeptics have the stronger evidence.
Read our earnings preview for Community Health Systems, Inc.: https://www.earningswhispers.com/article/CYH/20923
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-14 | |
| Sep-03 | |
| Sep-02 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 | |
| Jul-14 | |
| Jul-08 | |
| Jun-24 |
