Cohu's AI Thermal Ramp Faces A Margin Test As Stock Lags Its Raised Outlook
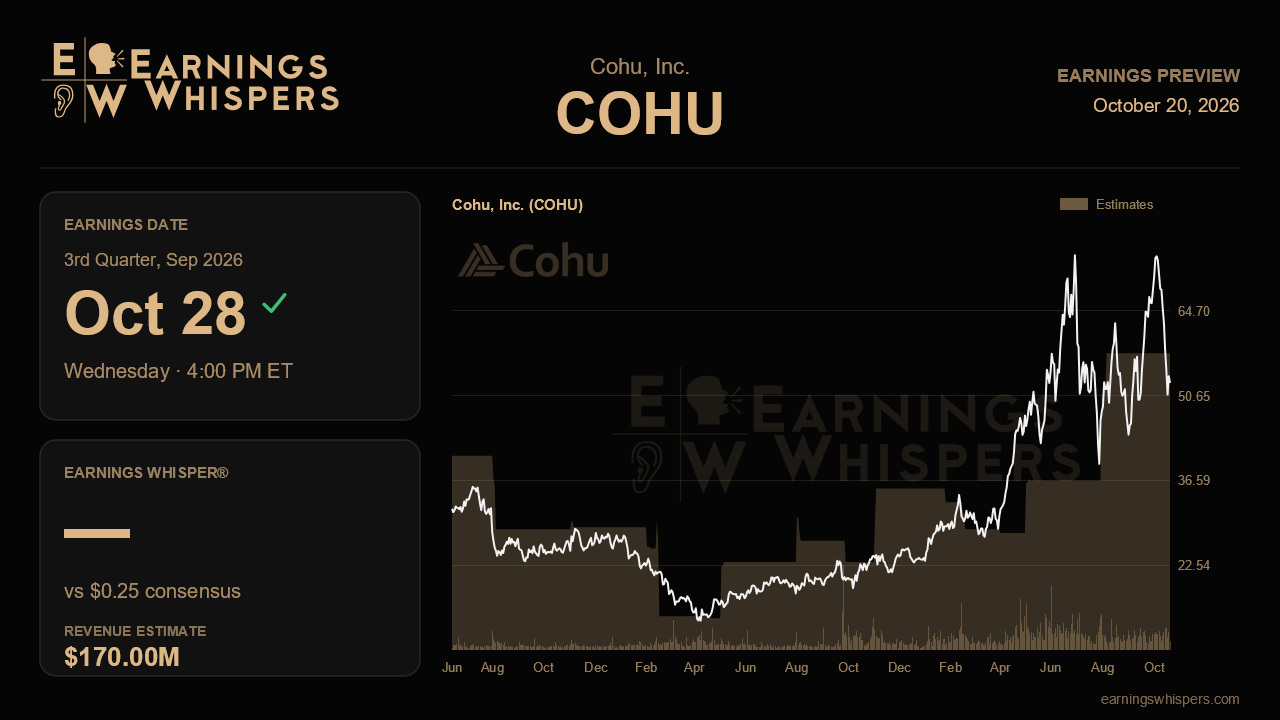
Cohu enters its third-quarter report with an unusual disconnect. Management has raised its full-year growth target twice, lifted its high-performance computing revenue estimate three times, and guided to the strongest quarter in years. Yet the stock has slipped 6.6% since the last report, trailing the S&P 500 by nearly 10 percentage points. The business narrative is accelerating while the share price is not, and the October 28 release, due after the close, is the next chance to show which side has it right.
The numbers themselves are not in much doubt. Consensus calls for earnings of $0.25 a share on revenue of $170.0 million, roughly a 35% jump in sales from a year ago and a swing from a $0.16 loss to a solid profit. That revenue figure sits exactly at the midpoint of management's $163 million to $177 million range. The Street moved up from about $148.5 million once guidance landed, so analysts are no longer ahead of or behind the company. They have simply adopted its forecast. A result near the top of the range would extend the beat-and-raise pattern. Anything near the bottom would be the first wobble in a story built on upward revisions.
The more revealing details lie beneath the headline. The engine is the AI and HPC thermal-handler business, where management last projected $100 million to $110 million in full-year revenue, up from an initial $60 million to $85 million. The computing pipeline has grown to about $850 million across roughly 19 customers, and qualified opportunities nearly doubled to around $190 million across four customers. The report should show that pipeline turning into orders, not just conversations. Early in the quarter Cohu booked a $26 million Eclipse order from a single customer, which is slated to ship largely in the fourth quarter. Its timing and any follow-on business will help show whether the HPC estimate has room to rise again. Neon HBM inspection, running near $20 million for the year, offers a second read on AI-related demand.
Capacity is the catch. Management said HPC output is effectively maxed for the second half until the Malaysia expansion doubles production by year-end. That means further demand may show up as bookings and FY27 visibility rather than near-term revenue. Progress on that buildout matters as much as the quarter's sales. So does the 80% test-cell utilization figure reached last quarter, a level that historically unlocks broader test-equipment spending. Holding or improving it would support the idea that the recovery is spreading. Core industrial orders rose 87% year over year, while automotive remains the laggard, with orders down 24% and recovery pushed into mid-2027.
Margins are the likeliest pressure point. Gross margin eased from 46.5% to 45.5%, and guidance calls for about 45% as costlier memory chips and longer lead times bite. That compares with a 48% target at normalized volume. Talks about passing costs to customers had only just begun, and operating expenses have climbed to roughly $54 million a quarter to fund the HPC push. If gross margin holds at 45% or improves while revenue rises 14% sequentially, the operating leverage case stays intact. Slippage below guidance would explain why the stock has struggled despite strong top-line momentum.
Sentiment has warmed modestly, rising to 32.4% bullish from 27.1%. The shares sit at $53.87, above the 200-day moving average near $45.91 but well below the post-report high of $75.72. Much of the earlier AI enthusiasm has been unwound, which lowers the bar for a positive reaction. With an Investor Day set for November 10, the central question is whether Cohu can grow revenue in line with its guidance without giving back gross margin. A clean answer would reconnect the stock with a business that, by management's account, is still getting better.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-14 | |
| Oct-08 | |
| Sep-29 | |
| Sep-15 | |
| Sep-14 | |
| Aug-12 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-16 | |
| Jul-09 | |
| May-19 | |
| May-18 |
