Cohu's Beat-And-Raise Delivers A 2027 Growth Framework, But Q4 Margin Pressure Shows The Cost Of Scaling Eclipse
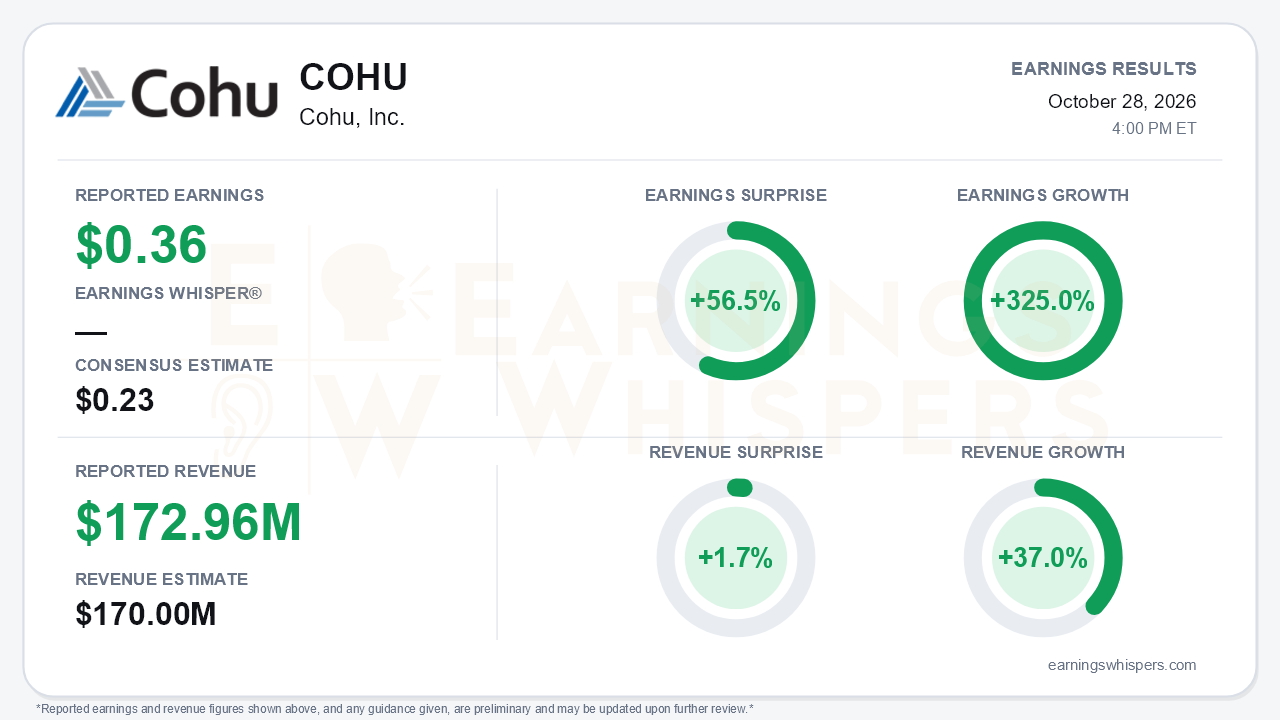
Cohu delivered the type of quarter that changes the conversation from recovery to scaling. Earnings Whispers normalized EPS came in at $0.36, beating the $0.23 consensus by 56.5% and growing 325.0% from a year ago, on revenue of $172.96 million that topped the $170.0 million consensus by 1.7% and rose 37.0% year over year. The company's own figures differ from the normalized number: Cohu reported non-GAAP EPS of $0.43 and GAAP diluted EPS of $0.22. On any of these measures, the direction is the same. A year ago Cohu lost $0.09 per share on a GAAP basis. It is now solidly profitable, and GAAP net income swung from a $4.1 million loss to $12.1 million. The modest revenue beat was not the main event. Guidance was. Fourth-quarter sales are expected at $178 million, plus or minus $7 million, up 46% year over year, and management offered a first 2027 framework calling for 30-40% growth.
The quality of the quarter holds up well. Operating leverage was the real story. Non-GAAP operating income rose to $25.5 million, or 14.7% of sales, from $15.1 million (10.1%) in the second quarter and $7.7 million (6.1%) a year ago. Adjusted EBITDA margin expanded to 16.6% from 12.3% sequentially, even though non-GAAP operating expenses grew less than $1 million quarter over quarter. Gross margin edged up to 45.7% non-GAAP from 45.5%. Bookings rose 126% year over year, led by a 318% jump in systems orders, and book-to-bill stayed above 1. Test cell utilization reached 82%, extending a steady climb from 76% at the end of 2025.
The call reinforced that this is an AI and high-performance computing story driven by the Eclipse thermal handler. Management raised its fiscal 2026 HPC revenue outlook to about $120 million. That outlook started at $60-85 million and has been lifted every quarter since. The annual HPC opportunity pipeline grew to roughly $1 billion from $850 million. The qualified portion rose to $230 million from $190 million, and opportunities in qualification jumped to $440 million from $250 million. New wins broaden the customer base beyond a single compute name:
- first interface orders from two leading hyperscalers;
- an initial device qualification at a major networking customer;
- DiamondX displacing an incumbent at a server PMIC customer;
- software ARR up 85% sequentially.
Management now targets HPC revenue at the high end of a $200-250 million range in 2027 and plans roughly three times the Eclipse output of 2026.
That growth comes with costs, and bears have legitimate ammunition. Fourth-quarter gross margin is guided to about 44%, down from 45.7%, as specialty components get pricier and lead times stretch. Quarterly opex rises to about $57 million from $53.5 million. Recurring revenue fell to 48% of the mix from 60% in the first quarter. That shift was expected as systems scale, but it makes the business more cyclical. Operating cash flow slipped to about $6 million, and receivables and inventories both climbed over the year. One compute customer still exceeds 10% of sales. The high end of the 2027 range depends on seven programs, worth about $340 million in annual systems revenue, clearing qualification between late November and early 2027. It also requires suppliers to ramp in step. The 2027 targets of 46-48% gross margin and roughly 50% incremental drop-through therefore assume today's margin pressure proves temporary.
The market setup is more complicated than the surprise implies. Shares surged from an inter-earnings low of $43.27 on September 2 to a 52-week high of $75.72 on October 5. They then gave back most of that move to enter the report at $50.98. That close is 32.7% below the peak and 11.6% below the opening price after the July report, although still 9.3% above the 200-day moving average. Expectations clearly ran ahead of the stock, then reset. Investor sentiment was essentially unchanged and moderately positive, edging to 0.284 from 0.271. The Earnings Whispers trend readings are mixed: momentum is positive while AVWAP remains negative, consistent with a stock still digesting its October spike.
The bottom line is that Cohu turned in a credible beat-and-raise and introduced a 2027 outlook that extends the growth story well beyond this quarter. Rising utilization, a deepening qualified pipeline and new hyperscaler and networking customers give that outlook substance. The near-term trade-off is real. Fourth-quarter margins are dipping, costs are rising, cash conversion is soft, and the 2027 upside depends on qualification timing and supplier execution. With shares already well off their October high, the November 10 Investor Day and those qualification milestones are the next tests of whether execution can catch up with the enthusiasm the stock briefly priced in.
Read our earnings preview for Cohu, Inc.: https://www.earningswhispers.com/article/COHU/20919
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-14 | |
| Oct-08 | |
| Sep-29 | |
| Sep-15 | |
| Sep-14 | |
| Aug-12 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-16 | |
| Jul-09 |
