Cimpress Must Prove Its Raised Targets Survive A Messy Quarter, Canva Ramp And Canadian Tariffs
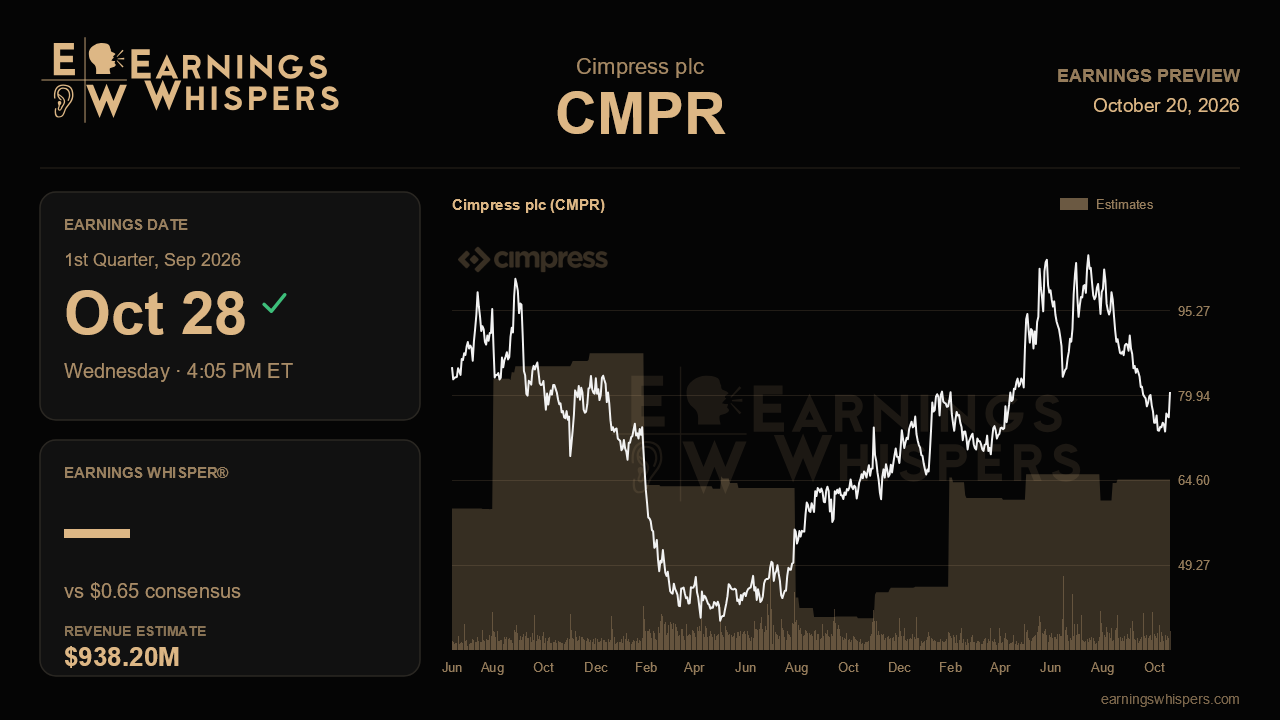
Cimpress heads into its fiscal first-quarter report with a credibility problem that has little to do with strategy and a lot to do with execution. Last quarter management sounded more confident than it has in years, lifting its fiscal 2028 adjusted EBITDA target to at least $615 million, formalizing fiscal 2027 guidance and unveiling a high-profile partnership with Canva. Yet the same quarter fell about $10 million short of its own EBITDA guide, full-year cash flow missed, and the stock has since slid 13.2% while the S&P 500 gained 4.1%. The October 28 report, due after the close, is the first chance to show the bigger promises were not built on sand.
The Street is looking for earnings of $0.65 per share on revenue of $938.2 million. That implies revenue growth of 8.7% and EPS more than doubling from $0.30 a year ago, a striking jump that owes much to an easy comparison and the GAAP noise in last year's quarter. The revenue figure sits comfortably above management's fiscal 2027 framework of at least 7% reported growth and at least 3% organic constant-currency growth, which makes sense given that acquisitions are now expected to add $165 million to $175 million of revenue and $18 million to $21 million of EBITDA this year. The gap between reported and organic growth is the first thing to dissect. If the headline beat comes mostly from deals like Saxoprint while organic growth drifts below 3%, the quality of the quarter will look thinner than the top line suggests.
The more important tests are operational. Management blamed the fourth-quarter miss on end-of-period items: a $4.7 million write-off of Canadian duty drawback receivables, $7.1 million of higher North American manufacturing startup costs, inventory write-downs and an incentive compensation adjustment. A clean quarter without fresh surprises would go a long way toward validating the claim that those were one-offs. Continued startup drag in North America, or another round of inventory or working-capital slippage, would challenge it, particularly after fiscal 2026 free cash flow landed at $122.4 million against a $130 million to $135 million guide. The fiscal 2027 plan calls for roughly $200 million of adjusted free cash flow, so early signs of working-capital discipline matter as much as EBITDA.
Canva is the new catalyst, and this report should offer the first real read on whether it is more than a press release. Vistaprint products launched in the US and Canada and were slated to reach more than 25 countries by the end of September. Investors should want evidence of new customer acquisition through that on-ramp, even if it is qualitative. Vistaprint's variable gross profit per customer, which rose 9% last quarter after gains of 7%, 9% and 13% earlier in the year, is the cleanest gauge of whether the push into elevated products and packaging is still working.
The wild card is the new 50% Section 338 tariff on certain Canadian goods, effective August 19 and excluded from guidance. Management described the product impact as small and under mitigation; any quantification, and whether it forces a guidance adjustment, will be closely parsed.
Sentiment has swung from modestly bullish before the last report to modestly bearish now, and shares at $76.03 sit below the 200-day moving average of $84.23 and near the bottom of a post-earnings range that ran from $71.70 to $104. That puts the bar lower than the confident tone of last quarter might suggest. The central question is simple: can Cimpress deliver a quarter clean enough to reaffirm at least $520 million of fiscal 2027 EBITDA without new excuses? If it can, the disconnect between rising targets and a falling stock becomes the story. If not, last quarter's optimism will look premature.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-20 | |
| Oct-15 | |
| Oct-06 | |
| Sep-09 | |
| Sep-01 | |
| Aug-28 | |
| Aug-12 | |
| Aug-06 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-16 | |
| Jul-02 | |
| Jun-10 |
