Century Communities Must Prove Its Summer Turnaround Survived Rising Rates And Fading Cost Tailwinds
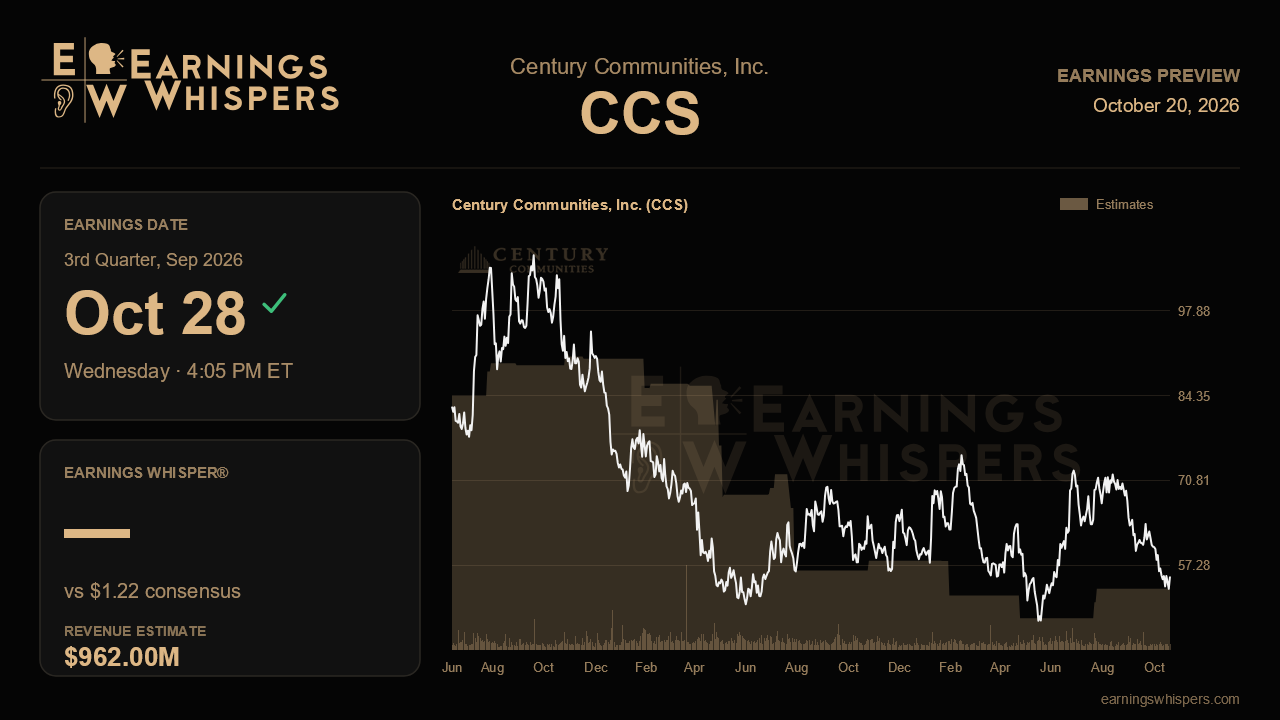
Three months ago, Century Communities delivered the kind of quarter that usually resets a homebuilder's story: deliveries blew past guidance, orders reaccelerated, incentives eased and management raised the low end of its full-year delivery outlook after cutting it just one quarter earlier. The market has responded by marking the stock down roughly 19% since that report, a 23-point gap against the S&P 500. When the company reports third-quarter results after the close on October 28, the question is whether that skepticism was justified or whether the operating recovery is sturdier than the share price implies.
The Street is not asking for much on the top line. Consensus calls for revenue of about $962 million, essentially flat with a year ago at a 1.9% decline but up from the $927.2 million reported last quarter. Earnings are a different matter. The $1.22 per-share estimate sits nearly 20% below the year-ago $1.52 and below the roughly $1.30 earned in the second quarter, which tells you analysts expect profitability to slip even as volume edges higher. Management has held its 2026 home sales guidance at $3.5 billion to $3.8 billion, and full-year consensus of $3.77 billion sits near the top of that range. That leaves little cushion: a soft fourth-quarter outlook or any trim to delivery targets would put the Street above management's comfort zone.
The earnings decline baked into estimates makes sense once you look past the headline strength of the last call. Adjusted gross margin improved to 20.0%, but both the first and second quarters were flattered by about 90 basis points from a warranty and rebate benefit that management said will not recur. Strip that out and the underlying margin gain was modest. Meanwhile, lumber has shifted from a tailwind to flat or rising, land development vendors have been asking for price increases, and management guided incentives flat rather than lower for the back half. A clean read on margins excluding the one-time help is the single most useful data point in this report. If underlying gross margin holds near the high teens with incentives steady around 12 percentage points of price, the cost initiative that cut direct construction costs 5% sequentially is doing real work. If margins slide further, the second quarter will look like a peak rather than an inflection.
Demand is the other test. Management flagged softer July traffic and higher rates, a notable caveat after a June surge that drove absorption sharply above the seasonal norm. Third-quarter orders should show whether that pace-driven strength was durable or a brief window. With community count at a record 330 and expansion underway across Texas, orders should benefit from more selling locations; flat or declining orders against that larger footprint would suggest absorption is weakening. Watch the adjustable-rate mortgage mix, which climbed to about 35% of buyers, as a gauge of how hard affordability is pressing, along with any update on weak spots such as Colorado and the Bay Area.
Expectations have cooled noticeably. Sentiment readings have fallen to only mildly bullish from a more confident stance before the last report, and the stock at $53.51 sits well below its 200-day moving average of $62.41 and just above the $53.30 low of its post-earnings range, a long way from the $73.58 high. That setup lowers the bar for a relief move but also signals that investors doubt the recovery can hold.
Ultimately, this report hinges on whether Century can show that improving construction costs and cycle times, now a record 112 days, can offset fading one-time margin help and choppier rate-sensitive demand. Reaffirming the 9,750 to 10,500 delivery range with stable underlying margins would validate last quarter's turn; another guidance retreat would confirm the market's darker read.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-15 | |
| Oct-14 | |
| Oct-08 | |
| Oct-06 | |
| Oct-01 | |
| Sep-30 | |
| Sep-29 | |
| Sep-28 | |
| Sep-22 | |
| Sep-15 | |
| Sep-11 | |
| Sep-10 |
