Century Communities Misses Badly And Cuts Guidance Again As Rate Spike Undercuts Record Community Growth
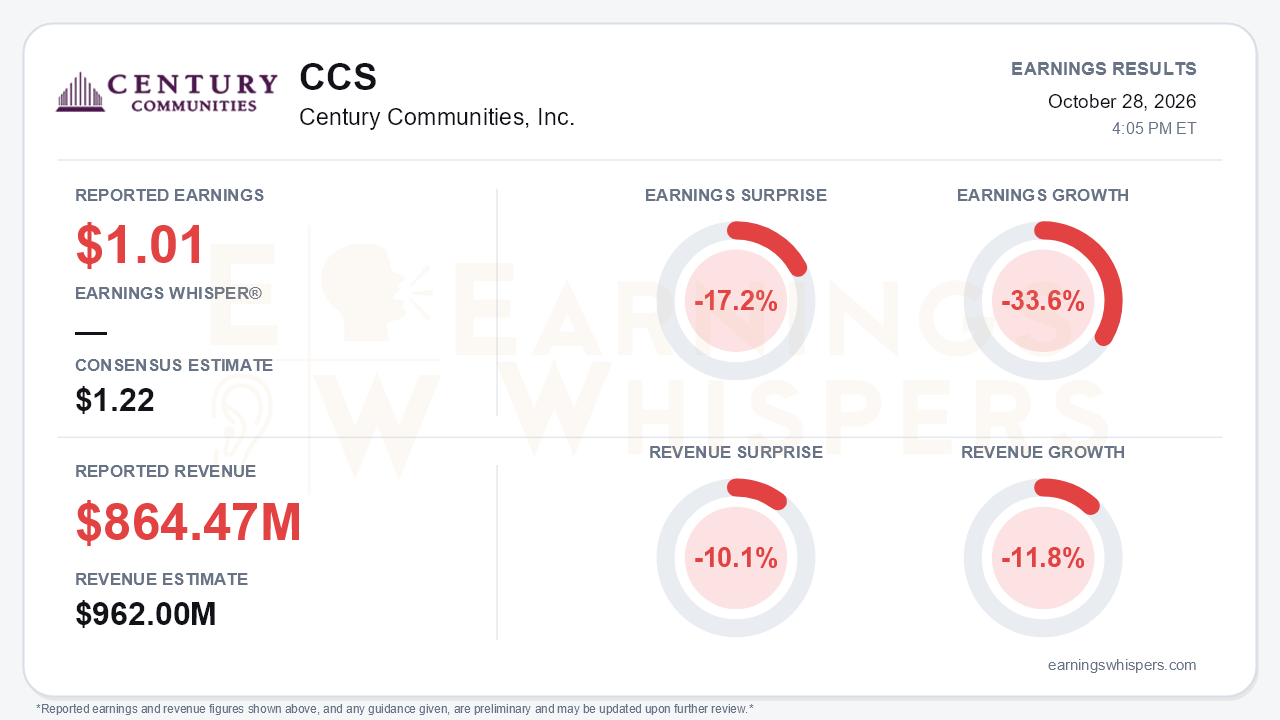
Century Communities delivered a clear miss in the third quarter, and the second guidance cut of the year matters more than the miss itself. Adjusted earnings of $1.01 per share fell 17.2% short of the $1.22 consensus. Revenue of $864.47 million missed the $962.0 million estimate by 10.1%. Adjusted EPS fell 33.6% year over year and revenue declined 11.8%. On a GAAP basis, the picture was worse: net income of $12.6 million, or $0.44 per diluted share, compared with $1.25 a year ago and $1.26 in the second quarter. The central tension is that Century is expanding its physical footprint aggressively just as demand, pricing and margins are moving the wrong way.
The quality of the quarter does not hold up well under scrutiny.
- **Deliveries missed the company's own target.** Deliveries of 2,442 homes fell below the 2,500-2,700 range management had issued only one quarter earlier.
- **Pricing fell sharply.** The average sales price dropped 10.2% year over year to $345,000, down from $358,000 in Q2 and $365,000 in Q1. Price declines hit every region.
- **Impairments drove much of the GAAP gap.** GAAP homebuilding gross margin fell to 15.0%, weighed down by $19.6 million of inventory impairments across six communities in the Bay Area, Houston and South Florida.
- **The underlying margin trend is also weaker.** Stripping out impairments, interest and purchase accounting still leaves an adjusted gross margin of 19.3%, down from 20.0% in Q2 and 20.1% a year ago.
- **The decline is steepening.** Nine-month adjusted EPS of $3.22 compares with $4.39 last year, and this quarter's year-over-year decline was steeper than the year-to-date pace. Earnings deterioration is accelerating, not stabilizing.
The call explained why management's tone shifted sharply from the second quarter. A roughly 75-basis-point jump in mortgage rates in September hurt traffic and conversions, and management said October looked similar.
- **Orders weakened.** Net orders fell to 2,284 from 2,615 in Q2 and were down 4.3% year over year.
- **Cancellations kept rising.** The cancellation rate climbed to 14.6%, up from 13.2% in Q2 and 12.2% in Q1.
- **Incentives are moving higher, not lower.** Incentives rose to about 1,300 basis points after Q2 had guided them flat. Management now expects another 200-250 basis points in the fourth quarter, reversing what had been a declining trend.
- **Production is being pulled back.** Starts were cut 12% sequentially.
- **The full-year outlook came down again.** Deliveries are now guided to 9,350-9,650 homes, including about 100 from HistoryMaker. That compares with 9,750-10,500 in July and 10,000-11,000 at the start of the year. Home sales revenue guidance fell to $3.3-3.4 billion from $3.5-3.8 billion.
- **Overhead guidance rose.** The SG&A ratio is now expected near 14.5%, versus roughly 13% in the original outlook.
- **Cost relief may be fading.** Direct costs fell 2% and finished lot costs fell 3% sequentially. However, management expects direct-cost savings to level off because of energy costs and tighter trade labor tied to immigration enforcement.
The credible part of the story is scale and geography.
- **Community growth is real.** Community count reached a record 343, up 7% year over year, with year-end guided to 360-370.
- **HistoryMaker adds meaningful scale in Dallas.** The October acquisition lifts Century's Dallas division from 12 to 41 communities, triples trailing deliveries from 211 to 669, adds move-up exposure and brings an ongoing land-development relationship. Management framed it as a template for further bolt-on deals as private builders struggle.
- **Texas and Century Complete held up.** Texas was the one region with real momentum: orders rose 21% and backlog units grew 34.9%. Century Complete, about 38% of deliveries, held up with above-average margins.
Bears have legitimate ammunition on the balance sheet. Net homebuilding debt to net capital rose to 34.9%, up from 31.9% in Q2 and 25.9% at year-end. Revolver borrowings climbed to $456 million from $51.5 million in December. Management now places buybacks behind holding leverage flat to down. The upsized $1.2 billion revolver and $864 million of liquidity provide flexibility. Even so, Century is adding communities and an acquisition while orders and pricing soften, which makes execution on the fourth-quarter guide critical. That guide implies selling and closing roughly 1,300 homes within a seasonally weak quarter, with incentives rising.
The market had already been discounting some of this. Shares closed at $57.69 ahead of the report, down 13.0% from the open after the July release. The stock sat 7.4% below its 200-day moving average and 21.6% below its August 19 inter-earnings high of $73.58. It was only 8.2% above the October 19 low of $53.30. Price-based trend readings were negative heading into the print. Even so, investor sentiment became modestly more positive, rising from 0.23 to 0.32. That suggests some investors were leaning toward stabilization that this report did not deliver.
The bottom line is that Century missed on earnings, revenue and its own delivery target, then cut guidance for a second time while flagging higher incentives, higher SG&A and fading cost relief. Record community count, a stronger Texas position and Century Complete's resilience give the company a credible platform for when rates ease. In the near term, however, the evidence points to falling prices, thinner margins and rising leverage, and the fourth-quarter guide leaves little margin for error.
Read our earnings preview for Century Communities, Inc.: https://www.earningswhispers.com/article/CCS/20912
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 3 hours | |
| 3 hours | |
| Oct-27 | |
| Oct-26 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-15 | |
| Oct-14 | |
| Oct-08 | |
| Oct-06 | |
| Oct-01 | |
| Sep-30 | |
| Sep-29 |
