Bausch Health's Third Quarter Tests Whether Its Guidance Raise Can Survive A Promised Slowdown
Bausch Health enters its third-quarter report in an unusual position: management has already told investors the numbers will look worse than last quarter, and the stock has rallied anyway. After a second quarter that produced record margins and the first full-scale guidance raise of this cycle, the question on October 28 is not whether growth slows. It is whether the slowdown looks like the orderly, well-flagged deceleration management described, or something messier.
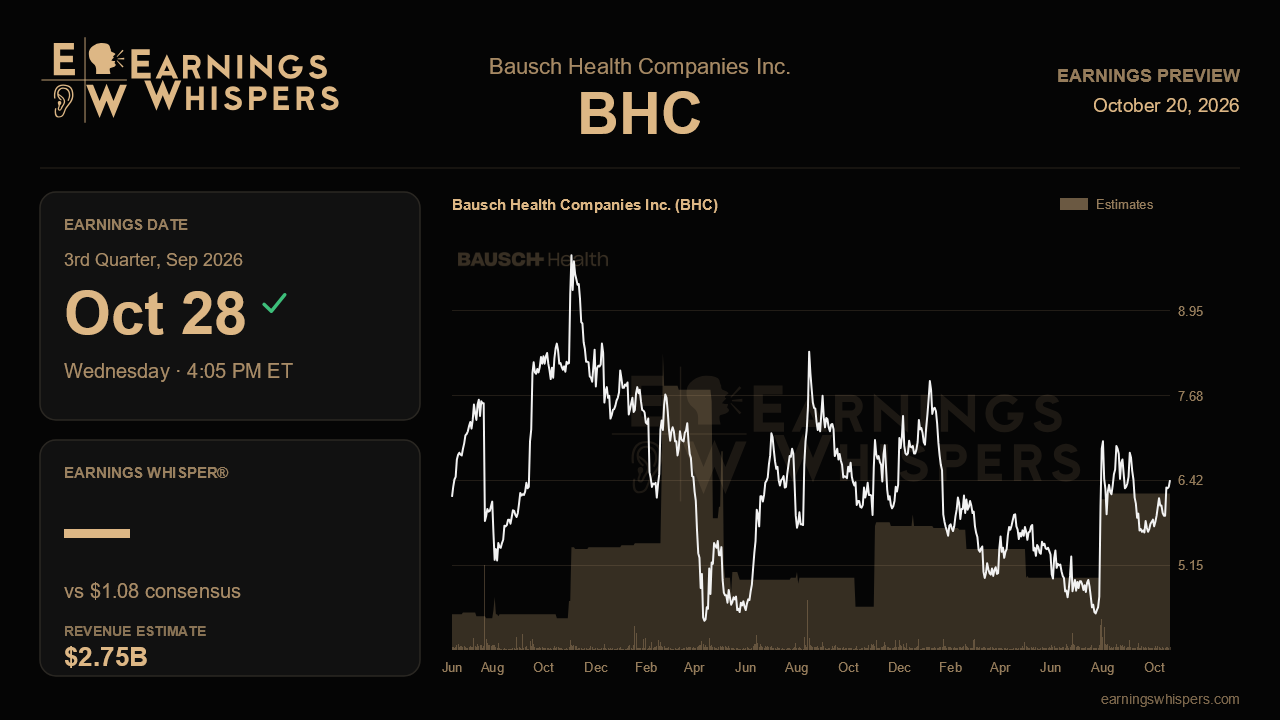
The Street is braced for contraction on the bottom line. Consensus calls for earnings of $1.08 per share, down about 7% from $1.16 a year ago and well below the $1.26 posted last quarter. Revenue is expected to reach roughly $2.75 billion, up a modest 2.6% year over year but a step down from the $2.85 billion reported in the second quarter. That pattern fits the script. Management named three second-half headwinds: a roughly $150 million gross-to-net swing tied to CMS rebate accruals, part of which comes from lapping a roughly $60 million Medicaid benefit booked in the year-ago third quarter; about $50 million of lost sales as generic competition hits Aplenzin and the neuroscience franchise; and around $75 million from continued erosion of Medicaid and 340B residual volume. Most of the larger $90 million accrual lands in the fourth quarter, so this report shows the early part of the drag rather than the full weight of it.
That sequencing makes the guidance math important. Management lifted full-year targets for the core business outside Bausch + Lomb to $5.35 billion to $5.50 billion in revenue, $3.1 billion to $3.25 billion in adjusted EBITDA and $1.40 billion to $1.475 billion in adjusted operating cash flow, after merely reaffirming in the first quarter. Because the first half did so much of the heavy lifting, a reaffirmation now would be perfectly respectable. Another nudge higher would suggest the headwinds are biting less than feared, while any trim would undercut the credibility the raise just bought.
The operating drivers to examine are the ones that carried the first half. Salix revenue grew 21% last quarter, with Xifaxan up 26% on net pricing and steady volume; holding growth in that range as the year-ago Medicaid benefit rolls off would validate the franchise's resilience ahead of its assumed 2028 exclusivity loss. Solta is the newer story. Management disclosed a segment-profit run rate near $330 million and framed it as roughly $1 billion of value, or $2 to $3 per share, that the market has not recognized. Sustaining something close to last quarter's 69% profit growth, with China still benefiting from the Shibo integration, would give that argument real weight. A sharp fade would make it look like a one-quarter pitch. Further progress on net debt, which fell to $13.7 billion, and any concrete business development step, now described as the top strategic priority, would round out the picture.
Expectations have clearly shifted. Sentiment has swung from modestly bearish heading into last quarter to modestly bullish now, and the shares have gained about 27% since the last report against roughly 4% for the S&P 500. At $6.32, the stock sits comfortably above its 200-day moving average of $5.73 but well below the $7.30 post-earnings high, so it has already given back part of the initial surge. That leaves some cushion, though a stock that has outrun the market by 23 points is less forgiving of an untidy quarter.
The central issue is whether the deceleration matches the blueprint. If the declines line up with the named headwinds while Salix and Solta keep delivering, the raised outlook stays intact and attention can turn to the still-unchanged $2.7 billion 2027 EBITDA framework. If the drag shows up faster or broader than promised, the market may decide the first half was the high-water mark.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-12 | |
| Oct-12 | |
| Oct-06 | |
| Sep-24 | |
| Sep-08 | |
| Sep-01 | |
| Aug-27 | |
| Aug-17 | |
| Aug-06 | |
| Jul-29 | |
| Jul-29 | |
| Jul-07 | |
| Jul-01 | |
| May-28 |
