AXIS Capital Faces A Softening-Market Test As Loss Picks Rise And Pricing Slides
AXIS Capital spent the past few years telling investors the specialty insurance market was changing but not softening. Last quarter that framing gave way. Management acknowledged broad-based pricing pressure, lifted its loss picks and leaned harder on reinsurance protection. The third-quarter report is the first chance to see whether that shift was a one-time recalibration or the opening chapter of a longer margin squeeze.
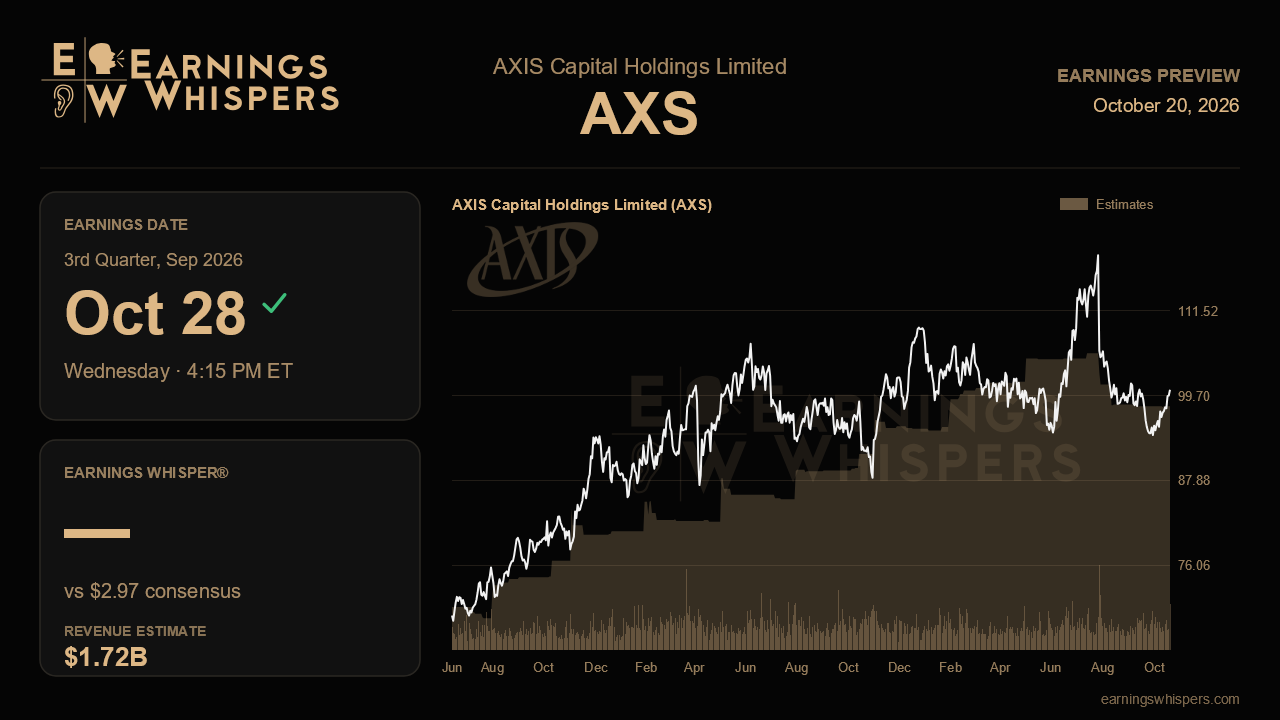
The Street is bracing for a modest step back. Consensus calls for earnings of $2.97 per share, down 8.6% from $3.25 a year ago, on revenue of about $1.72 billion, up 2.7%. That revenue figure is also slightly below the $1.75 billion booked last quarter, which fits a company deliberately shrinking parts of its book. Earnings would still edge up from the second quarter's $2.84, so the bar is not punishing. It is simply realistic about a year-over-year contraction in profitability. No formal guidance update has surfaced since the last call, which leaves management's prior commentary as the key yardstick.
The most important number may be the insurance underlying loss ratio. Management raised its expected year-over-year deterioration to roughly 1.7 points, up from the roughly one point it had signaled for two straight quarters. The driver was property pricing falling faster than planned, down 17% in the second quarter after a 13% drop in the first, with excess and surplus property off 22%. Casualty rates of 7% to 8% are also running behind loss trend. A third quarter that lands near the new 1.7-point marker would suggest the reset was adequate. Another upward revision, or property rate declines steepening again, would raise the uncomfortable question of whether AXIS is still chasing the cycle rather than managing it.
Top-line composition deserves scrutiny too. Insurance premiums grew 15% last quarter, but only about two points came from the core book, with the fee-driven ACS business contributing roughly eight points and expanded classes about five. ACS fees reached about $4 million in the second quarter against a full-year target near $17 million, which implies a meaningfully larger contribution over the back half. Evidence that ACS is ramping on schedule would validate it as a genuine offset to underwriting softness. Meanwhile, reinsurance premiums fell 25% and are tracking about 10% lower for the year as management trims casualty and professional lines, and employer stop-loss competition pushed that segment's loss ratio to 68.3%. Stabilization there matters more than growth.
The cost side has been the steadiest part of the story. The G&A ratio ran at 10.9%, below the 11% full-year target, and buybacks accelerated to $89 million with $263 million left on the authorization. Continued discipline on both fronts would help cushion lower margins and keep book value per share compounding after 15 straight quarters of growth. Catastrophe activity remains the wild card, given more frequent severe convective storm losses and fluid exposure tied to the Middle East conflict, though that same conflict has added premium-adequate marine war business.
Investor enthusiasm has cooled noticeably. Bullish sentiment has slipped to 8.6% from 26.5% ahead of the prior report, and the stock has gained just 1.8% since then, trailing the S&P 500 by nearly two points. At $99.71, shares sit below the 200-day moving average of $102.01 and in the lower half of their post-earnings range of $93.02 to $109.91, a ceiling well beneath the prior quarter's high near $120. That positioning suggests the market has already priced in some disappointment.
Ultimately, this report hinges on whether the higher loss picks hold. If AXIS shows the deterioration is contained while ACS and expense control carry their share of the load, the softening narrative becomes manageable. If loss assumptions creep up again, the defensive tone from last quarter will look like the beginning rather than the end of the adjustment.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-16 | |
| Oct-01 | |
| Sep-16 | |
| Sep-08 | |
| Aug-05 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 | |
| Jul-28 | |
| Jul-27 | |
| Jul-06 | |
| Jun-15 | |
| May-13 | |
| Apr-30 |
