AXIS Capital Beats On Investment Income And Growth, But Margins Erode As The Soft Market Deepens
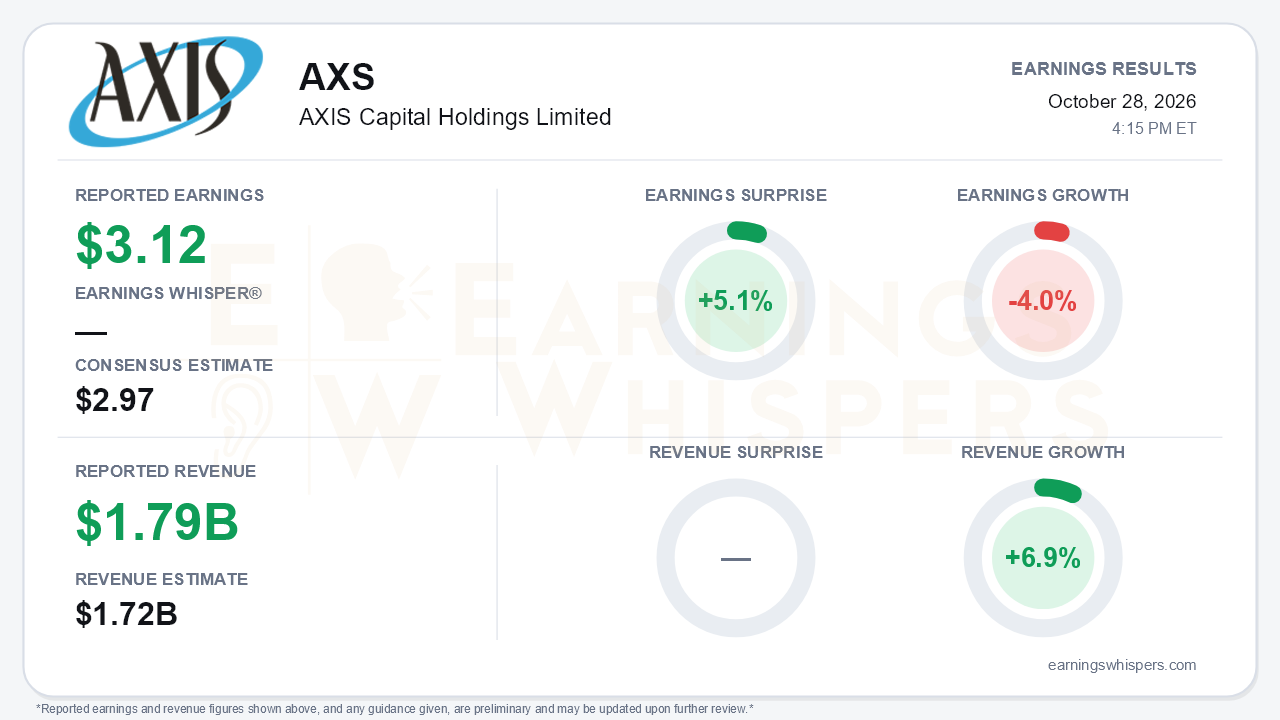
AXIS Capital (NYSE: AXS) cleared expectations in the third quarter, but the beat came from a business that is getting bigger rather than more profitable. Operating earnings of $3.12 per share topped the $2.97 consensus by 5.1%, and revenue of $1.79 billion beat the $1.72 billion estimate by 4.1% while growing 6.9% year over year. Earnings still fell 4.0% from a year ago, extending a contraction also visible in year-to-date operating EPS of $9.39 versus $9.67. Sequentially the picture improved: operating EPS rose from $2.84 in the second quarter and operating ROACE climbed to 15.7% from 14%. That is the central tension. Premium growth, investment income and buybacks are carrying the per-share numbers while underwriting margins keep slipping.
The quality of the beat deserves scrutiny. Underwriting income fell 29% to $134 million, and the combined ratio rose to 94.0% from 89.4% a year ago, up from 93.1% in Q2 and 89.8% in Q1. Catastrophe and weather losses explain only part of the slide. They totaled $75 million, including $44 million tied to the Middle East conflict and the Russia-Ukraine war. The more telling measure is the ex-cat current accident year combined ratio, which rose 2.6 points to 90.3%. In Insurance, the attritional loss ratio climbed 1.9 points to 54.2%, which the company attributed to accelerating property softening and more competitive casualty conditions. The acquisition cost ratio jumped 2.8 points to 22.5% on AXIS Capacity Solutions business and higher-commission marine war premium. The offsets were real. The G&A ratio improved to 10.8%, and net investment income rose 14% to $211 million on a 4.9% book yield. GAAP results were weaker still: diluted EPS fell to $2.75 from $3.74 as $47 million of net investment losses hit the income statement.
The top line remained strong. Gross premiums written rose 11% to $2.4 billion, with Insurance up 13%. Per the call, ACS contributed roughly 7 points of that growth and expanded classes about 5 points, and Retail North America grew 16%. Reinsurance gross premiums returned to 4% growth after a 25% decline in Q2, though net premiums written still fell 5% and the full-year segment outlook remains down low double digits. Marine war business tied to the Iran conflict added roughly $100 million of earned premium. That is a helpful but episodic tailwind, and management called Q4 war volumes uncertain.
The forward signals tilted cautious. Property rates fell 10%, and 15% in E&S. Management said pricing in some segments is "no longer rational." Casualty increases of 8-10% are only keeping pace with loss trend. Management signaled continued attritional pressure, a figure that has drifted up from 53.3% in Q1 to 54.0% in Q2 and now 54.2%. It also lifted its Q4 acquisition ratio proxy to about 22% from roughly 21%. ACS volume from the RAC Re arrangement is likely to shrink in its second year. The CEO declined to commit to double-digit insurance growth in 2027. On the positive side, management guided Q4 net investment income to about $200 million. Buybacks also accelerated to $109 million from $89 million in Q2 and $60 million in Q1, and management described the stock as highly attractive. Operational catalysts include a next-generation underwriting platform now cutting quote cycle times by up to 70%.
Book value tells a split story. Diluted book value per share fell 2.0% sequentially to $79.06 because rising sovereign yields and wider credit spreads produced a $361 million pre-tax unrealized loss on fixed maturities. Excluding AOCI, book value rose 2.7% in the quarter and 14.4% over twelve months to $84.33. The 5.8% market yield also points to continued reinvestment upside for income.
Investor sentiment cooled sharply heading into the report, falling from 0.265 to 0.058. It remains marginally positive, but conviction has been largely drained. Shares have gained 3.7% since the open following the July report, to $101.61. That leaves them essentially at the 200-day moving average of $101.93, a stock in equilibrium rather than one with a clear trend. The Earnings Whispers trend readings are mixed, with price trend negative while AVWAP remains positive.
The bottom line is that AXIS delivered a clean beat and credible sequential improvement, but the earnings mix is shifting toward investment income, buybacks and episodic war premium. Core underwriting margins are compressing as the cycle turns. Bulls can point to 14% ex-AOCI book value growth and aggressive capital return. Bears have legitimate ammunition in a rising attritional loss ratio, higher acquisition costs and management's reluctance to promise growth into 2027. With sentiment deflated and shares parked at their long-term average, the next leg likely depends on whether margin erosion stabilizes before the soft market fully arrives.
Read our earnings preview for AXIS Capital Holdings Limited: https://www.earningswhispers.com/article/AXS/20906
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-28 | |
| Oct-20 | |
| Oct-16 | |
| Oct-01 | |
| Sep-16 | |
| Sep-08 | |
| Aug-05 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 | |
| Jul-28 | |
| Jul-27 | |
| Jul-06 | |
| Jun-15 |
