Antero's Cost-Cut Blueprint Meets Sub-$2 Gas As Third-Quarter Test Arrives
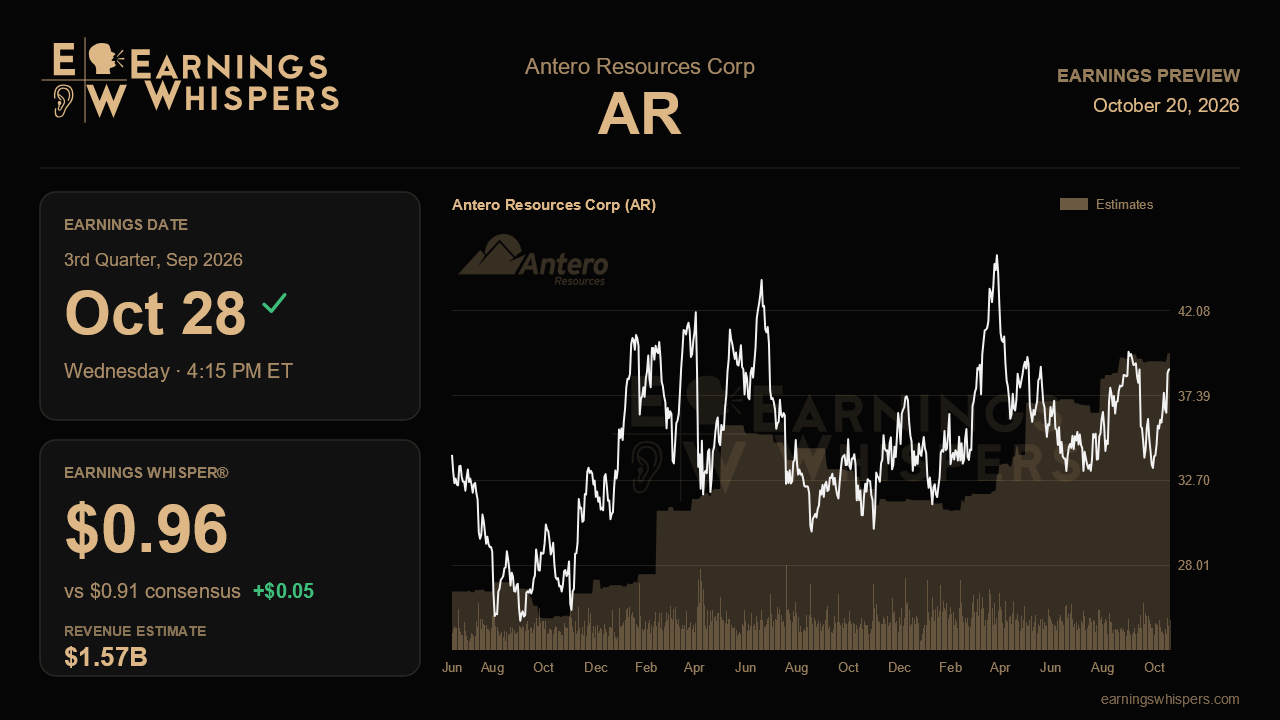
Last quarter Antero Resources stopped talking about future initiatives and started putting numbers on them. Management laid out a $300 million annual margin improvement program through 2028 and a plan to cut cash costs by more than 25% to $2.00 per Mcfe, and it paired that with record production and the best natural gas liquids prices since 2022. The third-quarter report, due after the close on October 28, is the first chance to see whether that blueprint shows up in the numbers while spot gas was trading below $2 in September and the company was curtailing volumes.
The Street is not bracing for weakness. Consensus calls for earnings of $0.91 a share on revenue of about $1.57 billion, which would be roughly a ninefold jump from the $0.10 earned a year ago and a 29% increase in sales. The whisper number sits at $0.96, a modest but real step above consensus, suggesting some traders expect another beat. The sequential comparison matters more than the eye-popping annual growth rate. Revenue is expected to be essentially flat against the second quarter's $1.56 billion, yet earnings are projected to climb from $0.72. That gap implies analysts expect margin gains, not price or volume, to do the heavy lifting, which puts the cost story directly on trial.
There are concrete reasons to think it could. The dissolved override royalty arrangement was supposed to add about $60 million of annualized cash flow beginning this quarter, and the $315 million of West Virginia bolt-on acquisitions that closed in July should contribute roughly 125 MMcfe per day of net production at what management described as about four times EBITDAX. Evidence that both are flowing through, alongside lower per-unit cash costs, would validate the claim that Antero's margin expansion is structural rather than a byproduct of strong liquids pricing. Investors should also look for progress toward the 4.5 Bcfe per day exit rate targeted for 2026, keeping in mind that curtailments on lean pads, newly possible after reduced minimum volume commitments, may temporarily muddy the production picture.
The risks are equally specific. Management guided realizations down about 35 cents as more gas sells in-basin, framing it as a deliberate trade against a 70-cent cost reduction. If the realization hit arrives before the cost savings, the net-margin argument weakens. NGL pricing is another swing factor, since the second quarter's C3+ print of $44.26 per barrel did a lot of work and may not repeat. The biggest open question is capital. Fourth-quarter growth completions, which would lift spending to about $1.2 billion versus a $1.0 billion maintenance pace, were explicitly tied to $3-plus gas. With prices soft, any update on whether that program proceeds will say a lot about how confident management is in the 2027 trajectory.
The market has already leaned in. Shares have gained 11.7% since the last report, beating the S&P 500 by 7.6 points, and at $38.83 the stock sits comfortably above its 200-day average and within about 3.5% of its post-earnings high of $40.21, which also tops the prior quarter's peak. Sentiment, by contrast, has cooled slightly to marginally bullish from somewhat more enthusiastic readings a quarter ago, a sign that the rally has come with fewer cheerleaders. That combination leaves limited room for a muddy print.
Ultimately, this report hinges on whether Antero can show its margin engine running independently of the gas tape. Lower unit costs, visible contributions from the royalty unwind and acquisitions, and a clear stance on growth capital would keep the demand-pull narrative intact even without a signed long-term in-basin contract, which remains the missing piece after management walked away from a headline power deal. A quarter that leans on liquids prices to hit the number would leave the bigger thesis looking less proven than the stock price suggests.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-14 | |
| Oct-06 | |
| Sep-25 | |
| Sep-25 | |
| Aug-12 | |
| Aug-04 | |
| Jul-30 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-15 | |
| Apr-30 | |
| Apr-30 |
