Antero Resources Misses On EPS As Weak Appalachian Gas Prices Offset Record Volumes And A Margin Plan Running Ahead Of Schedule
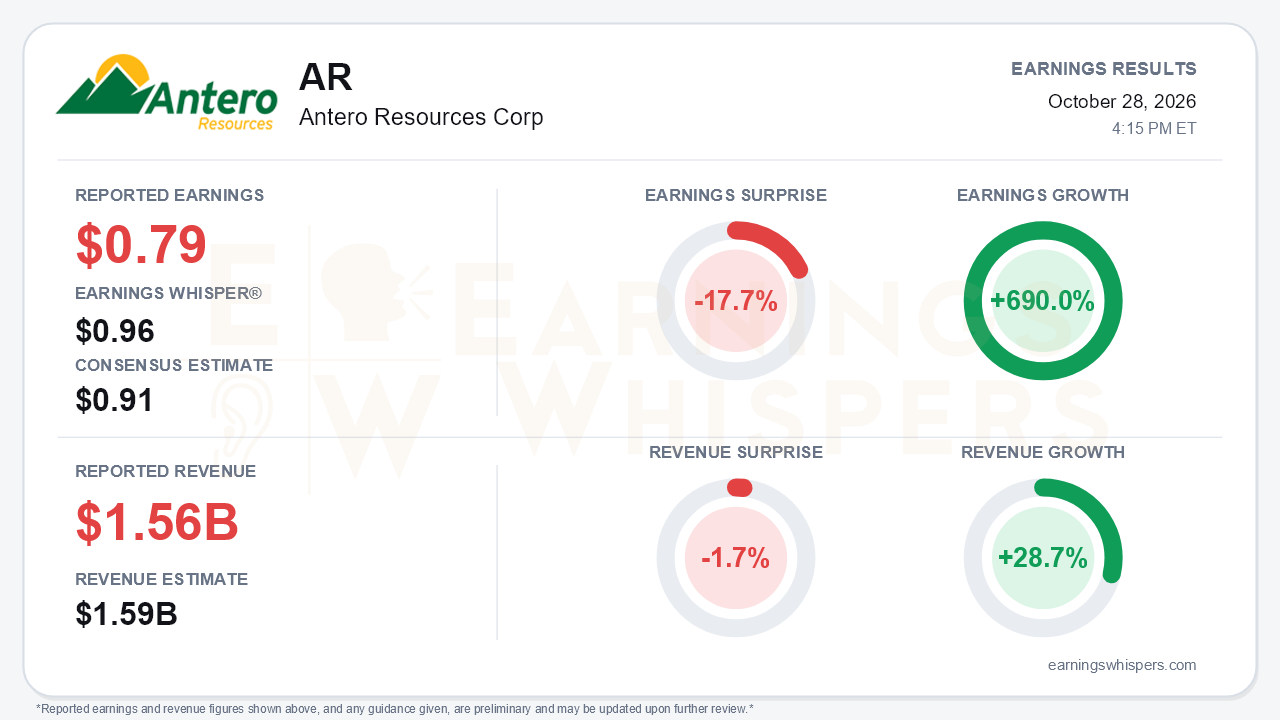
Antero Resources (NYSE: AR) missed on its third-quarter earnings, though the underlying operating story was stronger than the headline. The company reported earnings of $0.79 per share, short of the $0.91 consensus by 17.7% and well below the $0.96 Earnings Whisper number. Revenue of $1.563 billion missed the $1.59 billion consensus by 1.7%. Year over year, the comparison looks very different: earnings grew 690.0% and revenue rose 28.7%, driven by a record 4.2 Bcfe/d of net production, up 23%. The central tension is that Antero is executing its cost and margin agenda faster than promised, while the one variable it cannot control, regional natural gas pricing, turned sharply against it and set a high bar for a stock that had already rallied into the report.
The quality of the quarter deserves careful reading because the measures diverge. GAAP net income was $367 million, or $1.19 per diluted share. That figure was inflated by $53 million of unrealized derivative gains and $111 million of equity earnings from its unconsolidated affiliate. Adjusted net income was a more modest $256 million. The cash measures were strong:
- Adjusted EBITDAX nearly doubled to $634 million.
- Adjusted free cash flow jumped 137% to $215 million.
- Cash production expense fell to $2.05 per Mcfe from $2.44, below the low end of guidance. The biggest contributor was a 38% drop in per-unit transportation costs.
The weak spot was price. Antero realized just $2.63 per Mcf for gas before hedges, a $0.32 discount to index and down 16% from a year ago. Only $0.52 of hedge gains lifted the after-hedge price to $3.15. The earnings miss is therefore largely a commodity-realization story rather than an execution failure.
The call moved from presenting a margin plan to showing it was ahead of schedule.
- **Cost reduction:** Cash costs fell 16% year over year, an acceleration from the 11% decline in the second quarter. Management said the unhedged EBITDAX margin rose 27% even as NYMEX gas fell 4%.
- **Margin enhancement:** Of the $300 million target, $140 million is now locked in by mid-2027. That includes $60 million from the overriding royalty reversion, $20 million from 400 MMcf/d of firm transportation already optimized, and $50 million targeted from a formal process covering roughly 1 Bcf/d of transport. Expiration of the volumetric production payment in 2027 adds about $30 million and 35 MMcf/d of volume.
- **Longer-term potential:** Management now frames the total opportunity as potentially doubling to about $600 million by early next decade.
- **HG integration:** Synergies from the HG acquisition were raised to more than $100 million from $80 million.
- **Liquids:** NGL pricing has surged, with C3+ realizations near $60 per barrel versus $44.26 in the second quarter. Management expects fourth-quarter free cash flow to roughly double the third quarter's and framed 2027 EBITDA above $3 billion at strip.
Bears have legitimate ammunition on the gas side. Regional prices hit record lows in September and October because of downstream outages, falling to roughly $0.60 on some weekends. Realized gas swung to a discount after management had discussed a $0.10-$0.20 premium earlier in the year, and the hoped-for LNG-driven premiums have not materialized. Fourth-quarter guidance has several soft points:
- Production is guided to about 4.3 Bcfe/d, including 15-20 Bcfe of price-driven curtailments versus about 10 Bcfe in the third quarter. That is below the roughly 4.5 Bcfe/d exit rate cited on the prior call.
- Cash production expense is guided up to $2.10-$2.20 per Mcfe on fuel costs.
- The 2027 outlook calls for high-single-digit growth, but the risked base implies limited organic growth.
- Part of the NGL windfall is tied to Middle East conflict and elevated shipping rates, which may not last.
The balance sheet has also changed. Net debt rose to $2.78 billion from $1.31 billion a year ago after the HG deal, although the CEO says leverage remains around 1.0x.
The market setup is more demanding than the miss alone suggests. Shares have climbed 21.1% since the open after the July report, to $42.11, and sit 14.7% above the 200-day moving average of $36.70. Antero repurchased 1.6 million shares in the quarter at an average of $34.15, well below current levels. Price and AVWAP trend readings remain positive. Investor sentiment stayed mildly positive but slipped slightly, from 0.0887 to 0.0753, a change too small to signal any real shift in expectations. In short, investors entered the print constructive, and a whisper number above consensus shows how much good news was already expected.
The bottom line is that Antero's third quarter missed on headline earnings mainly because Appalachian gas prices collapsed, not because the business plan faltered. Costs, margins, synergies and NGL leverage all improved, and management outlined a credible path to substantially higher free cash flow. However, curtailed fourth-quarter volumes, a reset in gas differentials, and NGL upside partly dependent on geopolitics mean the near-term cash story relies more on commodity prices than the self-help narrative suggests, and the stock's run-up leaves less room for those risks.
Read our earnings preview for Antero Resources Corp: https://www.earningswhispers.com/article/AR/20902
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-14 | |
| Oct-06 | |
| Sep-25 | |
| Sep-25 | |
| Aug-12 | |
| Aug-04 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 |
