Amrize Faces A Margin Test As Strong Volumes Collide With Oil-Driven Cost Inflation
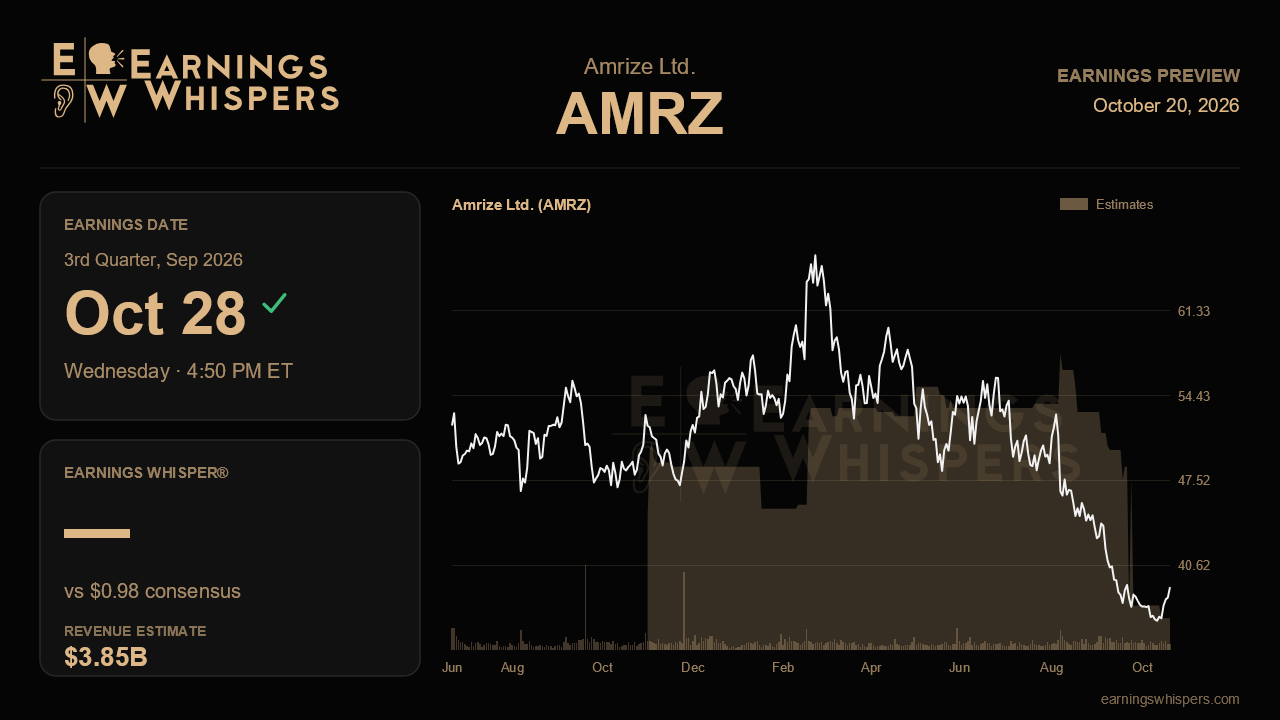
Amrize heads into its third-quarter report with a strange split in its story. Demand has rarely looked better, yet the company trimmed its profit outlook three months ago, and the stock has since lost a fifth of its value. The October 28 release, due after the close, is less about whether customers are buying cement, aggregates and roofing. They clearly are. The question is whether Amrize can keep enough of each sale to stop earnings from going backward.
Wall Street expects earnings of $0.98 a share on revenue of about $3.85 billion. That implies sales growth of roughly 4.8% while per-share profit falls about 7.6% from last year's $1.06. The gap between those two numbers is the whole setup. Management raised its full-year revenue range to $12.5 billion to $12.7 billion, yet the Street's annual estimate of about $12.45 billion sits below the bottom of that range. That suggests analysts are not fully buying the top-line raise, or are assuming a softer fourth quarter. A third-quarter revenue figure comfortably above consensus would make the company's guidance look credible and could pull estimates higher.
Profit is the harder test. Last quarter Amrize cut its adjusted EBITDA outlook to $3.1 billion to $3.2 billion, down from earlier targets of 8% to 11% growth. It blamed an oil-linked cost headwind now estimated at $140 million to $170 million for the year, driven by diesel, raw materials and a sharp jump in U.S. trucking rates. Management also said the gap between price increases and cost inflation would stay negative through the third quarter and only turn positive in the fourth. So this report should show pressure. What matters is whether that pressure is shrinking. Narrower unfavorable price/cost, signs that surcharges are sticking, and steady progress on the Aspire savings program would support the claim that margins bottom here. Aspire is targeting $80 million this year, with $29 million delivered in the second quarter. Any sign that the expected fourth-quarter turn is slipping again would be a real problem. The timeline has already moved once, with building envelope price/cost neutrality pushed beyond its earlier third-quarter target.
Pricing deserves close attention. Cement pricing slipped 0.2% from a year earlier last quarter, and full-year guidance was cut to flat to up low single digits. Volumes are also slowing against tougher comparisons. Cement growth fell to 5% from nearly 14%, and aggregates to 6.5% from 14.1%. If pricing stays flat while volume growth cools further, the revenue beat that bulls are counting on gets harder to deliver. On the positive side, the building envelope business swung back to growth, residential roofing posted a record quarter, and data center, energy and mega-project demand all remain intact. The Rapid Ready Mix deal, which closed July 31, should add its first contribution this quarter, and PB Materials has been running ahead of plan. The newly expanded Missouri cement plant adds volume that should help offset weak pricing.
The market has already priced in plenty of skepticism. Shares have fallen about 20% since the last report while the S&P 500 was roughly flat. At about $38, the stock trades well below its 200-day moving average near $51.29 and close to the $35.79 low of its post-earnings range. That entire range sits below where the stock traded the previous quarter. Sentiment remains bearish but far less so than before the last report, which hints that some sellers may be exhausted. The $1 billion buyback also gives the company a way to support per-share results.
In the end, this quarter comes down to one question: is the cost squeeze peaking on schedule? If Amrize can show a narrowing price/cost gap and reaffirm both its revenue and EBITDA ranges, the strong-demand story stays intact and the depressed share price looks overdone. If cost inflation keeps outrunning pricing, another cut to the profit outlook would confirm the market's fears.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-14 | |
| Oct-01 | |
| Sep-11 | |
| Sep-09 | |
| Sep-02 | |
| Sep-02 | |
| Aug-24 | |
| Aug-10 | |
| Aug-07 | |
| Aug-07 | |
| Aug-07 | |
| Aug-06 | |
| Jul-20 | |
| Jul-16 |
