Amrize Edges Past EPS Consensus, But Rolling Volumes And A Second Guidance Cut Overshadow Its Pricing Inflection
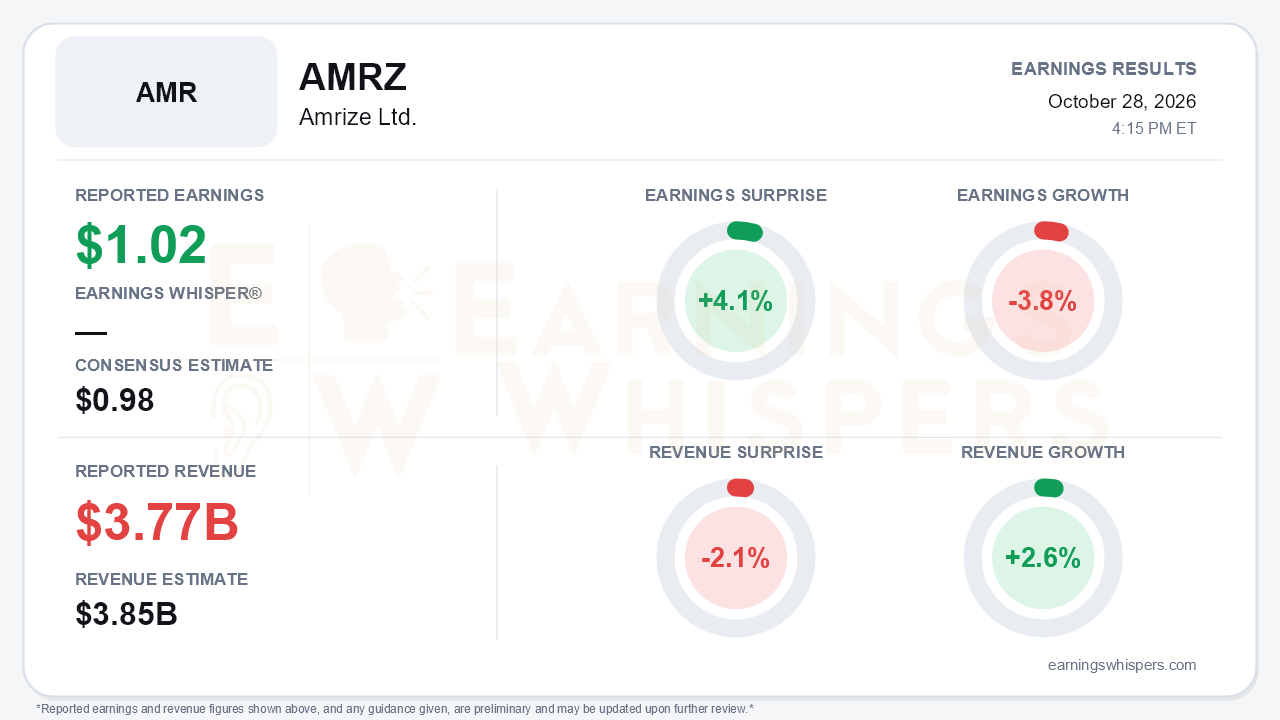
Amrize (NYSE: AMRZ) reported third-quarter earnings of $1.02 per share, beating the $0.98 consensus by 4.1%. Revenue of $3.771 billion missed the $3.85 billion consensus by 2.1%. On Earnings Whispers' normalized basis, earnings fell 3.8% year over year while revenue grew 2.6%. The company's own presentation is more flattering: GAAP diluted EPS of $1.02 versus $0.98, and adjusted EPS flat at $1.05. The prior-period figures were also revised for immaterial misstatements, so investors should be careful about which comparison they are using. Either way, the bottom-line beat is not the story. Pricing finally turned decisively in Amrize's favor, but volumes rolled over and cost inflation forced a second consecutive cut to full-year guidance. That is the central tension.
The quality of the beat deserves scrutiny. Gross profit slipped to $1,081 million from $1,092 million. Adjusted EBITDA rose just 0.2% to $1,076 million, and the adjusted EBITDA margin contracted 60 basis points to 28.5%. Per-share results got help from several sources:
- diluted shares fell to 545.5 million from 553.9 million;
- tax expense was lower;
- unallocated corporate costs dropped to $44 million from $52 million.
The revenue bridge is more revealing still. Price contributed $78 million, acquisitions $77 million and surcharges $23 million, yet organic growth totaled only $10 million. Volume losses, roughly a $69 million headwind per the call, absorbed nearly all of the pricing gains. Reported revenue growth decelerated to 2.2% from 8.6% in the second quarter.
Beneath that, the two segments moved in opposite directions.
Building Materials delivered the quarter's genuine positive. Constant-currency cement pricing rose 1.8%, versus -0.2% in Q2 and -2.4% in Q1. Aggregates pricing accelerated to 6.9% from 4% and roughly 1%. Segment EBITDA grew 2.7% to $938 million, the margin widened 30 basis points to 33.0%, and management expects price-cost to stay positive in Q4. Volumes, however, reversed sharply: cement fell 4.2% after rising 5% in Q2 and 13.9% in Q1, and aggregates slipped 0.2% after gaining 6.5%. Management blamed weather in the Northeast, South and Central regions. It also cited elevated interest rates as a risk to fourth-quarter volumes, a notable reversal from the falling-rate assumption that underpinned its original 2026 outlook.
Building Envelope is where the damage is concentrated. Revenue grew 3.6% and commercial roofing stayed strong on data center and industrial work. But segment EBITDA fell 14.6% to $182 million, a steeper decline than Q2's 5.2%, and the margin compressed to 19.6% from 23.7% as freight and petrochemical raw-material costs outran pricing. Management pushed the expected return to positive price-cost from Q4 2026 into 2027. Residential roofing went from a record Q2 and high-single-digit growth expectations to soft demand, with shingle destocking expected in Q4. Per the call analysis, management was noticeably less specific when pressed on 2027 cost recovery.
The guidance history tells the story plainly:
- Revenue guidance now stands at $12.2-$12.4 billion, after being raised to $12.5-$12.7 billion just one quarter ago.
- Adjusted EBITDA guidance falls to $2.95-$3.05 billion from $3.1-$3.2 billion. That is roughly flat against 2025, versus an original target of 8-11% growth.
The balance sheet has also absorbed considerable strain:
- Year-to-date free cash flow was a $551 million outflow, against $186 million a year ago.
- Cash fell to $299 million from $1.92 billion at year-end, while $904 million of short-term borrowings appeared.
- Net leverage rose to 1.8x from 1.1x at year-end 2025, and liquidity declined to $3.4 billion.
- Management now expects free cash flow conversion to fall below its roughly 50% target.
Completing the $1 billion buyback on October 28 rewards shareholders, but bears have legitimate ammunition on capital allocation. On the positive side, the PB Materials and Rapid Redi-Mix acquisitions are beating plan and expected to be EPS accretive. ASPIRE savings have reached $73 million toward an $80 million target, and infrastructure funding in the U.S. and Canada provides longer-term support. The company also has a new CFO, Sam Poletti.
The market had already priced in considerable disappointment. Shares at $40.03 are down 15.7% from the $47.50 open after the August report and sit 21.1% below the 200-day moving average of $50.73. The AVWAP trend reading remains negative. Investor sentiment, however, improved substantially, from -0.46 at the prior report to -0.03, essentially neutral. Pessimism had eased by report time, which leaves the stock exposed to a guidance cut that undercuts the recovery narrative.
The bottom line is that Amrize proved it can raise prices in cement and aggregates, but that achievement is being overwhelmed by falling volumes, a Building Envelope cost squeeze now extending into 2027, and a balance sheet stretched by buybacks and acquisitions. A modest EPS beat and a pricing inflection do not offset a full-year EBITDA outlook that has shifted from solid growth to flat.
Read our earnings preview for Amrize Ltd.: https://www.earningswhispers.com/article/AMRZ/20900
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-20 | |
| Oct-14 | |
| Oct-01 | |
| Sep-11 | |
| Sep-09 | |
| Sep-02 | |
| Sep-02 | |
| Aug-24 | |
| Aug-10 | |
| Aug-07 | |
| Aug-07 |
