Align's Q3 Tests Whether Aligner Momentum Can Outrun Scanner Cuts And A Sliding Stock
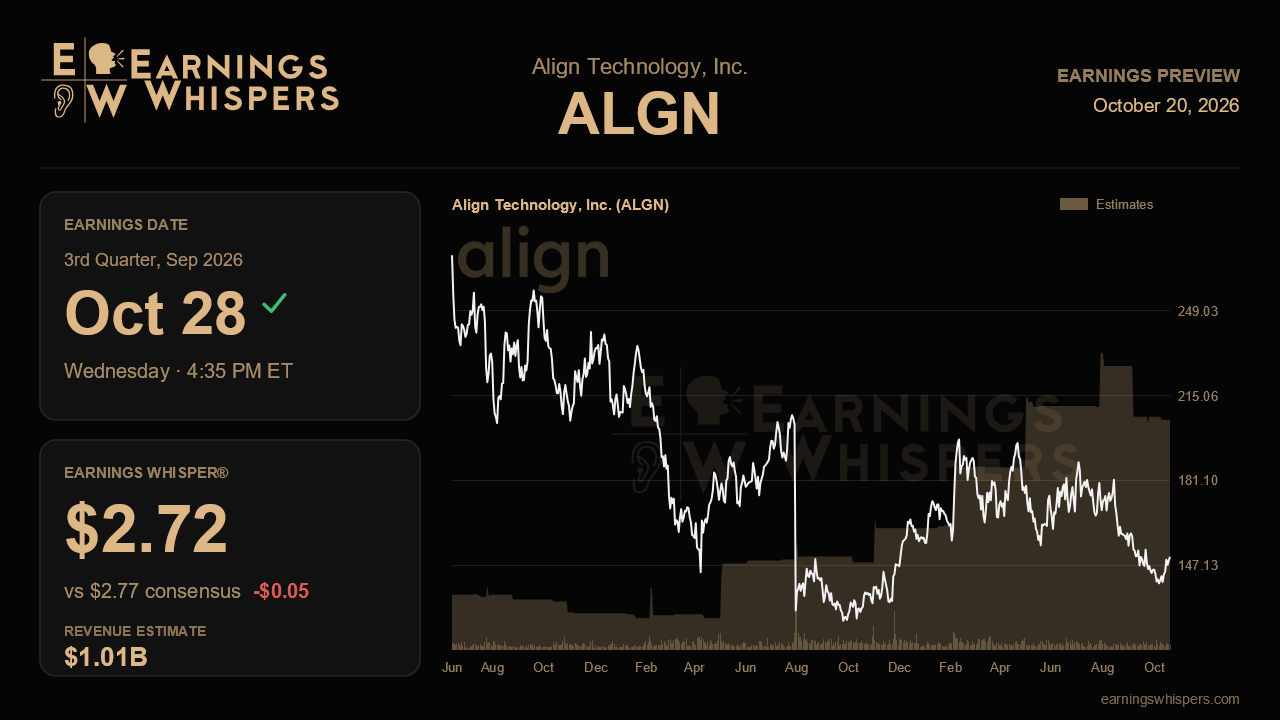
Align Technology heads into its third-quarter report with an odd disconnect. Management sounded more confident on its last call than it had in a year, citing record first-half aligner volumes, firmer pricing, a larger buyback and an early pledge of further margin gains in 2027. The stock has gone the other way, falling 17.6% since that report while the S&P 500 rose 4.1%. When the numbers arrive after the close on October 28, the question is whether the operating story still holds or whether the market has spotted something the call glossed over.
The bar itself is modest. Analysts expect non-GAAP earnings of $2.77 per share on revenue of about $1.01 billion, which would be growth of roughly 1.4% from the year-ago quarter. That is essentially flat, and it sits right in the middle of management's $1.00 billion to $1.02 billion third-quarter range. The earnings whisper of $2.72 is a touch below consensus. The gap is small, but it suggests the more skeptical crowd sees little room for upside surprise on the bottom line. The full-year picture is less forgiving. Management reaffirmed 2026 revenue of $4.156 billion to $4.196 billion, and the Street's $4.19 billion estimate sits near the top of that range. Analysts are leaning on the upbeat parts of the last call, so a merely midpoint outcome could disappoint.
The core of the bull case is clear aligner volume. Last quarter, management said first-half volumes were running about 7% above the prior year, ahead of the mid-single-digit growth it had guided all year. Growth came from double-digit gains in Asia-Pacific and EMEA and from strength in dental service organizations, which offset a soft North American retail market. A third quarter that keeps volume growth near that pace would support the case. Any slowdown toward the low single digits would raise the question of whether the first half pulled demand forward. Two items deserve close attention. The first is the United Kingdom, where Align is now passing a re-imposed 20% VAT on to providers and has said it is watching for volume effects. The second is North American retail, which management calls a top priority but has not yet turned around.
Pricing is the second test. Average selling prices have risen steadily to about $1,260, and management shifted from expecting a 1% to 2% decline this year to expecting prices to hold. If that holds in the third quarter, helped by product mix and list-price increases, it supports the gross-margin-led path to roughly 100 basis points of operating margin improvement this year. A dip in pricing would weaken both that target and the newer 2027 framing. Systems and services is the weak spot. Management already cut that business to a roughly 7% decline for the year as customers shift toward leased, rented and certified pre-owned scanners. Investors should look for evidence that the cut was enough, and that the shift is changing how scanner revenue is recognized rather than reflecting falling demand for iTero.
Sentiment has improved slightly, moving from 21.6% bearish before the last report to 17.2% bearish now. Even so, the stock trades at $149, well below its 200-day moving average of $169.41 and only about 8% above its post-earnings low of $138.05. It has fallen hard from a high near $188. That leaves a stock priced for doubt, even as management talks about a bigger buyback and an outside review of its strategy and operating model.
The report comes down to whether aligner volume and pricing remain strong enough to absorb the scanner shortfall. If they do, and management keeps the full-year range and its 2027 margin goal intact, last quarter's improving tone gains credibility the stock has not yet credited. If volume cools while the Street sits near the high end of guidance, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-16 | |
| Oct-05 | |
| Oct-05 | |
| Oct-01 | |
| Sep-28 | |
| Sep-22 | |
| Sep-08 | |
| Aug-31 | |
| Aug-17 | |
| Aug-11 | |
| Jul-30 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 |
