Align Technology Beats On Cost Control, But Slowing Growth, A Guidance Trim And A CEO Exit Dominate
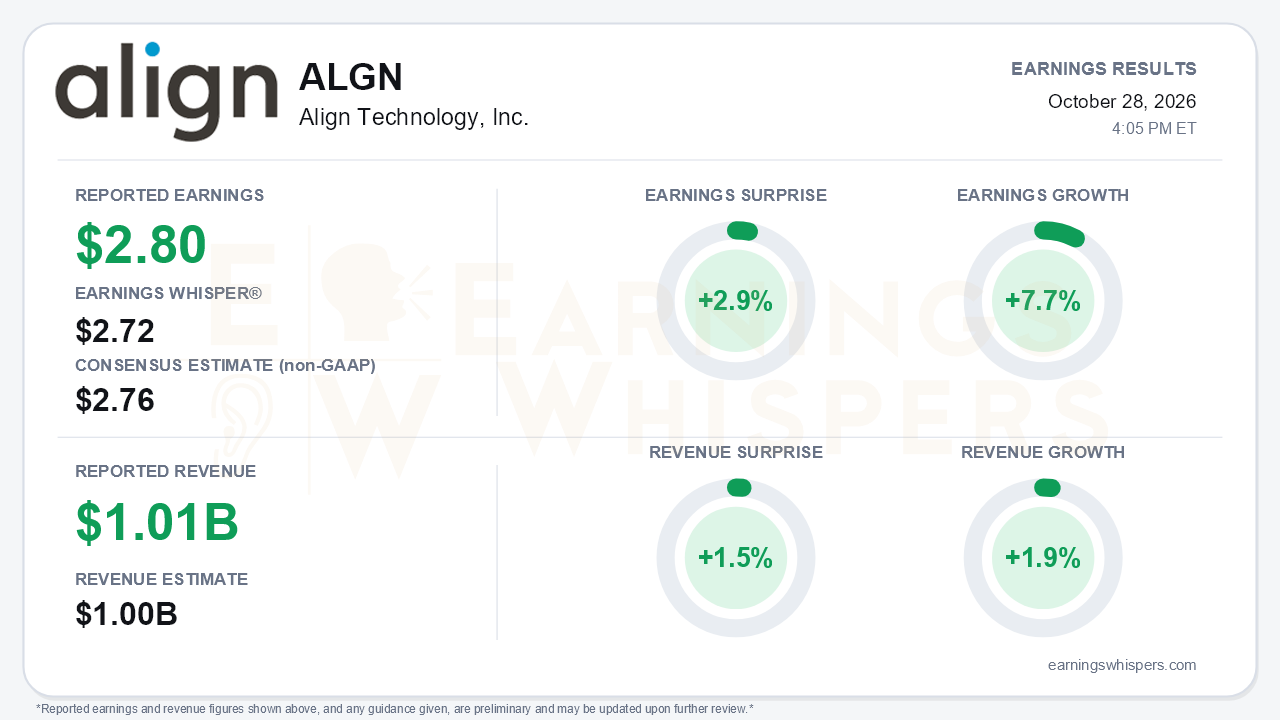
Align Technology delivered a modest headline beat for the third quarter. Non-GAAP earnings of $2.80 per share topped the $2.76 consensus by 2.9% and cleared the $2.72 Earnings Whisper number. Revenue of $1.015 billion beat the $1.00 billion consensus by 1.5%. Earnings grew 7.7% year over year, while revenue rose just 1.9%. That gap is the central tension. Align is growing earnings through cost discipline and buybacks, while its top line is decelerating. Revenue growth slowed from 6.2% in the first quarter and 5.3% in the fourth quarter of fiscal 2025. Management then trimmed full-year revenue guidance to $4.11 billion to $4.13 billion, roughly 3% growth and the low end of the original range.
The quality of the beat deserves scrutiny. On the operating line, it was genuine. Non-GAAP operating margin of 24.4% exceeded the outlook, and non-GAAP operating expenses of $466.3 million were essentially flat year over year despite higher revenue. The gross margin story was weaker. Non-GAAP gross margin of 70.4% missed management's roughly 71% target and was flat year over year. Management blamed fuel-related freight costs, lower Clear Aligner pricing and mix, and the figure was down from 71.8% in the first quarter. GAAP EPS jumped to $1.90 from $0.78, but that comparison is flattered. The prior-year quarter absorbed impairment charges, accelerated depreciation, an inventory write-down and a 40.1% GAAP tax rate. The GAAP improvement says more about lapping charges than about a step-change in the business. Share count also fell, helped by Q3 repurchases of about 627,000 shares at an average of $164.73.
Beneath the surface, volume held up better than pricing. Clear Aligner shipments reached a record 690.6 thousand cases, up 6.6%, with record doctor submitters of roughly 91,000 and utilization up 3.4%. There were encouraging signs in North America:
- Orthodontist shipments grew year over year for the first time in six quarters.
- DSO shipments rose by double digits.
Internationally, EMEA and Latin America also grew double digits. The problem is monetization. Revenue per case fell to $1,215 from about $1,260 in the second quarter, down 2.3% year over year. Systems and services revenue dropped 7.6% as leasing, rental, certified pre-owned and lower-priced scanner configurations reduced reported revenue, even though placed units grew double digits. Management noted that like-for-like scanner pricing stabilized and expects systems and services to grow in 2027. For now, that is a forecast rather than a result.
The forward-looking signals tilted softer than the quarter itself. Fourth-quarter Clear Aligner volume is guided to only low-single-digit growth, versus about 7% in the first half. Management described a broadly "reticent consumer," a notable change from the "stable" language on the prior call. Full-year GAAP operating margin guidance of about 16.2% compares with "slightly below 18%" earlier in the year, though the non-GAAP target of about 23.7% was reaffirmed. Management guided to roughly 26% non-GAAP operating margin in the fourth quarter. Its preliminary 2027 plan calls for about 100 basis points of further margin expansion without assuming a consumer recovery. That planning also assumes Clear Aligner ASPs fall another 1% to 2%, while China volume-based procurement and continued North American GP retail erosion add pricing and channel risk.
The leadership change complicates the setup further. Joe Hogan is stepping down, and former P&G healthcare executive Jennifer Davis becomes CEO on December 31. The handoff comes mid-way through a strategic and operating review that includes an Elliott-linked board member. Detailed 2027 guidance has been deferred to the next report under the new CEO. That could prove a catalyst if Davis resets the plan credibly, but it also extends the period of uncertainty. On the supportive side, the full-year buyback rises to about $500 million, with up to $300 million in the fourth quarter. The Invisalign Sports Guard pilot, sized by management at $6 billion to $8 billion, offers optionality, though not near-term revenue.
Investors were already skeptical heading into the report. Earnings Whispers sentiment, measured before the release, weakened from -0.22 to -0.34, a meaningful move deeper into negative territory. Shares are down 15.9% from the open after the July report, sitting about 10% below the 200-day moving average of $169.10. The stock had rebounded about 10% from its October 8 low of $138.05 but remains roughly 19% below the post-July high. Trend readings are mostly negative on price and AVWAP, with momentum the lone positive.
The bottom line is that Align beat on earnings by controlling costs and buying back stock, while the drivers that ultimately matter are softening. Revenue growth, pricing, gross margin and fourth-quarter volume expectations all weakened. Record volumes and the North American orthodontist recovery give the bull case some substance. Still, with guidance trimmed, ASPs eroding and a new CEO set to define 2027, bears have legitimate ammunition. The margin story alone may not be enough to reset sentiment.
Read our earnings preview for Align Technology, Inc.: https://www.earningswhispers.com/article/ALGN/20896
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-26 | |
| Oct-20 | |
| Oct-16 | |
| Oct-05 | |
| Oct-05 | |
| Oct-01 | |
| Sep-28 | |
| Sep-22 | |
| Sep-08 | |
| Aug-31 | |
| Aug-17 |
