AGCO Must Prove Its Guidance Cut Was Enough As Europe And Brazil Weigh On Third Quarter
Three months ago AGCO swapped its bottom-of-the-cycle confidence for a more defensive posture, cutting its full-year outlook after a surprise stumble in Europe and further softness in Latin America. The third-quarter report, due before the opening bell on October 29, is the first real test of whether that reset cleared the decks or simply marked the start of a longer slide. With management having already guided to a deliberately soft quarter, the numbers matter less than what they reveal about the trajectory into 2027.
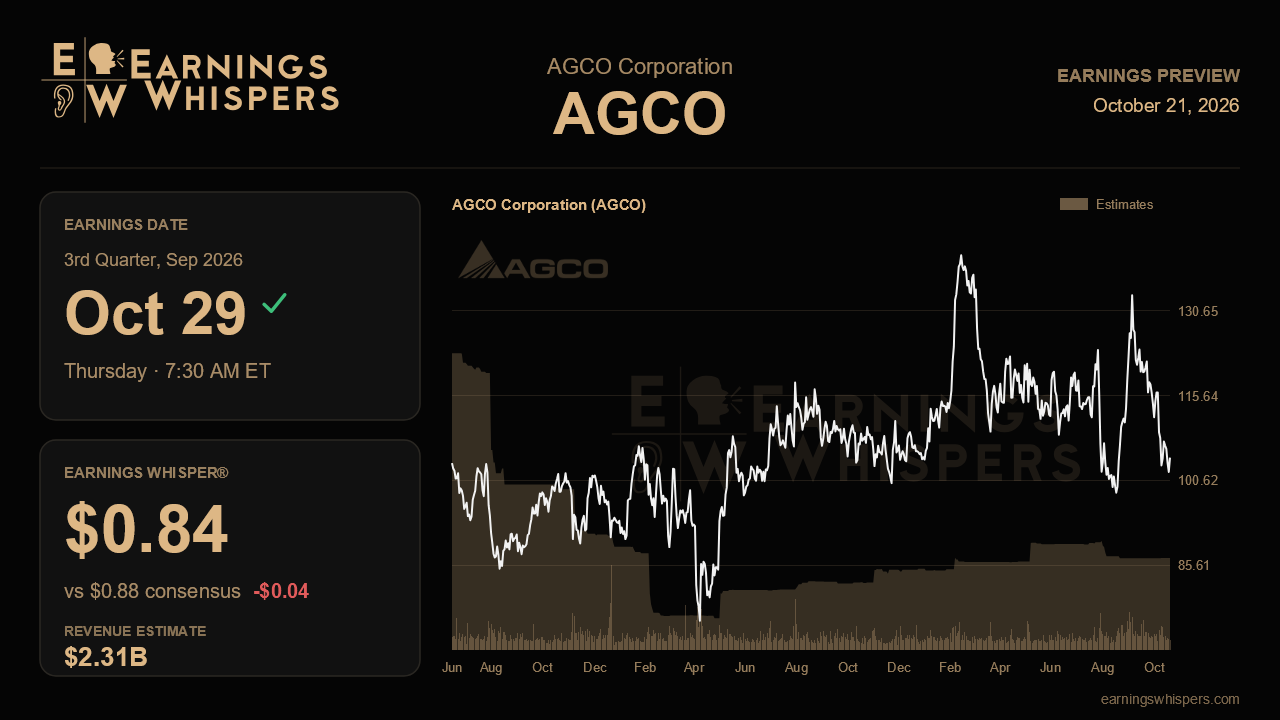
Wall Street expects earnings of $0.88 per share on revenue of $2.31 billion, which would mean a decline of roughly 35% in profit and nearly 7% in sales from a year ago. That is a sharp contraction, and it reflects production cuts in Europe and Latin America that management flagged when it guided to $0.85 to $0.90 for the quarter. Consensus sits right at the midpoint of that range, while the Earnings Whisper of $0.84 falls just below the low end, a sign that some investors suspect even the lowered bar could prove a stretch. The full-year picture is more awkward. AGCO now guides to $5.50 to $5.75 per share on $10.1 billion to $10.2 billion in revenue, yet consensus still sits at $6.20 on $10.53 billion, above the top of management's range. Either those estimates have not caught up, or the Street is betting on a fourth-quarter rebound that the company has not promised. Expect that gap to close, likely to the downside, once the outlook is reaffirmed or revised.
Europe is the swing factor. It is AGCO's largest and most profitable region, and last quarter Germany's market came in about 15% worse than expected while dealers pulled inventory down to roughly 3.5 months, removing a couple hundred million dollars of sell-in. The constructive interpretation is that destocking is largely done and shipments can more closely track retail demand. Confirmation would come from stable European margins and commentary that Western Europe is holding around flat. Further destocking or another downgrade to the regional outlook would challenge that view. In Brazil, where the industry outlook was cut to a decline of 5% to 10% and subsidized FINAME loans arrived late, the question is whether Latin America can keep inching toward breakeven after a $49 million year-over-year drop in operating income in the second quarter.
North America was the bright spot, with constant-currency sales up 20% on high-horsepower tractors, hay tools and genuine retail share gains tied to the full Fendt lineup. Sustaining that strength while dealer inventories move toward the six-month target would show the share story is durable rather than a one-quarter fill. Small ag, now seen flat to down 5%, deserves attention too. On costs, AGCO raised its efficiency savings goal to $60 million to $70 million and lowered net tariff costs to $95 million after a $22 million refund, with additional refunds offering upside not built into guidance. Cash flow is another pressure point after a first-half outflow of about $347 million, especially following roughly $345 million in buybacks.
The market has not been forgiving. Shares have fallen about 5% since the last report while the S&P 500 gained 4.5%, and at about $105 the stock trades well below its 200-day moving average near $116 and sits in the lower part of its post-earnings range, not far above the $98 low. Sentiment has also turned slightly more bearish than it was heading into the prior report.
That skepticism lowers the bar somewhat, but it does not remove the central question. AGCO needs to show that its reduced guidance holds, that European destocking has run its course, and that North American share gains can offset weakness elsewhere. A reaffirmed outlook with steadier cash generation would suggest the trough is in sight; another cut would imply the reset was not deep enough.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-20 | |
| Oct-09 | |
| Oct-07 | |
| Oct-07 | |
| Oct-07 | |
| Oct-05 | |
| Oct-05 | |
| Oct-01 | |
| Sep-30 | |
| Sep-25 | |
| Sep-17 | |
| Sep-09 | |
| Sep-02 | |
| Sep-01 |
