AGCO Clears A Low Bar But Cuts Guidance A Third Time As The Ag Trough Sinks Below The Prior Low
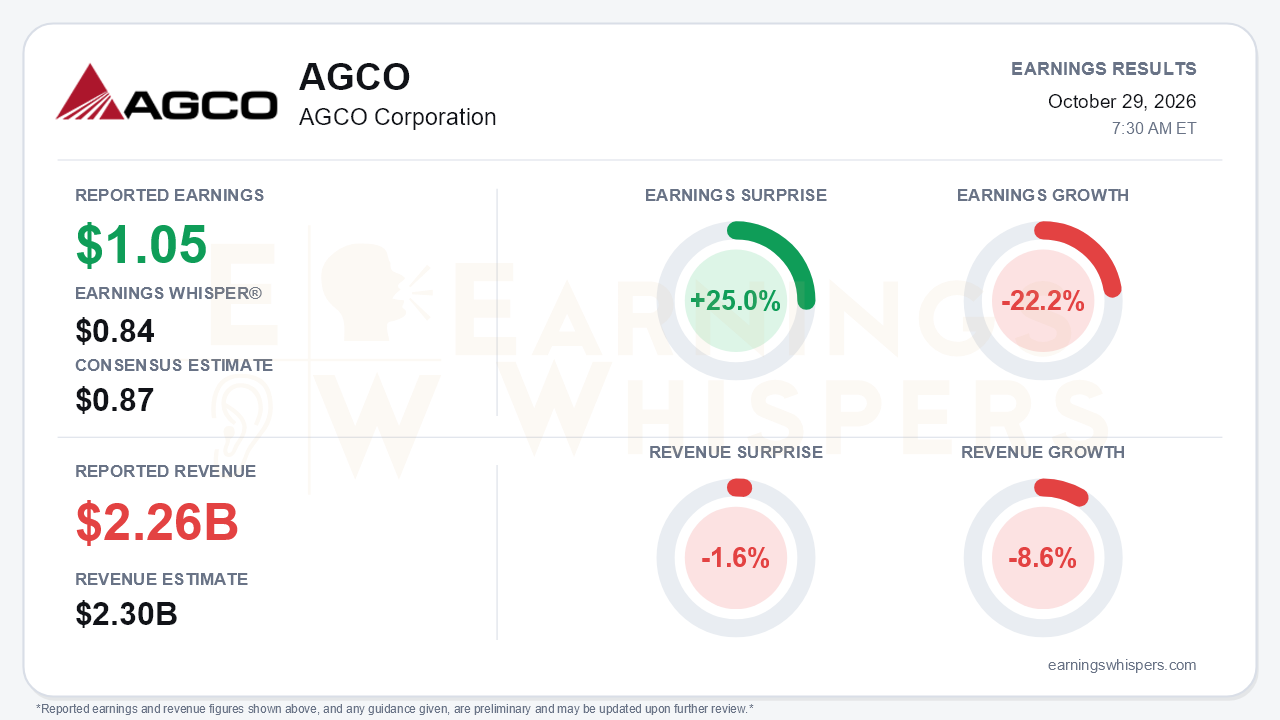
AGCO delivered a sizable earnings beat in a quarter that did little to improve the outlook. Adjusted EPS of $1.05 topped the $0.87 consensus by 25.0% and cleared the $0.84 Earnings Whisper number, but revenue of $2.263 billion missed by 1.6%. Earnings fell 22.2% year over year and sales fell 8.6%. Both comparisons mark a clear deceleration from the first nine months, when sales were up 0.7% and adjusted EPS rose to $3.42 from $3.11. Management also cut full-year guidance for the third straight quarter. The 2026 sales range fell to $9.8-$10.0 billion from $10.1-$10.2 billion, the adjusted operating margin target fell to about 7% from about 7.5%, and adjusted EPS is now about $5.50, the bottom of the prior $5.50-$5.75 range. That is the central tension: AGCO is executing well against expectations that keep moving lower.
The quality of the beat deserves scrutiny. The Q3 result came in above the $0.85-$0.90 target management set on the Q2 call, but several supports were non-operating or one-time. Diluted shares fell to 69.5 million from 74.7 million after $403.7 million of buybacks this year, which lifted per-share results. North America's swing to a $13.8 million operating profit from a $42.0 million loss included roughly $13 million of IEEPA tariff refunds. Management described the region as about breakeven without them. Those refunds, about $35 million year to date, are not assumed going forward, and the company warns it could have to repay them depending on the government's appeal. Adjusted operating margin fell 140 basis points to 6.1%. GAAP EPS of $0.75 compares with $4.09 a year ago, but the prior-year figure was inflated by a $2.93-per-share gain on the sale of AGCO's TAFE stake, so the GAAP decline overstates the deterioration.
Beneath the headline, the regional picture split sharply. North America is accelerating: constant-currency sales rose 35.1%, after gains of 20% in Q2 and 9% in Q1. Large-ag market share is up more than 200 basis points and parts sales rose about 12%. AGCO's largest region moved the other way. EME sales fell 18.1% in constant currency and EME operating income dropped about $115 million. That compares with roughly flat EME profit in Q2 and a $104 million gain in Q1. Latin America sales fell 19.1%. Dealer inventory there rose to just under five months from about 3.5 months in Q2, reversing the destocking progress management highlighted last quarter. Brazil's subsidized Finame financing is reaching only about 10-11% of buyers versus roughly 80% historically. The election outcome management had hoped would bring farmer-friendly policy clarity did not deliver it. Management now estimates global industry demand at about 83% of mid-cycle, below the prior cyclical trough. That figure has slipped every quarter, from 87% last year to 86% in Q1 and 85% in Q2. Management's tone shifted accordingly, from "operating around the trough" earlier in the year to conditions that are "even more challenging."
The list of cuts is long:
- Pricing assumption to 1.5-2%
- Currency benefit to about 1%
- Production hours to about 5% below 2025
- Brazil industry outlook to about -15%
- Western Europe tractor outlook to flat to -5%
- Capex to $250-$300 million
There are credible offsets for 2027:
- North America's early order program is up high-teens to about 20% by volume. Management cautioned, however, that it covers only 20-25% of regional sales and overstates the tractor read-through.
- European dealer inventory is below the four-month target, the fleet is the oldest on record, and drought-relief subsidies are in place. Management expects 2027 production to run close to retail in North America and EME, with some European restocking.
- About $40 million of cost-savings carryover supports a roughly $200 million run-rate.
Latin America looks likely to be underproduced into next year, and El Niño adds yield risk. The CFO transition, with Damon Audia moving to run PTx, adds a layer of change at a delicate moment.
The balance sheet gives bears legitimate ammunition. Year-to-date free cash flow is about -$381 million versus +$65 million a year ago. Inventories rose to $3.0 billion from $2.7 billion. Cash fell to $415 million from $862 million, while borrowings due within one year climbed to $536 million from $118 million. Management reaffirmed its 75-100% cash conversion target, but meeting it depends heavily on the fourth quarter. The guidance math puts similar weight on Q4: the full-year target implies roughly $2.08 of adjusted EPS in the final quarter.
The market had already been leaning negative. Investor sentiment slipped modestly to -0.30 from -0.27, a small move toward pessimism rather than capitulation. Shares closed at $102.16 the day before the report. That was down 7.1% since the open following the July report and 12.2% below the 200-day moving average. The stock rallied to $135.17 in early September but gave all of it back, entering earnings near the bottom of its range and just 4% above the 52-week low of $98.22 set in August. The Earnings Whispers trend signals are mostly negative, with price, momentum and AVWAP readings all pointing lower.
The bottom line is that AGCO beat a lowered bar while the cycle kept getting worse. North America's share gains, early orders and cost actions preserve a believable recovery story for 2027. But a third consecutive guidance cut, a demand trough now below the last one, refund-aided regional profits and a back-end-loaded cash target mean the beat changes less than the 25.0% surprise suggests.
Read our earnings preview for AGCO Corporation: https://www.earningswhispers.com/article/AGCO/21019
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 8 hours | |
| 9 hours | |
| Oct-28 | |
| Oct-26 | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-09 | |
| Oct-07 | |
| Oct-07 | |
| Oct-07 | |
| Oct-05 | |
| Oct-05 | |
| Oct-01 |
