ASE's Third Quarter Tests Whether Margins Can March Toward 30% As Capex Soars
ASE Technology enters its third-quarter report with a problem most companies would envy: management says demand for its advanced packaging and test capacity is running ahead of its ability to build. That makes this release less about whether customers want more and more about whether ASE can turn a historic spending spree into the margin expansion it has promised. With guidance raised at every call this year, the bar is no longer whether the story is good. It is whether the next step up arrives on schedule.
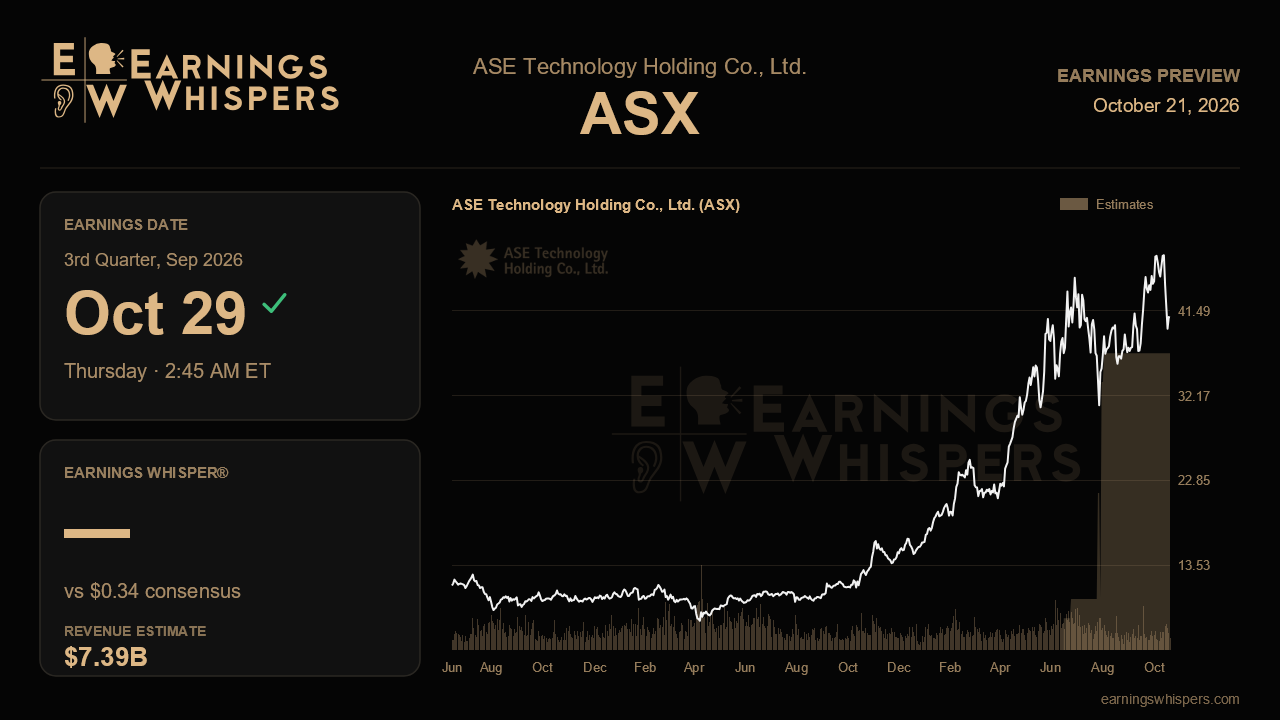
Wall Street expects earnings of $0.34 per share, more than double the $0.16 earned a year ago, on revenue of about $7.39 billion, up 31.2% year over year. That is a step up from last quarter's $0.29 and $6.04 billion. Management guided consolidated revenue up 21% to 22% sequentially, which points to roughly $7.31 billion to $7.37 billion, so consensus sits a hair above the top of that range. The gap is small enough that currency could explain it, but it tells you analysts are already assuming ASE lands at or beyond the high end. A result merely inside guidance could read as a soft quarter even if it is a record.
The most important number may be the assembly, test and materials gross margin. It climbed from 26.0% in the first quarter to 27.3% in the second, and management guided 28% to 29% for the third, with the fourth likely to break above the 30% level the company has long treated as a structural ceiling. Executives even said they would review lifting that range. A third-quarter print at or above 29% would make that pledge feel conservative; a figure at the low end, or blamed on start-up costs from new lines, would raise doubts about the fourth-quarter breakthrough. Utilization is the swing factor here, since blended rates were only 80% to 85% while equipment and buildings were still being installed. Evidence that newly installed tools are filling quickly would validate the claim that ASE is capacity-gated rather than demand-gated.
The AI-driven leading-edge packaging business, which ASE calls LEAP, is the engine behind all of this. Its full-year target has been raised from roughly doubling to tracking ahead of $3.5 billion, and management has set an explicit goal to double it again next year. Investors should look for confirmation that the trajectory is intact, along with progress on the full-process co-op program, which is targeted at about $300 million this year, and early signs from the 310x310 panel line and co-packaged optics launch slated for the turn of the year. Meanwhile, electronics manufacturing services is guided to jump about 40% sequentially, but its operating margin slipped to 2.4% last quarter on mix and memory costs. Management called those costs a pass-through; this quarter should show whether that holds.
The balance sheet is the quieter risk. Capital spending has been lifted repeatedly to roughly $10.5 billion, quarterly capex now exceeds EBITDA, free cash flow has turned negative, and net debt to equity rose to 47%. Last quarter's net income was also flattered by sizable mark-to-market gains that may not repeat, so the quality of the earnings beat matters as much as the headline figure.
The market has paid up for this story. Shares have gained about 26% since the last report against roughly 4.5% for the S&P 500, and at $40.77 they sit comfortably above the 200-day average near $32 but around 15% below the post-earnings high of $47.93. Sentiment has cooled modestly from the prior quarter despite the rally, suggesting some fatigue at elevated levels. Ultimately, the narrative stays intact if margins keep climbing toward 30% while capacity comes online fast enough to justify the borrowing. If spending outruns profitability, the super-cycle thesis will face its first real question.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-19 | |
| Oct-16 | |
| Oct-13 | |
| Oct-12 | |
| Sep-09 | |
| Aug-10 | |
| Aug-07 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-09 | |
| Jun-24 | |
| Jun-09 | |
| May-26 |
