ASE Technology Beats As ATM Margins Clear 30% Early, But A Third CapEx Raise Puts The Balance Sheet In Play
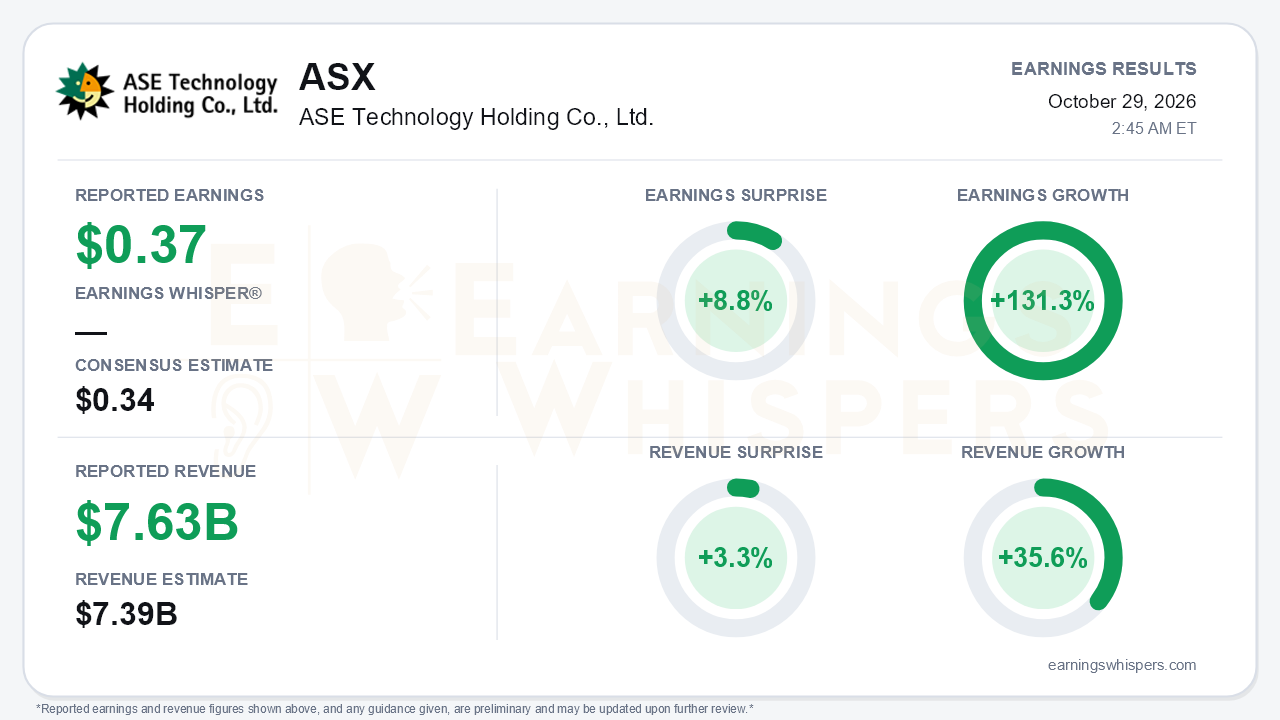
ASE Technology Holding delivered a clean beat and a materially stronger outlook. The company reported third-quarter earnings of $0.37 per ADS on revenue of $7.635 billion, ahead of the $0.34 consensus by 8.8% and the $7.39 billion revenue estimate by 3.3%. Earnings grew 131.3% year over year and revenue rose 35.6%. In local currency the top line was even stronger, up 44.8% to a record NT$244.2 billion; the gap reflects a weaker New Taiwan dollar against the year-ago period. The central takeaway is that ASE's advanced-packaging business has moved into a higher margin regime faster than management expected. The central tension is that funding that growth is consuming cash and adding leverage at an accelerating rate.
The quality of the beat holds up well. Operating income jumped to NT$33.1 billion from NT$21.1 billion in the second quarter, and consolidated operating margin widened to 13.6% from 11.1%. Non-operating items actually swung to a NT$432 million net expense from NT$4.6 billion of income a quarter earlier. In other words, pretax profit rose despite weaker below-the-line results, not because of them. The engine was the assembly, testing and materials (ATM) segment:
- **ATM revenue** grew 20.1% sequentially, against an 11-13% guide.
- **ATM gross margin** reached 30.6%, versus a 28-29% guide and 27.3% in the second quarter.
- **ATM operating margin** rose to 20.0% from 15.7%.
Computing climbed to 34% of ATM revenue from 25% a year ago. Flip chip, bumping, wafer-level and system-in-package work reached 51% of the mix. Both shifts point to AI-related advanced packaging as the driver.
The conference call reinforced that this is a trajectory, not a one-off. Management had said in July that the 30% ATM gross-margin ceiling would likely be breached in the fourth quarter. It happened a quarter early, and management now describes the old ceiling as the new base, with sequential gains expected every quarter in 2027 in what it called a "very pricing friendly" environment. Full-year guidance moved up again across several measures:
- **2026 LEAP (advanced packaging) revenue** is now above US$4 billion. That is the fourth consecutive increase, from US$3.2 billion at the start of the year, and the expected doubling in 2027 was reaffirmed.
- **Growth in the general, non-LEAP business** is now guided above 20% for 2026, up from 13% earlier in the year, with similar growth expected in 2027.
- **New 2027 targets** include more than US$1 billion of full-process revenue, up from roughly US$300 million in 2026, and more than US$0.5 billion from co-packaged optics, which entered mass production this quarter.
- **Fourth-quarter guidance** calls for consolidated revenue up 6-8%, gross margin of 23-24% and operating margin of 14.5-15.5%. ATM revenue is guided up 11-13% with another 100-200 basis points of gross-margin expansion.
Bears have legitimate ammunition, and most of it sits on the balance sheet. 2026 capital spending was raised for a third time, to US$11.5 billion from US$10.5 billion in July and roughly US$8.5 billion earlier in the year, compared with US$5.5 billion actually spent in 2025. Management expects 2027 spending to be higher still and negative free cash flow to continue into next year. Third-quarter payments for property and equipment of NT$125.9 billion were roughly two and a half times operating cash flow of NT$50.5 billion. Interest-bearing debt rose about NT$100 billion in a single quarter to NT$406.5 billion, net debt to equity climbed to 0.66 from 0.47, and net interest expense rose to NT$2.6 billion.
Other risks are narrower but real:
- **EMS margins:** The electronic manufacturing services business is being diluted by memory pass-through costs. EMS gross margin slipped to 8.3%, and fourth-quarter EMS operating margin is guided to about 2% on flat revenue.
- **Customer concentration:** The top five EMS customers now account for 70% of segment revenue, up from 58%.
- **Capacity and competition:** Space constraints are forcing ASE to prioritize assembly over test. Management also flagged potential competition in on-substrate packaging from a foundry partner's subsidiary.
- **End demand:** PC and smartphone demand remains soft.
The market setup is more complicated than the surprise implies. Shares rose 35.9% from the open after the July report to $43.92 heading into this release, about 33% above the 200-day moving average. Yet the stock sat 8.4% below its October 2 52-week high of $47.93, so some of the run had already been given back. Investor sentiment remained positive but fell noticeably, from 0.45 to 0.21. That suggests enthusiasm cooled even as the price held most of its gains, possibly reflecting concern over capital intensity. The Earnings Whispers trend signals are mostly positive, with sequential growth, momentum and AVWAP readings favorable while the price trend is neutral.
The bottom line is that ASE's third quarter strengthened the operating story. Margins are running ahead of plan, guidance keeps rising, and new 2027 revenue streams have been quantified. The trade-off is a business that is borrowing heavily to keep pace with demand. As long as pricing power and LEAP growth keep outrunning rising debt and interest costs, the expansion looks justified. But the investment case now depends as much on execution of the capital plan as on demand, and cooling sentiment suggests investors are starting to weigh that cost.
Read our earnings preview for ASE Technology Holding Co., Ltd.: https://www.earningswhispers.com/article/ASX/21027
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-21 | |
| Oct-19 | |
| Oct-16 | |
| Oct-13 | |
| Oct-12 | |
| Sep-09 | |
| Aug-10 | |
| Aug-07 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-09 |
