Avery Dennison's Pre-Buy Hangover Arrives As Street Tests Its Reinstated Full-Year Outlook
Avery Dennison told investors last quarter exactly how its third quarter would look worse, and that is what makes this report interesting. Second-quarter adjusted EPS of $2.89 jumped 19% on 8% organic growth, but management said roughly half of that growth, worth about $0.25 a share, came from customers stocking up ahead of raw-material price increases. It warned that most of that pull-forward should unwind in the third quarter, creating a sequential headwind of about $0.50. The real question is whether the business underneath the pre-buy noise is as healthy as management claims.
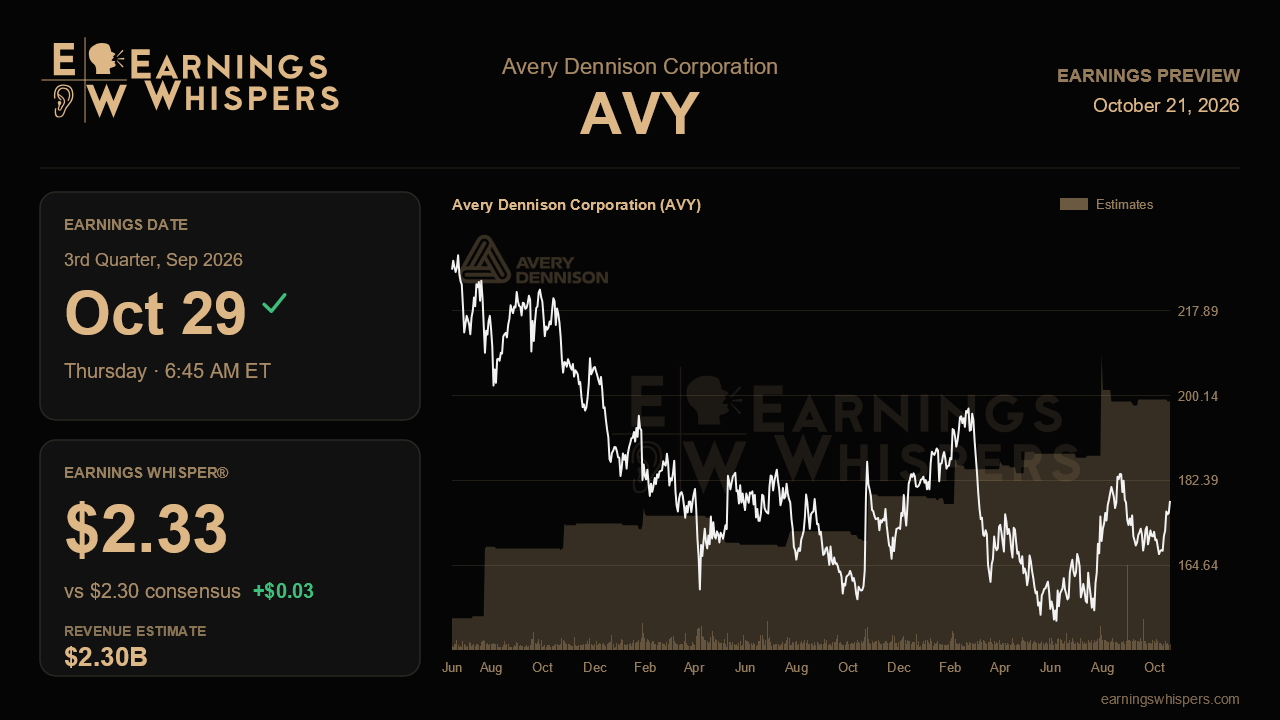
Wall Street expects EPS of $2.30 on revenue of about $2.30 billion. That would mean sales up 3.8% from a year ago but earnings down 3% from $2.37. The earnings decline is misleading if read as fading momentum. Subtracting management's flagged headwind from the second quarter points to something in the high $2.30s, so consensus already builds in extra caution, probably for rising input costs. The Earnings Whisper of $2.33 sits only modestly above consensus. That suggests a slightly higher bar, not a dramatic one, and leaves the reported figure within reach of the company's own roadmap.
The full-year guidance makes this quarter a credibility check. After three quarters of offering only quarterly outlooks, Avery reinstated an annual target of $10.00 to $10.30 in adjusted EPS, roughly 7% growth, with organic sales up 3% to 4%. Consensus sits at $10.00, the very bottom of that range. With $5.36 already banked in the first half, a $2.30 third quarter would require only about $2.34 in the fourth to hit the low end, below last year's $2.45. Analysts are clearly reluctant to give credit for upside. A clean quarter and a reaffirmed range would argue the Street is too conservative. Any trim toward the bottom would suggest the destock or inflation is biting harder than expected.
The operating details matter more than the headline. Management said Materials Group grew at a mid-single-digit pace even excluding pre-buys, and that high-value categories recovered. Signs that underlying volume held up as inventories normalized would support that view. Raw-material inflation is the main swing factor. Management expects it to reach the high single digits in the second half, after deflation in late 2025. Margins will show whether pricing keeps pace. The second-quarter EBITDA margin of 17.1%, and an 18.6% margin in Solutions, set a high mark, and restructuring savings now above $60 million should provide a cushion. Management also suggested inflation could push customers toward the market leader in Europe and Asia, and evidence of share gains there would be a quiet positive.
Intelligent Labels is the other test. Enterprise growth slowed to low single digits as logistics fell by double digits. Management pointed to the Kroger food rollout ramping and Walmart's fresh-grocery commercial launch, both beginning in the second half, as the catalysts that should change that. This is the first quarter where those programs should start showing up, so commentary on their pace will carry weight. World Cup-related strength in Embellex is a smaller tailwind that should help apparel-related results.
Investor mood has improved, with bearish sentiment easing to about 17% from nearly 44% before the last report. Yet the stock has slipped 4% since then while the S&P 500 rose 4.5%, as the market has discounted the expected payback. Shares at $178 sit above the 200-day average and in the upper half of the post-earnings range, roughly 5% below the $187.91 high. The central issue is whether, once the pre-buy unwinds, underlying demand and pricing are strong enough to keep the reinstated full-year range intact. If so, the gap between improving fundamentals and lagging shares could close quickly.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-12 | |
| Oct-01 | |
| Sep-16 | |
| Aug-07 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-23 | |
| Jul-15 | |
| Jul-01 | |
| Jun-16 | |
| Jun-15 | |
| Jun-04 |
