Avery Dennison Beats On Slower Destocking And Buybacks, But Walmart RFID Delay And Margin Squeeze Temper The Quarter
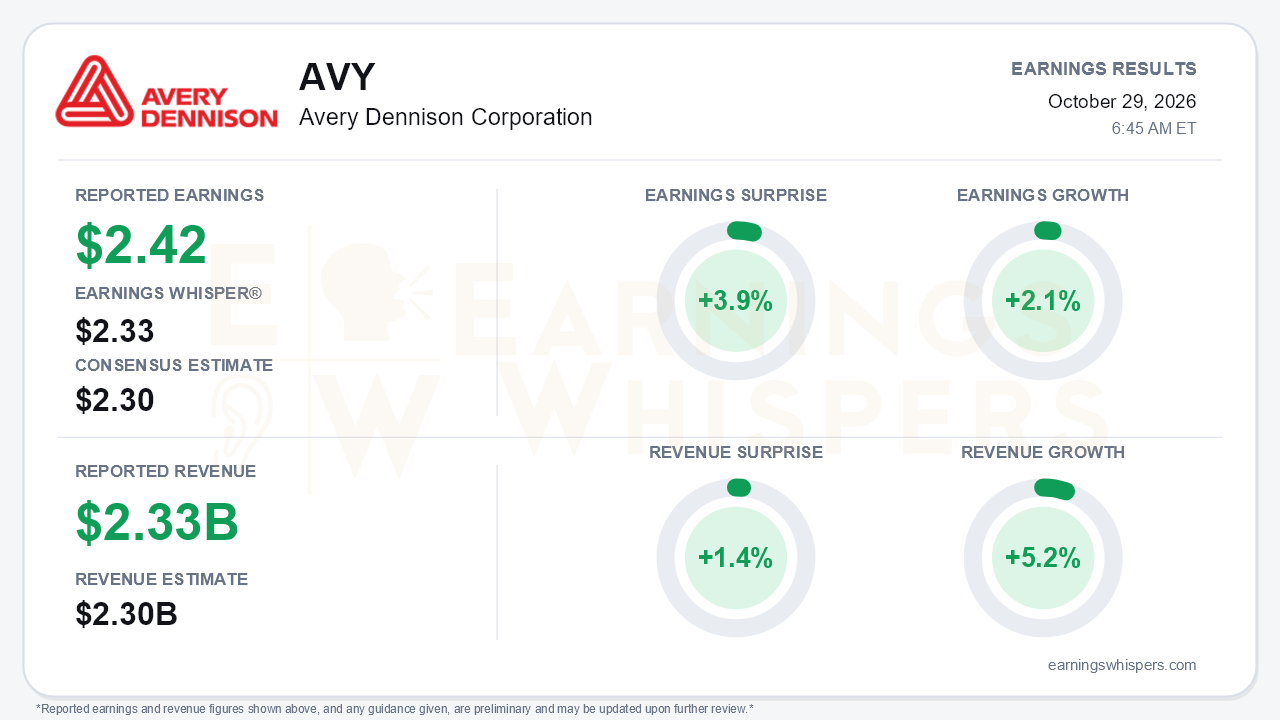
Avery Dennison (NYSE: AVY) cleared the bar in the third quarter, but the beat looks more like timing and financial engineering than a fundamental re-acceleration. Adjusted EPS of $2.42 topped the $2.30 consensus and the $2.33 Earnings Whisper number by 3.9%. Revenue of $2.332 billion beat the $2.30 billion estimate by 1.4%. The trajectory is the problem. Earnings grew just 2.1% year over year, a sharp deceleration from the roughly 19% growth delivered in the second quarter. Revenue rose 5.2%, while organic sales grew a more modest 3.7%. That is the central tension: the company outperformed what the Street expected for the quarter while its earnings growth rate collapsed and a key growth catalyst slipped another year.
The quality of the beat deserves scrutiny. Adjusted net income actually declined 0.8% to $183.3 million. Per-share growth came entirely from a lower diluted share count, 75.9 million versus 78.0 million, after $257 million of year-to-date buybacks. Margins moved the wrong way:
- Adjusted operating margin slipped to 12.1% from 12.7%.
- Adjusted EBITDA margin fell to 15.8% from 16.5% a year ago and from 17.1% in the second quarter.
- Corporate expense rose to $23.4 million from $18.7 million.
- The adjusted tax rate edged up to 26.9%.
GAAP EPS rose a firmer 5.2% to $2.24, helped by lower restructuring and other charges. Cash flow was the cleanest part of the report. Year-to-date adjusted free cash flow reached $716 million versus $405 million last year, already above the full-year 2025 total.
The segment split tells the operating story. Materials Group posted 4.9% organic growth with mid-single-digit gains in both high-value and base categories and continued share gains. Its adjusted EBITDA margin, however, fell 110 basis points to 16.4%. The call attributed the decline to price pass-through dilution from mid-to-high single-digit raw material inflation, incentive compensation normalization and mix. Solutions Group grew only 0.8% organically yet expanded its EBITDA margin 80 basis points to 17.8% on productivity. Within RFID, the picture is uneven:
- Apparel and general retail rose roughly 10%.
- Logistics fell double digits for a third straight quarter.
- Overall Intelligent Labels growth was only low single digits.
The call also explained why the quarter beat internal plans: destocking proceeded more slowly than expected. That flatters the third quarter but pushes the remaining unwind, mainly in Europe, into the fourth quarter. It lands alongside a roughly 1.5-point calendar-shift sales headwind. Management framed underlying, ex-destocking growth at about 6% organic and 8% EPS, a more constructive read than the headline suggests.
The most consequential development was the delay of the Walmart Fresh RFID ramp. Management had guided to a second-half 2026 start in each of the prior three quarters, and the launch now moves into 2027. The expected second-half inflection in Intelligent Labels will not happen this year, and bears have legitimate ammunition on execution credibility around the food opportunity. Management offered partial offsets:
- A third large grocer has entered early-stage commercial rollout, and the food pipeline is broadening.
- Vestcom SaaS is commencing with major U.S. grocers, and beauty and personal-care RFID pilots are underway.
- A new Solutions Group president arrives November 3.
- The restructuring savings target rose again to more than $65 million, its fourth straight increase, with about $0.20 of carryover into 2027.
Full-year adjusted EPS guidance was narrowed to $10.10 to $10.24 from $10.00 to $10.30. The midpoint edged up only slightly, implying about 7% growth. The free cash flow conversion target was lifted above 100%, while capex was trimmed to about $240 million.
The market setup is more complicated than the surprise implies. Investor sentiment remained negative but improved meaningfully heading into the report, rising from -0.44 to -0.16. Shares closed at $180.70 before the release, down 2.6% from the open after the July report. They sat about 3.8% below the inter-earnings high of $187.91, set the day of that report. After sliding to a $164.10 low on October 8, the stock rebounded roughly 10% and finished about 5% above its 200-day moving average. The Earnings Whispers price, momentum and AVWAP trend readings are positive, reflecting that recovery, while sequential growth is neutral. Expectations had already been rebuilding into a quarter that beat but deferred its most visible catalyst.
The bottom line is that Avery Dennison delivered a credible beat, exceptional cash generation and steady cost execution, but the underlying earnings engine is idling. Flat adjusted net income, compressing Materials margins and a Walmart RFID delay leave 2026 dependent on buybacks and restructuring. Real growth now hinges on a 2027 ramp that has already slipped once.
Read our earnings preview for Avery Dennison Corporation: https://www.earningswhispers.com/article/AVY/21029
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-26 | |
| Oct-23 | |
| Oct-21 | |
| Oct-12 | |
| Oct-01 | |
| Sep-16 | |
| Aug-07 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-23 | |
| Jul-15 |
