Baxter Must Prove Its Turnaround Holds Without A Tariff Refund Cushion
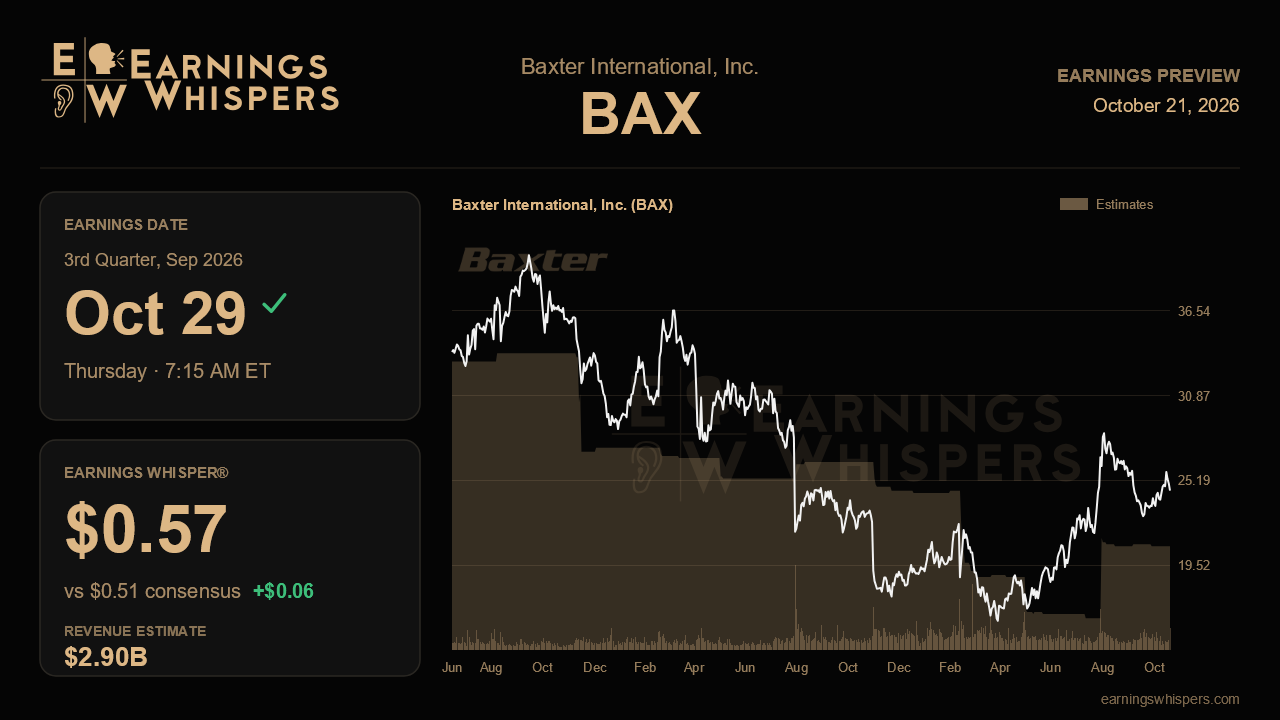
Baxter's last report delivered something the company had not offered in a long while: a raised revenue outlook and a management team that sounded genuinely confident. The market's reaction since then has been far less generous. Shares have fallen 15.7% since that report while the S&P 500 gained 4.5%, leaving the stock about 20 percentage points behind the benchmark. That gap frames the October 29 report, due before the open. The question is whether the second-quarter inflection was real operating progress or a quarter flattered by one-time help.
Wall Street expects adjusted earnings of $0.51 a share on revenue of about $2.90 billion. That implies sales growth of 2.3% from a year ago but a 26.1% drop in earnings, a reminder that the turnaround is still rebuilding profitability rather than expanding it. The comparison with last quarter matters. Second-quarter EPS of $0.56 included roughly $0.11 from a non-recurring tariff refund, so the underlying figure was closer to $0.45. Against that baseline, the $0.51 consensus already assumes real sequential improvement. The Earnings Whisper of $0.57 sits meaningfully above consensus, which suggests some investors expect Baxter to beat even the headline number from a quarter that had the refund. That is not a low bar.
Management reaffirmed full-year EPS guidance of $1.95 to $2.15, and the $2.04 consensus sits close to the midpoint. The more telling detail from last quarter is that the full-year EPS outlook rose by less than the second-quarter beat. That implies a softer underlying second half, and it makes margins the main swing factor. Adjusted gross margin fell 210 basis points year over year to 38.6% last quarter. Operating margin in the medical products and therapies segment dropped 350 basis points to 19.3%. Revenue growth is helpful only if some of it starts reaching the bottom line. Signs that this year-over-year margin erosion is narrowing would do more to support the story than another top-line beat.
On revenue, the stronger narrative needs evidence that the 5% organic growth in the second quarter was not a peak. Management lifted full-year reported growth to 3% to 4% and organic growth to 2% to 3%. The third-quarter consensus points to some cooling from the prior pace. Drug compounding, which has grown at double-digit rates for several quarters, and advanced surgery, steady at roughly 10% to 12%, have carried the story. Investors should also want to see the hospital systems business build on its 4% reacceleration, helped by Connex360 and the Dynamo smart stretcher, which just made its first international move into Canada. The drags are well known. The Novum IQ large-volume pump hold remains unresolved and is assumed to last all year. Injectables and anesthesia face supply limits at a contract manufacturer that management expects to persist into 2027. Any resolution on Novum would be upside. Further deterioration in injectables would test the raised outlook. This is also the first full look at the newly combined Infusion Therapies and Platforms division.
Cash flow is the quieter test. Free cash flow reached $257 million through the first half, and management grew more confident about reaching roughly 3x net leverage by year-end. Hitting that target would open the door to tuck-in deals and buybacks, so continued cash generation would strengthen the investment case even if EPS is merely in line.
Sentiment has turned noticeably more bullish than it was before the last report, even as the stock has slid. At $24.51, shares remain above the 200-day moving average of $21.15. However, they sit much closer to the post-report low of $22.56 than to the $30 peak. The market appears to be pricing in skepticism about 2027, when transition services income rolls off and the tariff refund will not recur. To keep the turnaround narrative intact, Baxter needs to show that it can earn around the low $0.50s without one-time help and that margin pressure is easing. Doing both would suggest the recent selloff reached too far. Failing on margins would suggest the market's doubts were justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-07 | |
| Oct-07 | |
| Sep-30 | |
| Sep-16 | |
| Aug-20 | |
| Aug-20 | |
| Aug-19 | |
| Aug-18 | |
| Aug-18 | |
| Aug-18 | |
| Aug-04 | |
| Aug-03 | |
| Jul-30 | |
| Jul-30 |
