Baxter Beats And Raises Again As Turnaround Firms, But Margin Pressure, A New FDA Warning Letter And 2027 Headwinds Temper The Setup
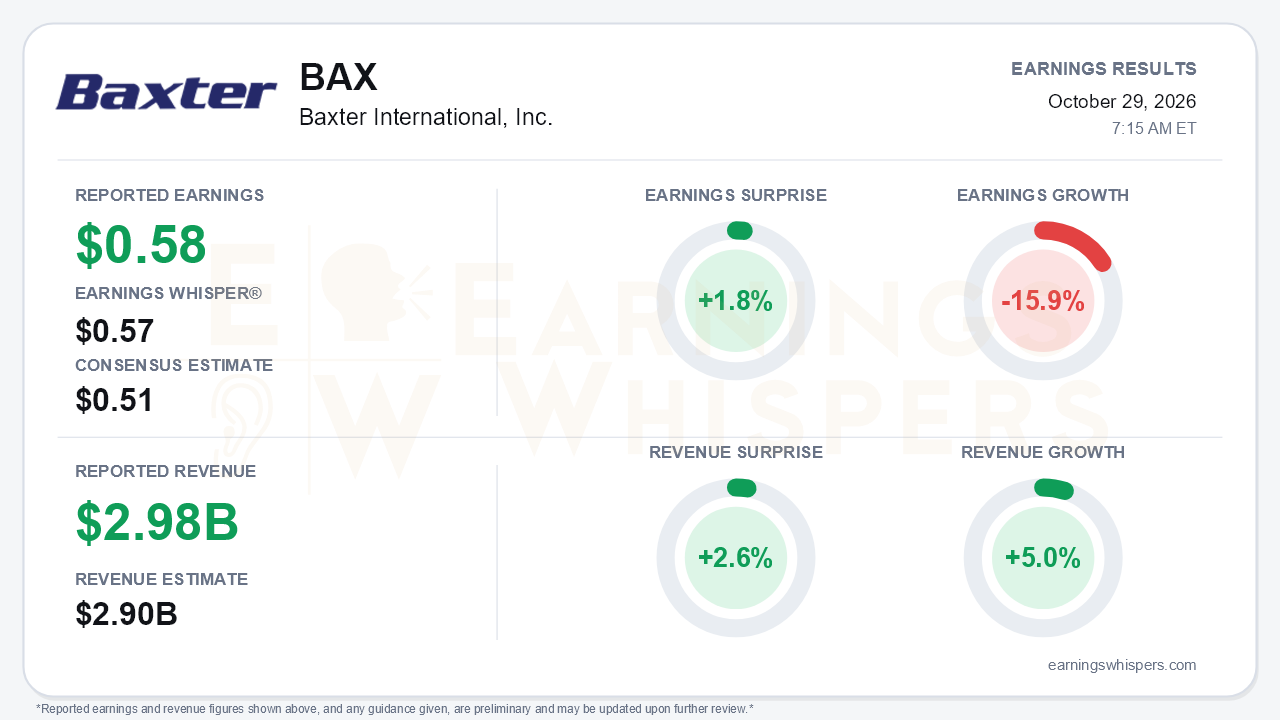
Baxter International delivered its third consecutive beat-and-raise quarter. Adjusted earnings were $0.58 per share, comfortably above the $0.51 consensus and 1.8% ahead of the $0.57 Earnings Whisper number. Revenue of $2.976 billion beat the $2.90 billion consensus by 2.6% and grew 5.0% year over year, with every segment and division contributing. The headline earnings trend still looks weak: adjusted EPS fell 15.9% from a year ago. The bigger story is that the top line has stabilized and cash generation has inflected sharply. The open question is whether that improvement can survive a crowded list of 2027 headwinds.
The EPS decline deserves context rather than alarm. Adjusted pretax income was essentially flat at $371 million versus $372 million, and adjusted operating income rose 2%. The year-over-year drop came almost entirely from tax: the adjusted effective rate rose to 18.3% from an unusually low 5.1%. GAAP results look far stronger, with $0.57 of diluted EPS versus a $0.10 continuing-operations loss a year ago, but that comparison is flattered by a $253 million gain on debt extinguishment worth $0.38 per share. The more telling details are mixed. Adjusted gross margin fell 110 basis points to 38.3% on mix and lower pricing contribution, and adjusted operating margin of 14.5% was slightly below last year's 14.9%. Sequentially, however, operating margin improved from 11.0% in Q1 and 14.2% in Q2. Healthcare Systems & Technologies was the standout, with segment margin expanding 140 basis points to 17.2%.
On the call, the revenue trajectory was the clearest positive. Organic growth of 5% matched Q2 after a 1% decline in Q1. Advanced Surgery grew 12% for a second straight quarter, and Care & Connectivity grew 5%. Beneath that, the momentum is uneven:
- Drug compounding slowed to 9% from double digits in Q2 and 20% in Q1.
- Injectables fell 3% on price deflation and manufacturing issues.
- Part of the Advanced Surgery strength stems from a competitor's supply disruption, a tailwind that may prove transient as comparisons toughen.
The guidance carries an apparent contradiction. The company describes it as raised, while the Earnings Whispers guidance note calls it narrowed. Both are accurate. Organic growth guidance moved up to 3% to 4% from 2% to 3%, and reported growth moved to 4% to 5%. The adjusted EPS range tightened to $2.05 to $2.15 because only the low end rose, lifting the midpoint without raising the ceiling. Operating margin guidance of 13% to 14% was also left unchanged. That signals management is willing to bank top-line upside but is not yet promising incremental profitability.
The balance sheet and cash flow are where the turnaround is most tangible:
- Free cash flow was $448 million, up from $181 million in Q2 and $76 million in Q1, bringing the year-to-date total to $705 million.
- A $600 million tender retired $864 million of debt, prompting a cut in the non-operating expense guide to $245 million to $255 million.
- Management expressed greater confidence in reaching roughly 3x net leverage by year-end.
- New CFO John Rogers is focused on costs and capital allocation, and management outlined tuck-in M&A in cardiac monitoring and advanced surgery plus possible buybacks once leverage targets are hit.
The risk ledger also grew, however:
- A new FDA warning letter at the Round Lake specialty injectables facility led Baxter to exit cephalosporins. That line represents roughly $50 million of 2026 sales and $30 million of operating income and becomes a net 2027 headwind.
- The Novum IQ large-volume pump remains on ship hold with no timeline.
- Management flagged further 2027 pressures, including the end of the Vantive transition services agreement in January with stranded costs, stepped-up inflation, no repeat of a tariff refund, Section 232 tariff uncertainty and product exits.
The market had already been skeptical. Shares closed at $25.46 ahead of the report, down 12.4% from the $29.07 open following the July release. The stock gave back the entire post-report spike to its $30.00 52-week high and bottomed at $22.56 in September. It entered earnings in the middle of that range but still about 19.5% above its 200-day moving average. Investor sentiment moved from slightly negative (-0.04) to modestly positive (0.10), a meaningful but not euphoric improvement. Momentum and AVWAP trend readings are positive, while price trend is neutral.
The bottom line is that Baxter's turnaround is gaining credibility where it matters most: steady organic growth, rising guidance and a dramatic step-up in cash flow and deleveraging. Bears still have legitimate ammunition. Gross margin is compressing, margin guidance was not raised, some growth drivers are decelerating or borrowed from a competitor's misfortune, and 2027 is shaping up as a year of real headwinds. The quarter improved the near-term setup more than the long-term earnings visibility.
Read our earnings preview for Baxter International, Inc.: https://www.earningswhispers.com/article/BAX/21032
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 8 hours | |
| 11 hours | |
| 11 hours | |
| Oct-21 | |
| Oct-07 | |
| Oct-07 | |
| Sep-30 | |
| Sep-16 | |
| Aug-20 | |
| Aug-20 | |
| Aug-19 | |
| Aug-18 | |
| Aug-18 | |
| Aug-18 |
