Blackstone Mortgage Trust's Dividend Decision Looms As Office Losses Test A Battered Stock
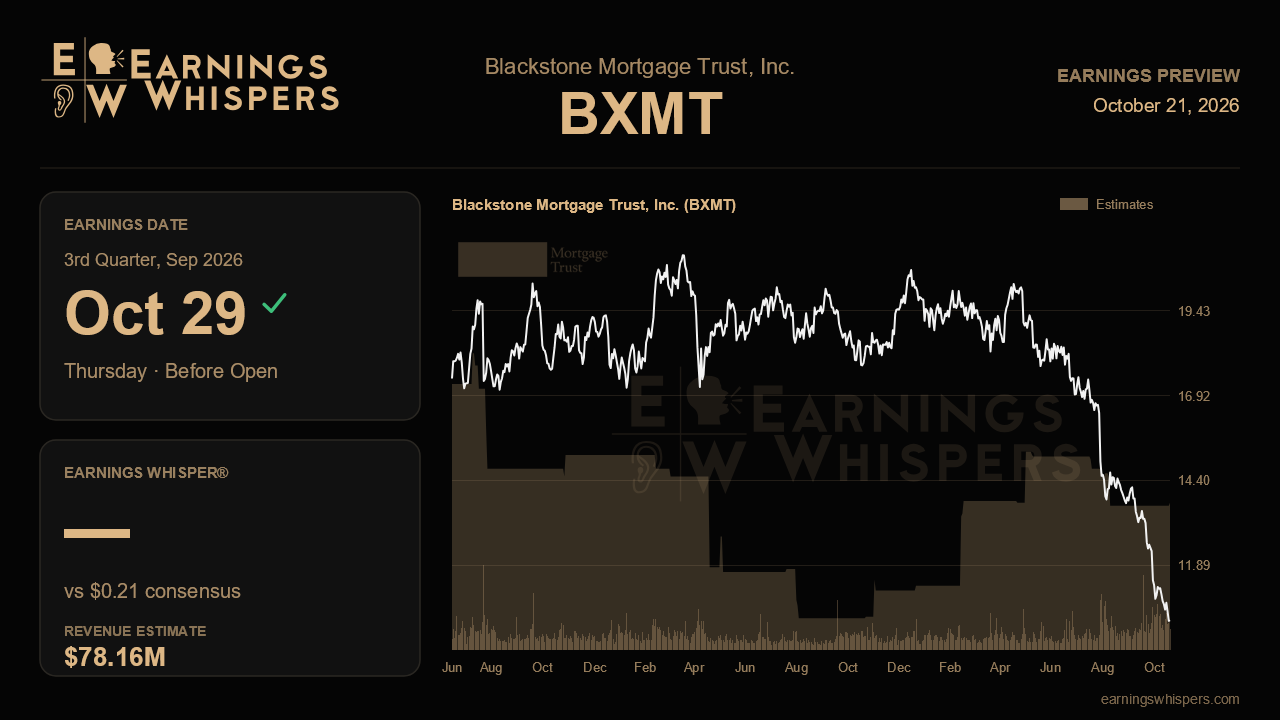
Blackstone Mortgage Trust heads into its third-quarter report with the market having already delivered a harsh verdict. Shares have fallen 35.1% since the last release, trailing the S&P 500 by nearly 40 percentage points, and at $10.27 the stock trades at barely half of June's $19.31 book value. The question is no longer whether office credit stress has returned. Management confirmed that last quarter. The question is how deep the damage runs and what the Board decides to do with a $0.47 quarterly dividend that earnings no longer comfortably support.
The Street is braced for a thin quarter. Consensus calls for earnings of $0.21 per share on revenue of $78.2 million. That EPS figure is nominally up about 10.5% from the $0.19 posted a year ago, but the comparison flatters the picture: it sits less than half of the prior quarter's $0.45 and far below the dividend. Revenue is expected to drop roughly 77% year over year and to about half of last quarter's $158.1 million, a sign that analysts expect impairments, nonaccruing loans and repayment timing to weigh heavily on the line. Management did not offer a formal numerical target, but it explicitly warned that third-quarter distributable earnings would come in lower, so a weak print is the base case rather than a surprise.
The more important tests sit beneath the headline. Last quarter brought three new impairments, led by a defaulted $345 million Chicago office loan from 2018, and pushed total loss reserves to $2.43 per share from $1.80. Management also flagged roughly $1 billion of watch-list office loans as vulnerable if elevated rates persuade institutional sponsors to stop supporting their properties. Evidence that those borrowers kept writing checks, and that the watch list continued shrinking from $2.0 billion, would suggest the June quarter was a painful but contained episode. Additional defaults within that $1 billion cohort, another sizable reserve build, or a further slide in the share of performing loans from 97% would argue the cycle has a second leg. Book value is the scorecard here; it has already fallen about 8% over three quarters.
There is a constructive story competing for attention. Net lease holdings climbed to $661 million from $222 million a year earlier, joint venture capital rose to $322 million, and the company entered homebuilder lending, targeting mid-to-high-teens levered yields. Office exposure has been cut to 21% from a 36% peak, and financing remains a genuine strength, with no corporate maturities until 2029 and most debt not subject to margin calls. Updates on the sale of the 686-key San Francisco Hyatt and the more than $1 billion of mostly office loans put up for sale will show whether the company can recycle capital without crystallizing large losses. Pricing on those exits matters as much as speed, since leverage has crept up to 3.9 times equity.
Sentiment has cooled from modestly bullish going into the last report to slightly bearish now, and the stock is sitting just above its post-earnings low of $10.12, deep beneath its 200-day average near $17. That positioning suggests a dividend cut is largely anticipated. A reset accompanied by stable credit and a credible earnings bridge could actually clear the air. The real risk is a report pairing a reduced payout with fresh office defaults and another meaningful drop in book value.
Ultimately, this release will be judged on whether the June impairments marked the peak of a final office cleanup or the opening of a new round of losses. If credit stabilizes, the diversification strategy has room to carry the narrative. If it does not, the dividend will be only the first casualty.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-16 | |
| Oct-07 | |
| Sep-15 | |
| Aug-04 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-14 | |
| Jun-15 | |
| May-11 | |
| May-05 | |
| May-05 | |
| Apr-29 | |
| Apr-29 |
