Cullen/Frost Must Prove Its Raised Outlook Can Outrun A Credit Blemish And Deposit Costs
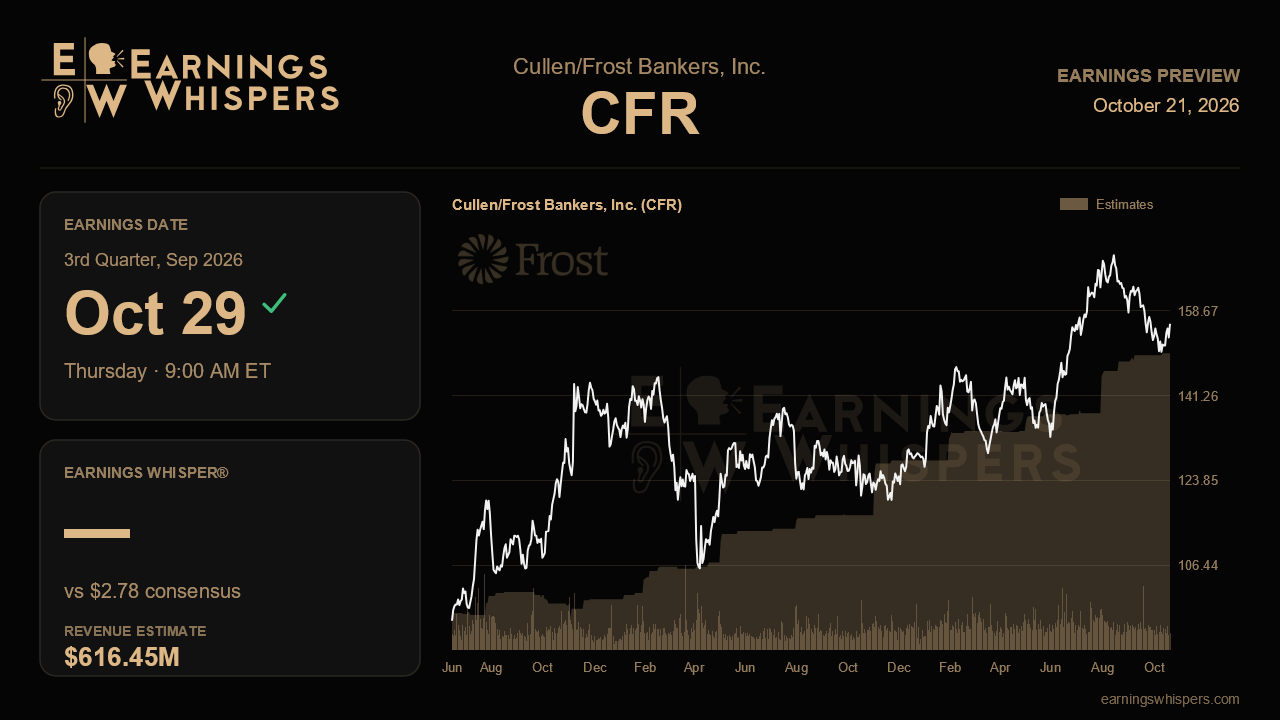
Three months ago Cullen/Frost delivered the kind of call bank investors rarely get: higher targets for net interest income, loans and fees, a lower expense forecast, and a rate outlook that flipped from a cut to a hike. The stock's response since then has been a shrug and then some. Shares have slipped 7.7% since that report while the S&P 500 gained 4.5%, leaving the Texas lender roughly 12 points behind the market. That gap frames the third-quarter report due before the open on October 29. Either the market is discounting a story it doesn't yet believe, or it has spotted cracks that management played down.
The Street is looking for earnings of $2.78 a share on revenue of about $616.5 million. That would be a 4.1% gain from the $2.67 earned a year ago and a modest step up from the $2.70 posted last quarter. It is a measured bar, not a heroic one. Management's raised full-year framework calls for net interest income growth of 4.75% to 5.25%, average loan growth of 7% to 8%, non-interest income up 7.5% to 8.5%, and expenses held to 4.5% to 5% growth. Mid-single-digit EPS growth looks consistent with that guidance rather than a stretch beyond it. The real question is whether the company can keep nudging those ranges higher after raising nearly all of them at once.
Operating leverage is the core of the bull case. Management has spent more than a year promising that expense growth, once running in the high single digits, would fall below revenue growth. Last quarter it finally showed about 140 basis points of positive leverage year to date and said it intends to sustain that into 2027. A clean third quarter would show fee income tracking toward the raised target, helped by wealth management, interchange and service charges, while costs stay inside the lowered range. Any upward drift in expenses would undercut the most important change in the story.
The margin outlook needs similar scrutiny. Net interest margin reached 3.75%, near a 15-year high. The outlook leaned on a September rate hike worth roughly $2 million a month and on a $250 million Treasury yielding under 1% that rolls off in August, with the larger benefit expected in the fourth quarter. Working against that, interest-bearing deposit costs rose to 1.61% from 1.55%, and management expects betas to drift toward the low 40s. Deposit growth guidance has sat at 2% to 3% for four straight calls. If funding costs keep climbing faster than asset yields reprice, the narrowed target of 10 to 13 basis points of margin improvement over 2025 will come under pressure.
Credit is the obvious soft spot. Non-performing assets jumped to $114 million, or 49 basis points of loans, almost entirely because of a single $55 million Austin multifamily loan from 2022 that was moving through a property sale. Management expected little loss on it and pointed to three or four similar-vintage commercial real estate credits that could migrate. Resolution of that loan, with no meaningful wave of new downgrades, would go a long way toward explaining the stock's underperformance as overdone. Criticized loans improved to $917 million last quarter, and continued improvement there would help.
Sentiment has edged more bearish, to 25.1% from 22.6%. The shares trade above their 200-day moving average near $148 but in the lower half of the post-earnings range of roughly $146 to $171. Growth evidence also matters: the record $2.17 billion loan pipeline should translate into loan balances, and consumer household growth should keep running near 5.7%. In the end, the report turns on whether Cullen/Frost can show that its organic growth engine and expense discipline are outpacing deposit competition and isolated credit problems. If that holds, the gap between the improving fundamentals and the lagging stock becomes difficult to justify.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 1 hour | |
| 4 hours | |
| Oct-08 | |
| Sep-14 | |
| Aug-31 | |
| Aug-18 | |
| Aug-03 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-09 | |
| Jul-06 | |
| Jul-06 | |
| Jul-01 |
