Cullen/Frost Beats And Raises Again, But Rising Rates Leave A Mark On Book Value And Deposit Costs
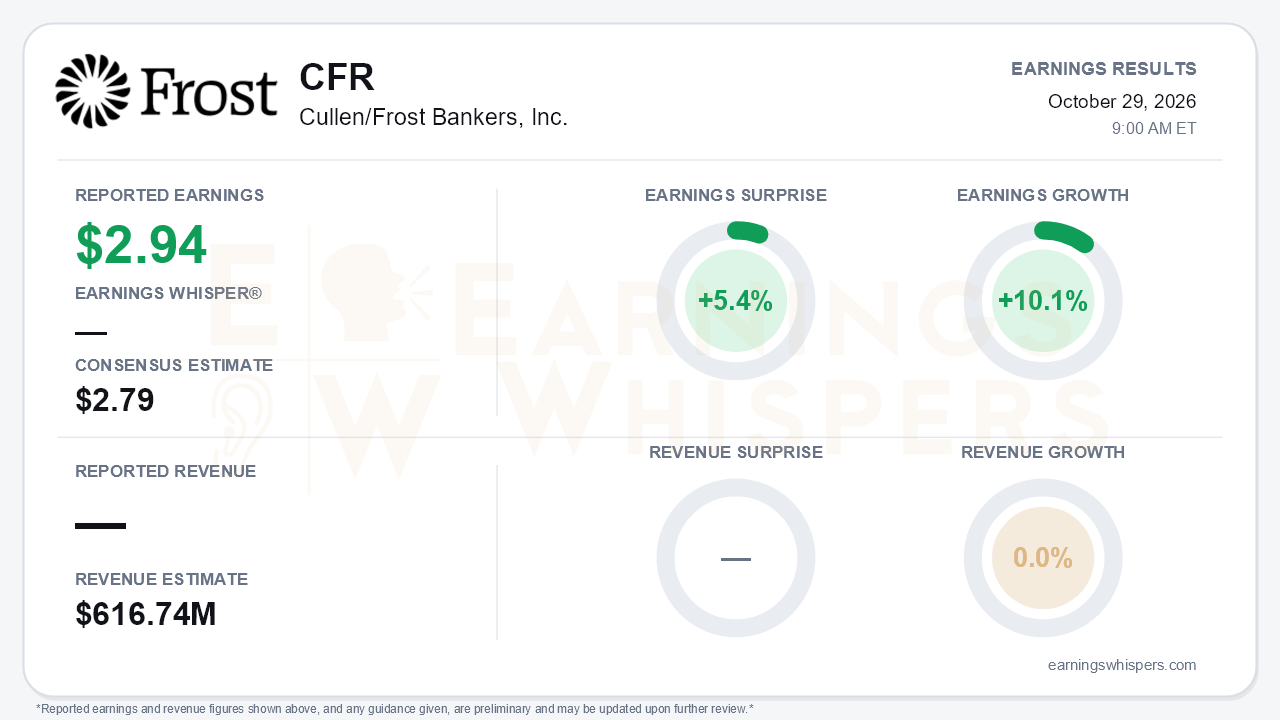
Cullen/Frost Bankers delivered another clean beat on its Texas organic-growth strategy. Earnings Whispers puts third-quarter EPS at $2.94, 5.4% above the $2.79 consensus and up 10.1% year over year. Management then raised full-year 2026 guidance for net interest income, loan growth and fee income for a second straight quarter. The central tension sits on the balance sheet, where the rate environment that is helping asset yields is also raising funding costs. It is widening unrealized securities losses and eroding tangible capital measures faster than earnings can rebuild them.
The comparison basis needs a caveat. The company's GAAP net income available to common shareholders was $178.5 million, or $2.84 per diluted share, against $2.67 a year ago. On that basis, the call analysis characterizes EPS growth as +6.4%, slower than the roughly 13% pace in the second quarter. The core earnings drivers are clearly healthy. Taxable-equivalent net interest income rose 5.8% to $490.8 million. Net interest margin expanded to 3.78% from 3.75% in Q2 and 3.69% a year earlier. Average loans grew 9.0% to $23.4 billion, including a 3.3% sequential gain. The beat still deserves some scrutiny:
- About $3 million of the margin benefit came from a non-accrual loan payoff, which flatters the run rate.
- Non-interest income included $7.6 million of gains on sales of excess bank properties. That gain was largely offset by $7.5 million of securities losses from a bond restructuring.
- Expenses rose 7.0%, outpacing net interest income growth. Salaries, advertising and cloud spending all moved higher.
The call preserved a credible growth story. The 90-day weighted commercial loan pipeline hit a record $2.5 billion, up 16% from the prior record of $2.17 billion set in Q2. Other demand indicators were also strong:
- New relationships topped 1,000 for a sixth straight quarter.
- Relationships sourced from M&A-disrupted competitors jumped 73% year over year, with a reported win rate near 80%.
- The mortgage book passed $1 billion, well ahead of the $850 million year-end target.
- Earnings accretion from the branch expansion program climbed to $0.22 per share from $0.16 in Q2. Fourteen openings are planned for 2027, up from 12 this year.
The guidance raises were meaningful, especially given where they started in Q1:
- Net interest income growth: now 5–5.5%, versus 3.5–5% in Q1.
- Average loan growth: now 8–8.5%, versus 6–7% in Q1.
- Fee income growth: now 8.5–9%, versus 4–5% in Q1.
Management also pointed to multi-year repricing tailwinds. About $275 million of fixed-rate loans will roll from roughly 5.25% to 7.25% in Q4, and more than $1 billion follows in 2027, alongside $2.7 billion of securities repricing over the same span.
Bears have legitimate ammunition on several fronts:
- **Deposit costs.** The cost of interest-bearing deposits rose 12 basis points to 1.73%, double the Q2 increase, and is guided to about 1.87% in Q4.
- **Rate sensitivity.** Total deposit beta is guided to 50–55%, above the prior cycle. The net interest income benefit per 25 basis-point hike was cut to $1.5–1.7 million per month from about $2 million.
- **Expenses.** Expense growth is now pinned at about 5%, the top of the range. 2027 is flagged somewhat above mid-single digits as wealth management hiring continues.
- **Capital.** The unrealized loss on available-for-sale securities widened to $2.0 billion from $1.15 billion. Book value per share fell to $61.70 from $72.04, and period-end equity to assets dropped to 7.29% from 8.58%. Regulatory capital remains strong, with CET1 at 13.76%, but buybacks slowed to $15 million from $90 million in Q2.
- **Credit.** Non-accrual loans fell to $63.7 million from $112.7 million after an Austin multifamily loan paid off at par. However, provision expense rose to $12.1 million, and management still flagged remaining 2022-vintage multifamily loans and about $290 million of homebuilder exposure.
The market setup is more complicated than the surprise implies. Shares closed at $157.01 the day before the report, down 7.1% from the open following the July release. That leaves the stock 8.1% below the $170.80 52-week high set in mid-August, though 7.9% above the early-October low of $145.56 and 5.7% above the 200-day moving average. In effect, the stock entered earnings having already priced in some of the rate-driven balance-sheet stress. Investor sentiment remained negative but improved modestly, from -0.23 to -0.18. That fits a market cautious on funding costs and capital rather than doubtful of the franchise. The Earnings Whispers trend readings are mixed, with momentum positive while sequential growth and AVWAP remain negative.
The bottom line is that Cullen/Frost's operating engine is accelerating: record pipelines, share gains from disrupted competitors and a second consecutive guidance raise. The open question is whether that growth can outrun rising deposit costs, elevated expense growth and the capital drag from a $2.0 billion securities loss. Investors focused on loan momentum and repricing tailwinds got what they needed. Those focused on book value and returns of capital have reason to wait for funding costs to stabilize.
Read our earnings preview for Cullen/Frost Bankers, Inc.: https://www.earningswhispers.com/article/CFR/21048
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 9 hours | |
| 9 hours | |
| Oct-21 | |
| Oct-21 | |
| Oct-08 | |
| Sep-14 | |
| Aug-31 | |
| Aug-18 | |
| Aug-03 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-09 |
