Leonardo DRS Faces A Credibility Test After Two Guidance Raises And A 27% Slide
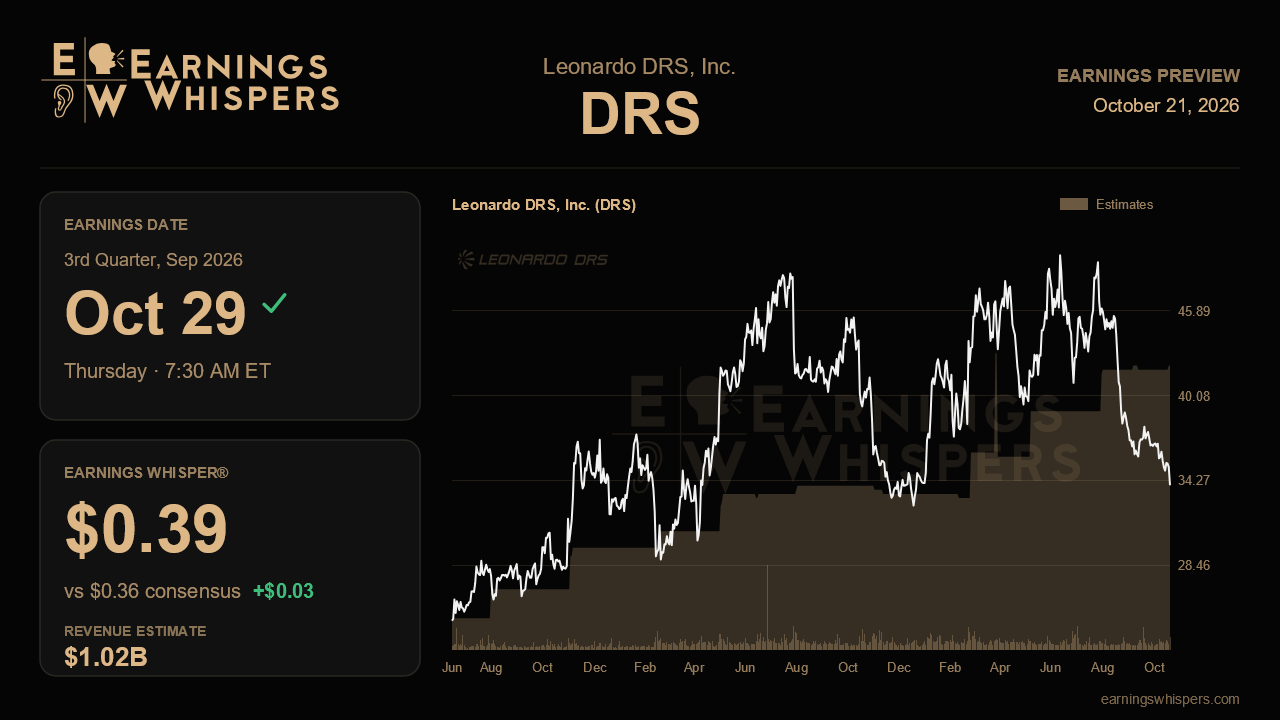
Leonardo DRS heads into its third-quarter report with an awkward mismatch. On the operating side, management has raised its full-year profit outlook twice, organic growth reaccelerated last quarter and orders keep outrunning sales. In the market, the stock has fallen 27.3% since that upbeat report while the S&P 500 gained 4.5%. When the company reports before the open on October 29, the results need to show whether the business story or the share price has the better read on what comes next.
The Street expects earnings of $0.36 a share on revenue of about $1.02 billion. That would be roughly 24% EPS growth from $0.29 a year ago on revenue growth of only about 6%, so most of the projected gain comes from margin expansion rather than volume. The Earnings Whisper sits at $0.39, a few cents above consensus, which suggests the more engaged crowd expects another modest beat. Management's latest guidance calls for 2026 EPS of $1.34 to $1.39, raised from $1.26 to $1.30, and revenue of $3.90 billion to $3.975 billion, which it left unchanged. The full-year consensus of $1.30 sits below even the low end of the raised range, so the published Street numbers appear not to have fully caught up with management. Revenue consensus of $3.94 billion lands near the middle of guidance.
The quarter carries a built-in margin step down, and investors should not mistake it for deterioration. Management guided third-quarter adjusted EBITDA margin to the mid-13% range because the second quarter benefited from a one-time gain when a program retired risk. A number in that area would be in line with plan. A clearly higher figure would suggest the underlying margin gains are larger than management has said. A slip toward 13% or below would raise doubts, because the core of the bull case is a company growing earnings much faster than sales.
Revenue conversion is the bigger question. Organic growth jumped to 10% last quarter from 6% in the first quarter, yet management kept the sales range flat and warned that backlog is turning into revenue more slowly as the mix shifts from components toward larger, more complex solutions. Consensus implies a solid sequential increase from $913 million, but year-over-year growth would slow to the mid-single digits. Investors need clear signs that the record funded backlog is reaching the income statement. That includes the accelerating order flow on the $533 million DAIRCM production contract, the 50,000-unit camera-core order from a low-cost drone maker, and early progress on over-the-horizon radar tied to homeland missile defense. Book-to-bill matters too. The company has posted 18 straight quarters at or above 1.0, and a 19th would ease concerns about a calendar fourth-quarter continuing resolution and unsettled fiscal 2027 appropriations, which management has called minimal headwinds.
The $450 million Raft acquisition adds a newer element. Management says the AI and mission-software business will be accretive in its first full year and has already been selected for the Army's next-generation command-and-control data layer. Any update on timing, integration costs or how Raft affects the 2026 outlook will show whether the deal strengthens the higher-margin software story or simply adds noise to the numbers.
Sentiment barely moved, at 19.9% bullish versus 18.8% a quarter ago, so the selloff has not turned the crowd sharply negative. The chart, however, looks bruised. Shares at $33.94 sit just above the post-earnings low of $33.57 and well below the 200-day moving average of $42.27. That leaves room for relief if results hold up, and little cushion if they do not. The central issue is whether management can reaffirm or nudge up profit guidance while showing that backlog is converting to revenue fast enough to justify keeping, and eventually raising, the sales outlook.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 | |
| Oct-12 | |
| Oct-05 | |
| Oct-05 | |
| Sep-29 | |
| Sep-17 | |
| Sep-14 | |
| Sep-10 | |
| Sep-01 | |
| Aug-11 |
