Leonardo DRS Posts Record Bookings And A Third Straight Raise, But A Tax-Aided Beat Meets A Stock That Lost A Quarter Of Its Value
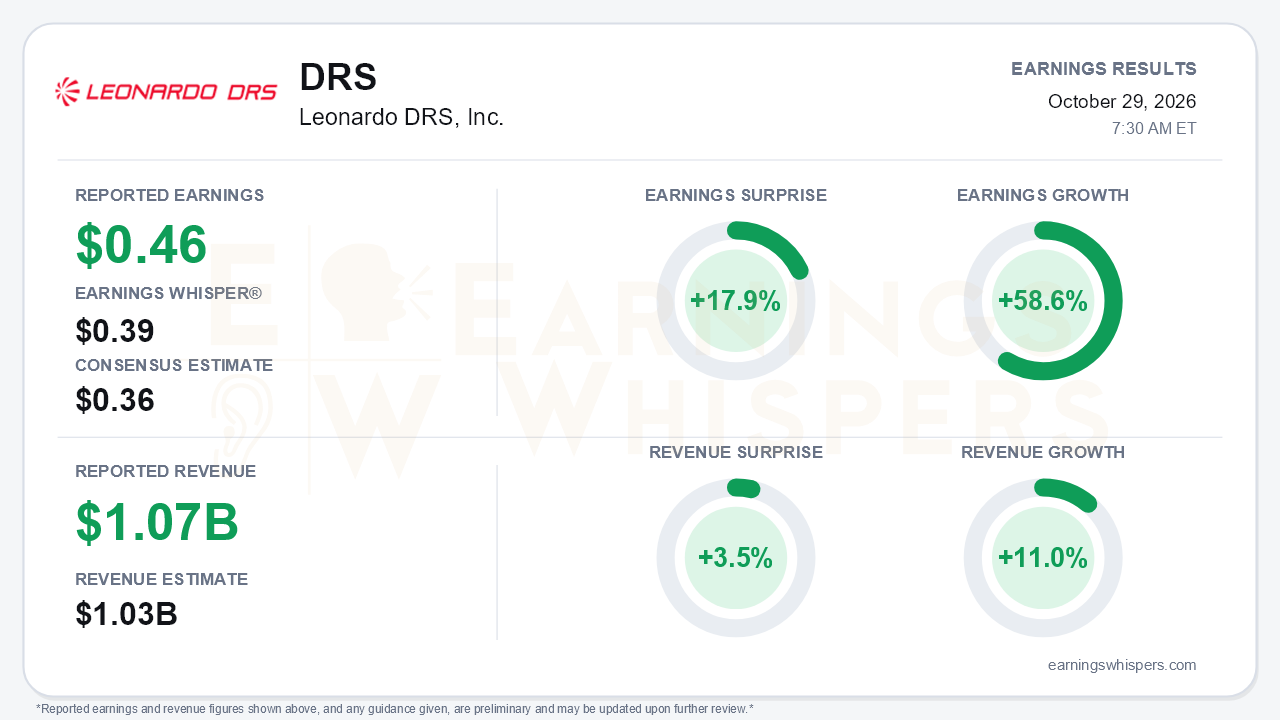
Leonardo DRS delivered the cleanest operating quarter of its four years as a public company, and the stock entered the report as if the opposite were true. Adjusted EPS of $0.46 beat the $0.36 consensus by 17.9% and topped the $0.39 Earnings Whisper. Earnings grew 58.6% year over year, revenue rose 11.0% to $1.066 billion and beat consensus by 3.5%, and bookings above $1.6 billion produced a 1.5x book-to-bill, the company's strongest since its debut. Management raised full-year guidance for the third consecutive quarter. Yet shares fell 24% between the open after the July report and the eve of this one. That gap between accelerating fundamentals and a deteriorating tape is the central tension.
The quality of the EPS beat deserves scrutiny. The operating story is real. Adjusted EBITDA rose 27% to $149 million, and margin expanded 180 basis points to 14.0%, ahead of the mid-13% management had framed. GAAP operating earnings climbed from $93 million to $116 million. But the income tax provision fell to just $1 million from $15 million a year ago, and that collapse did much of the work separating roughly 33% pre-tax earnings growth from 60% net earnings growth. The guidance raise carries the same fingerprint. The adjusted EPS range moved from $1.34–$1.39 to $1.50–$1.53, while the full-year tax assumption dropped from 16.5% to 13%. The EBITDA range rose a more modest amount, to $545–$555 million from $525–$540 million. Management also flagged that the fourth-quarter tax rate will normalize to about 19%. Investors should treat the EBITDA raise as the operational signal and the EPS raise as partly an accounting gift.
Beneath the headline, the trajectory is genuinely improving. Organic growth has stepped up from 6% in the first quarter to 10% in the second and 11% in the third. The revenue outlook has been lifted from an initial 6%–8% organic range to an implied 8%–9%. Integrated Mission Systems was the standout. Segment adjusted EBITDA margin jumped 280 basis points to 16.6% on naval power and propulsion strength, and management now frames roughly 16% as the baseline rather than the ~15% it cited in July. Advanced Sensing and Computing grew revenue 14% on tactical radars and space sensing, but its margin was flat sequentially. Management said further expansion there depends on mix.
The call added a meaningful list of growth catalysts:
- a roughly $500 million JIATF-401 counter-drone radar contract, which is not yet in backlog and already has deliveries flowing;
- selection for Korea's KDDX destroyer electric propulsion system, the company's first allied surface-combatant win;
- a role in the Army's counter-drone laser production program;
- finalist status in the APEX low-cost interceptor competition;
- the formation of DRS UK for licensed European radar production.
Record funded backlog of $5.6 billion, up 21%, supports the narrative. So does a preliminary 2027 framework of low double-digit growth, including 2–3 points from the pending Raft acquisition.
Bears still have legitimate ammunition. Management said 2027 margin expansion will be more muted than 2026, a retreat from an earlier framework that implied similar expansion. Third-quarter free cash flow of $61 million beat the 'modestly positive' guide but trailed the prior year's $77 million on working-capital needs. Full-year conversion remains at 75%, down from the 80% target set in February. Cash fell to $294 million from $647 million at year-end, largely from debt repayment, ahead of a Raft close and elevated fourth-quarter capex. Management described the continuing resolution through December 11 as immaterial.
The market setup is more complicated than the surprise implies. Investor sentiment slid from a modestly positive 0.19 to essentially neutral at -0.01. Expectations cooled even as guidance kept rising. The stock closed at $35.50 before the report, 15.8% below its 200-day moving average of $42.19 and 26.4% below the inter-earnings high of $48.21 set the day after the July report. It sat just 7.2% above the $33.12 low reached on October 23. Earnings Whispers trend readings are split. Sequential growth and momentum are positive, while price and AVWAP trends remain negative. That split is consistent with improving numbers that the market had not yet rewarded.
The bottom line is that DRS delivered on nearly every operating lever investors could ask for: accelerating organic growth, record orders and backlog, expanding margins and a credible 2027 growth outline. The EPS beat and raise were flattered by a sharply lower tax rate, and the margin story is set to slow next year, giving skeptics a reason to discount the headline. Still, the quarter answers more questions than it raises. For a stock that entered the print near its lows with sentiment flat, the fundamental story now looks considerably stronger than the price action leading into the report.
Read our earnings preview for Leonardo DRS, Inc.: https://www.earningswhispers.com/article/DRS/21061
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 12 hours | |
| Oct-21 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 | |
| Oct-12 | |
| Oct-05 | |
| Oct-05 | |
| Sep-29 | |
| Sep-17 | |
| Sep-14 | |
| Sep-10 |
