Cal Water's First Clean Quarter Under New California Rates Tests A Sliding Stock
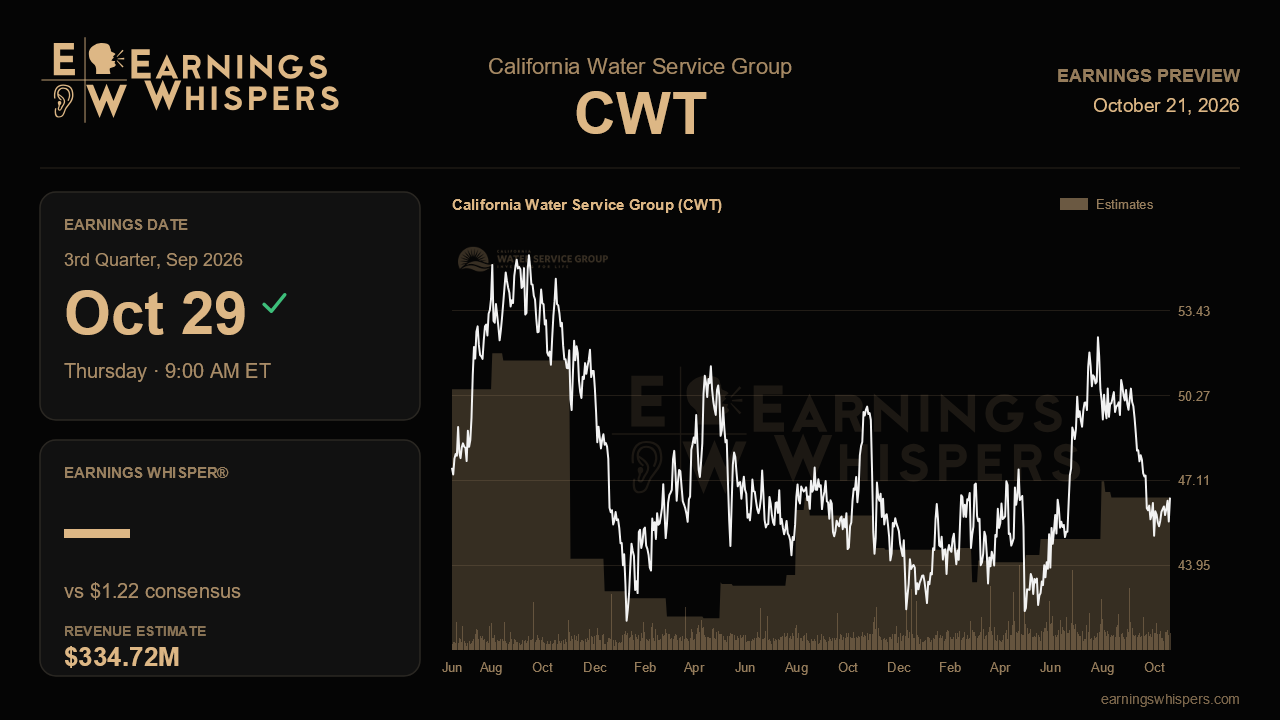
For the better part of a year, the story at California Water Service Group was about waiting. The company's 2024 California general rate case sat unresolved through three straight earnings calls, and the uncertainty hung over everything. Last quarter that changed: the decision was finalized, new rates hit customer bills on July 1, and management sounded more confident than it had in some time. Yet the stock has since dropped 13.2%, trailing the S&P 500 by nearly 18 percentage points. The third-quarter report, due before the open on October 29, is the first full period to show what the resolved rate case actually looks like in the numbers, and it arrives with the market plainly skeptical.
Wall Street expects earnings of $1.22 a share on revenue of $334.7 million. That would be an 18.5% jump from the $1.03 earned a year ago, on revenue growth of 7.6%. The gap between those two growth rates is the point. Earnings rising more than twice as fast as sales signals that analysts expect the new authorized rates to fall largely to the bottom line, with margins widening as the roughly $91 million in 2026 revenue increases flows through. The third quarter is also seasonally the company's strongest, since summer is when Californians use the most water, so it shows rate changes at their highest-volume moment.
The second quarter's $0.93 in EPS was flattered by a one-time catch-up. Because the rate decision was retroactive to January 1, the company booked $15.3 million in interim rate memorandum account revenue covering earlier months, alongside deferred revenue adjustment mechanism gains. Those catch-ups do not repeat. A result near consensus would confirm that the underlying run rate is genuinely higher, not just padded by a backlog of retroactive dollars. The quarter should also include revenue from the Washington rate settlement, which management said would be recognized in this period, a small but tangible addition.
The quality of the beat or miss matters as much as the headline figure. The new California sales adjustment mechanism is designed to recover part of the company's fixed costs when usage falls short, which should dampen the weather swings that hurt results in late 2025. Evidence that this mechanism is working as intended would be a meaningful validation of the regulatory upgrade. Conversely, the company flagged $6.3 million in higher water supply costs last quarter, and rising electricity prices feed directly into production expenses. If supply and power costs outrun the new rates, the margin expansion embedded in consensus could prove too optimistic.
Beyond the quarter, the investment case rests on capital deployment. Management spent a record $276 million in the first half and is targeting roughly 12% annual rate-base growth toward about $3.5 billion by 2028. Continued spending at that pace, an update affirming the Nexus Water acquisition in Nevada and Oregon remains on track for a year-end close, and further progress on PFAS recoveries from polluters, which have climbed to around $60 million, would all reinforce the growth narrative. Commentary on the California cost-of-capital timeline and on affordability pushback deserves attention, since those are the risks management itself elevated.
Sentiment has soured, with bearishness more than doubling from the prior quarter, and the shares sit right at their 200-day moving average near the bottom of a range running from about $45 to almost $54. That leaves the stock with little cushion if results disappoint but meaningful room to recover if they do not. The central question is simple: does the first clean quarter under the new California rates show durable earnings power, free of retroactive help? If it does, the selloff since the last report looks like an overreaction to macro noise rather than a verdict on the business.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 9 hours | |
| Oct-15 | |
| Oct-15 | |
| Oct-08 | |
| Sep-30 | |
| Sep-10 | |
| Sep-08 | |
| Sep-01 | |
| Aug-31 | |
| Aug-19 | |
| Aug-17 | |
| Aug-10 | |
| Aug-10 | |
| Aug-03 | |
| Jul-30 |
