California Water Service Misses By 13.9% As Below-The-Line Costs And Dilution Mute Rate-Base Growth
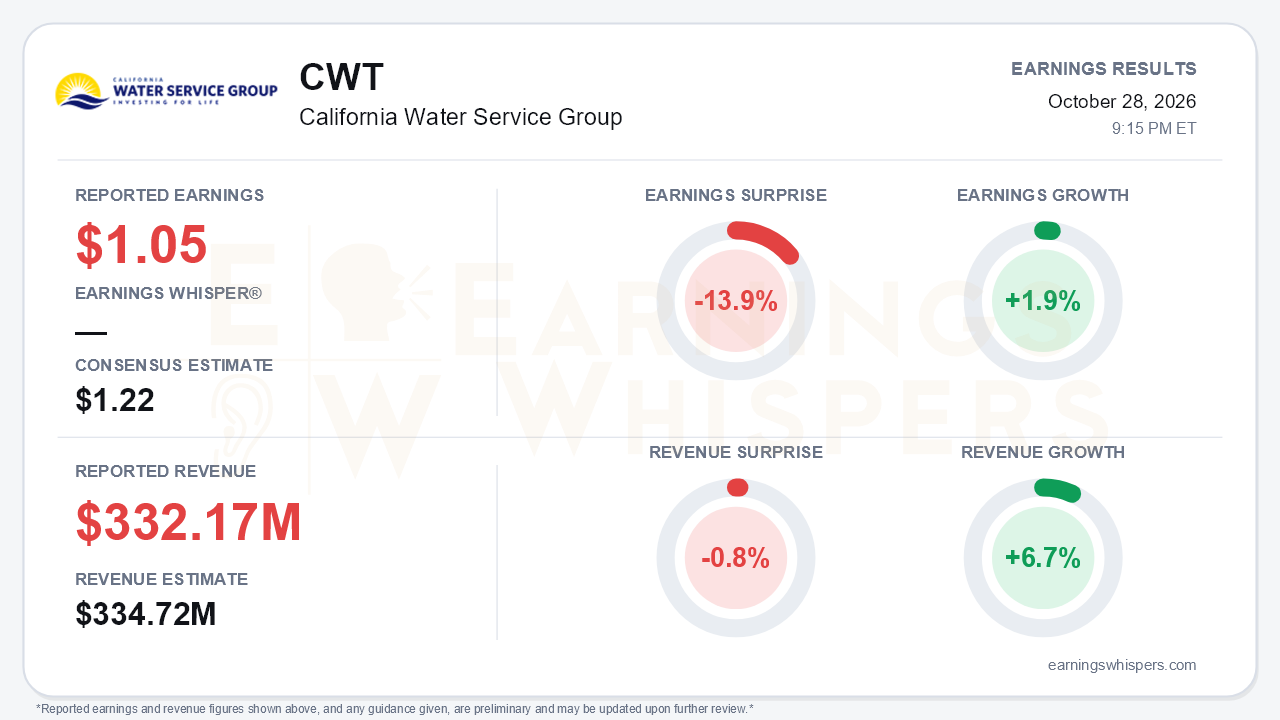
California Water Service Group (NYSE: CWT) reported third-quarter earnings of $1.05 per share, missing the $1.22 consensus by 13.9%. Revenue of $332.17 million rose 6.7% year over year but fell 0.8% short of the $334.72 million consensus. Management called the results "solid" and "strong," but the gap between 6.7% revenue growth and just 1.9% earnings growth is the central tension. The regulated utility engine is working. Almost nothing below the operating line is helping it reach shareholders on a per-share basis.
The quality of the miss deserves scrutiny, because the operating results were not the problem. Net operating income rose to $82.7 million from $70.6 million, helped by $22.1 million from rate changes and new customers and $3.9 million from the drought memorandum account. Water production costs were flat. The erosion came further down the income statement:
- Net other income fell $6.0 million, driven by a $3.9 million drop in non-qualified benefit plan investment gains and $1.4 million of higher acquisition expenses.
- Interest expense climbed to $20.2 million from $18.1 million.
- Income tax expense on operating income rose $7.1 million, partly because of a scheduled reduction in the TCJA refund.
- Diluted shares rose to 62.5 million from 59.7 million after continued at-the-market issuance, including $49.8 million in the quarter.
Net income attributable to the company grew from $61.2 million to $65.4 million, a respectable gain. Dilution then compressed that into a two-cent EPS improvement. Revenue growth also cooled from the 9.6% year-to-date pace. That earlier pace was flattered by one-time catch-up items: $15.7 million from the interim rates account tied to the delayed California GRC and $9.9 million of legacy WRAM revenue. Lower customer usage cost another $4.4 million in the quarter, while conservation program spending rose $2.8 million.
The call preserved a credible long-term growth story. Management described the quarter as one of execution and de-risking:
- **Capital spending:** Year-to-date capex reached a record $424.8 million against a $627 million 2026 plan.
- **Step increase:** Management expects to capture a "big chunk" of the roughly $49 million in 2027 California step increases it plans to file around November 15.
- **Rate base and return:** The roughly 12% rate base growth outlook to about $3.5 billion by 2028 was reaffirmed. The 10.27% authorized ROE remains locked through 2027 after the cost-of-capital mechanism was not triggered.
- **Rate cases:** Washington approved a $4.1 million increase, Hawaii approved $1.94 million for Kapalua, and the Texas BVRT rate case was placed on the November 5 commission agenda.
- **PFAS:** The CPUC opened an advice-letter path to recover roughly $113 million of PFAS capital. Net PFAS litigation recoveries climbed to $59.4 million, from about $40 million at year-end 2025.
- **Dividend:** Management formalized a 7% annual growth floor and a 50-60% payout target.
Bears still have legitimate ammunition, and much of it points to the next few quarters rather than the next few years. Inflation became a new emphasis on the call. Fuel costs across roughly 1,000 vehicles are up 20-30%, materials costs are higher, and the CEO said the company is "not through the worst of it yet." Nexus integration costs of $7-9 million are borne by shareholders and will weigh on non-regulated results into the first quarter of 2027. New financing locks in coupons of 6.08% to 6.54% on $275 million of notes and bonds, and $77.8 million of equity forwards remain to be settled, so both interest costs and dilution have more room to grow. Fourth-quarter capex is back-end loaded, and management flagged that a strong El Niño winter could push spending into 2027.
The market setup reflects that near-term skepticism. Earnings Whispers investor sentiment slid from -0.10 to -0.29, a meaningful move deeper into negative territory. Shares closed at $47.15, down 12.0% from the $53.56 open after the July report. That decline came after the stock set a 52-week high of $53.82 the day after that report. The shares then fell to a $45.05 low on September 29 and now sit just 1.2% above the 200-day moving average of $46.60. The trend readings are mixed: momentum is positive while AVWAP remains negative. That fits a stock that has stabilized off its lows without regaining its post-July footing.
The bottom line is that CWT's quarter combined clean regulatory execution with a disappointing per-share outcome. Rate relief, record capex, secured financing and two Nexus approvals strengthen the multi-year rate-base thesis. However, rising taxes, interest costs, integration expenses, weaker usage and ongoing equity issuance are absorbing much of that growth before it reaches EPS. Until the 2027 step increase and acquisitions begin outrunning dilution and inflation, investors are likely to keep weighing the durable regulated story against a stubborn near-term earnings drag.
Read our earnings preview for California Water Service Group: https://www.earningswhispers.com/article/CWT/21056
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-21 | |
| Oct-15 | |
| Oct-15 | |
| Oct-08 | |
| Sep-30 | |
| Sep-10 | |
| Sep-08 | |
| Sep-01 | |
| Aug-31 | |
| Aug-19 | |
| Aug-17 |
