Cognizant's 30% Rally Raises The Stakes For Bookings After A Revenue Guidance Cut
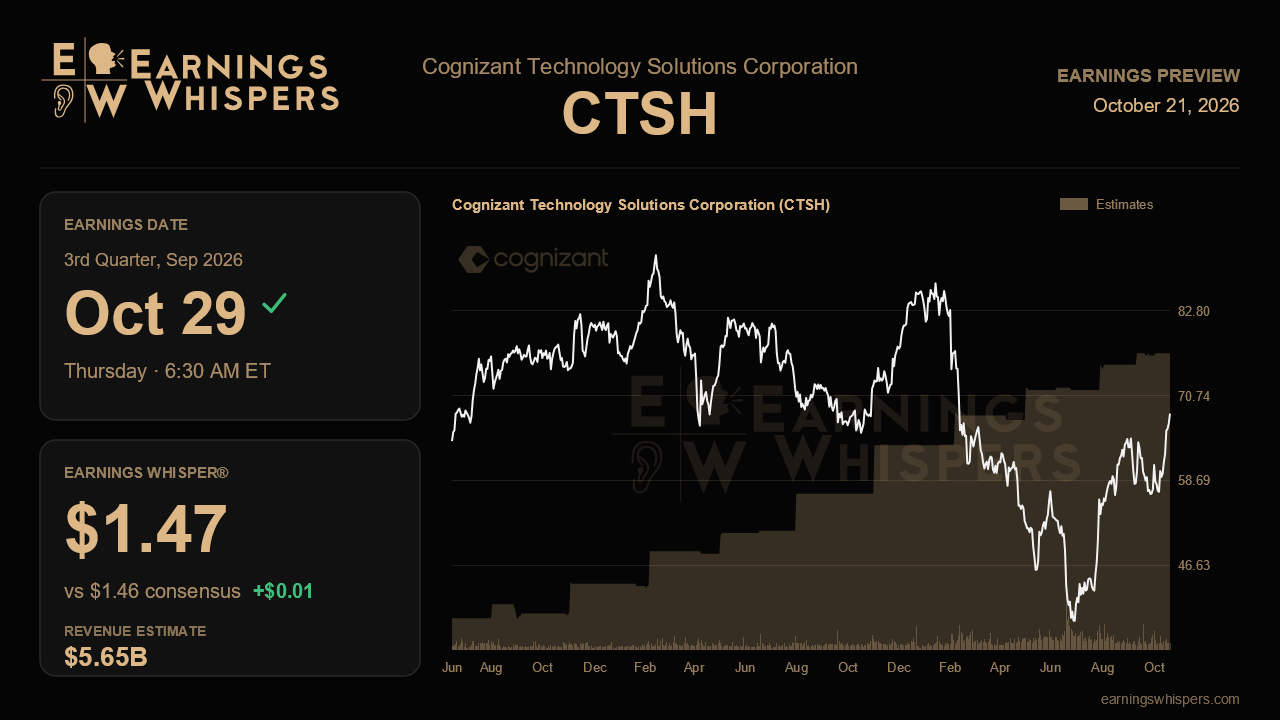
Three months ago, Cognizant gave investors a split verdict: it raised its full-year earnings outlook while trimming the top of its revenue range, conceding that the discretionary spending rebound it had counted on never showed up. The market has since chosen to focus on the good half of that message. Shares have climbed about 30% since the last report, beating the S&P 500 by more than 26 percentage points. That shifts the burden of proof for the third-quarter release, due before the open on October 29. The stock is now priced for a company whose demand is stabilizing, not one that just lowered its sales ambitions.
The near-term numbers look achievable. Analysts expect earnings of $1.46 a share on revenue of $5.65 billion, up roughly 5% and 4.3% from a year ago. That is steady, unspectacular growth, and it fits management's third-quarter revenue range of $5.60 billion to $5.68 billion, slightly above the midpoint. The Street's revenue estimate has drifted down from about $5.70 billion when guidance was issued, which means analysts have already moved into the company's framework rather than ahead of it. The whisper number of $1.47 is a penny above consensus, too small to signal a meaningfully higher bar. For the full year, Cognizant expects adjusted EPS of $5.70 to $5.82 on revenue of $22.04 billion to $22.35 billion. At the time of the update, consensus sat at the bottom of the EPS range and near the top of the revenue range. That mismatch suggests some skepticism about margins and some optimism about sales.
Margins have been the company's most reliable story. The second quarter marked a sixth straight year-over-year gain in adjusted operating margin, reaching 16%. Another expansion would support the raised EPS outlook, especially with interest costs rising after a $1 billion revolver draw that funded the Astria acquisition and buybacks. Financial services is the growth engine to track. That vertical accelerated from 9% constant-currency growth to roughly 12% over three quarters, and management called it a leading indicator for the rest of the portfolio. Holding at that pace, or showing early improvement in health sciences, communications and media, or products and resources, would support that claim. If financial services cools while the other verticals stay soft, the argument that recovery is spreading loses its main exhibit.
Bookings are the bigger swing factor. Trailing twelve-month bookings growth slowed to 5% in the second quarter from 21% the quarter before. Large-deal signings came in at seven, and annual contract value dipped again because of longer-duration deals. A rebound in deal flow would tell investors the second-quarter slowdown was a matter of timing. Another weak bookings print would raise questions about 2027 just as the stock prices in better days. Public-sector wins such as the HMRC contract worth more than $250 million help, but they cannot replace broad commercial demand. Free cash flow also needs to improve after a soft $652 million through the first half.
The AI story will color how investors read everything else. AI engagements topped 8,000, more than 40% of software development is now AI-assisted, and the company has deepened its ties with Anthropic, OpenAI and Google while launching its AI Delivery Operating System. The open question is whether that activity turns into revenue or simply replaces older, labor-heavy work. Management itself noted that many enterprises are pausing AI deployments or not yet seeing measurable gains.
Sentiment has swung from mildly bearish before the last report to solidly bullish now. The stock trades about 14% above its 200-day moving average and within 1% of its post-earnings high of $68.75, so it is testing a breakout. That leaves little room for a merely adequate quarter. Hitting the EPS target looks likely given the margin momentum. The real test is whether bookings and vertical breadth show that the guidance cut marked a low point. If they do, the rally has a foundation. If they don't, investors may conclude the stock got ahead of the demand it actually has.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 1 hour | |
| 8 hours | |
| Oct-20 | |
| Oct-19 | |
| Oct-16 | |
| Oct-13 | |
| Oct-12 | |
| Oct-11 | |
| Oct-10 | |
| Oct-09 | |
| Oct-09 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 |
