Cognizant Edges Past Estimates And Posts Record Margins, But A Second Guidance Cut Exposes A Thinning Organic Growth Engine
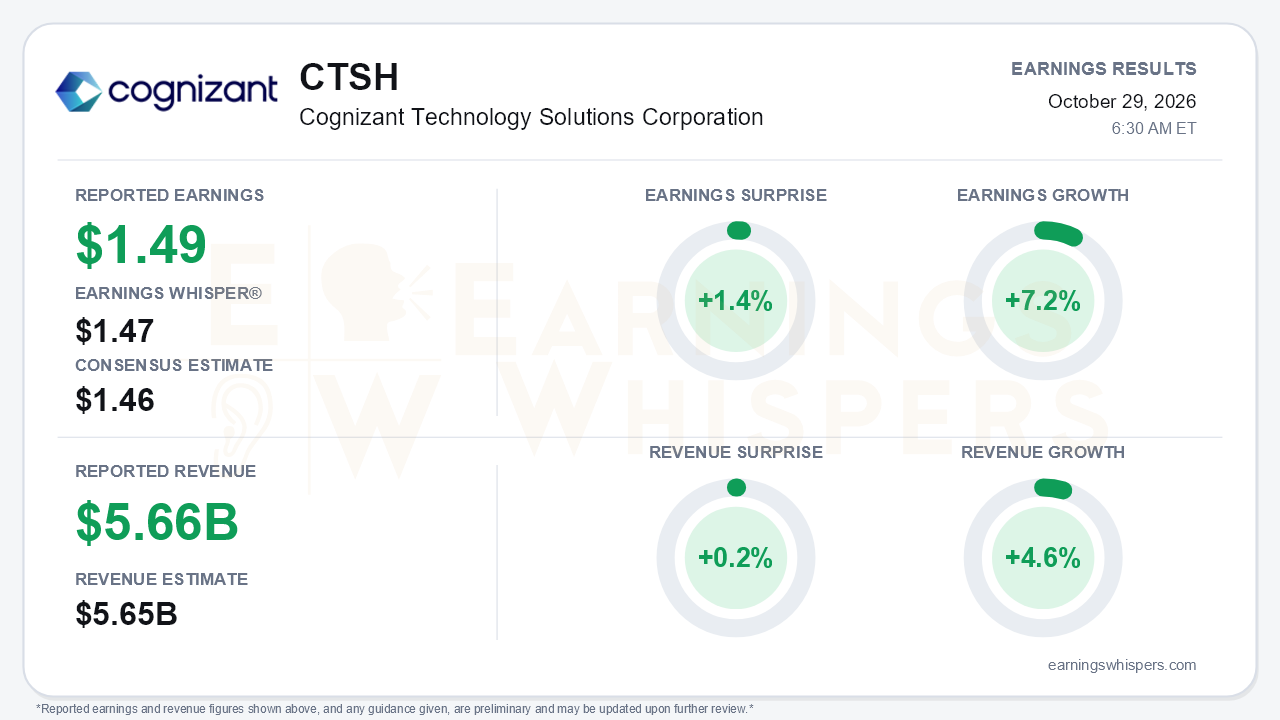
Cognizant cleared expectations in the third quarter, though not by much, and the forward commentary carried more weight than the beat. Adjusted EPS of $1.49 topped the $1.46 consensus and the $1.47 Earnings Whisper number by 1.4% and rose 7.2% year over year. Revenue of $5.664 billion edged past the $5.65 billion consensus by 0.2% and grew 4.6% (4.8% in constant currency). On the surface, top-line growth accelerated for a third straight quarter, from 3.9% in Q1 to 4.1% in Q2 to 4.8% now. That is the central tension. The quarter looked better than the business underneath it, and management cut the top end of full-year revenue guidance for the second consecutive quarter. The new Q4 outlook implies organic growth slowing to roughly 2% by year-end.
The quality of the beat deserves scrutiny. Recent acquisitions, primarily 3Cloud and Astria, added about 210 basis points to Q3 growth. Low-margin resale of third-party products under the integrated-offerings strategy added another 190 basis points. Together those two sources account for most of the reported 4.6%. The segment picture is lopsided. Financial Services grew 12.3% in constant currency, its third straight double-digit quarter, and Communications, Media and Technology grew 10.7%. In CMT, however, acquisition (875 basis points) and resale (600 basis points) contributions exceeded the segment's entire reported growth. Health Sciences slipped 0.9% and Products and Resources fell 0.8%. On earnings, adjusted net income of $670 million was actually slightly below last year's $675 million. The 7.2% per-share gain came from a diluted share count that fell to 450 million from 487 million. GAAP EPS of $1.39 versus $0.56 is flattering only because last year's quarter absorbed a $390 million one-time tax charge. GAAP operating margin fell 60 basis points to 15.4% on $51 million of Project Leap restructuring costs.
Where Cognizant genuinely delivered was profitability. Adjusted operating margin reached 16.3%, up 30 basis points year over year. That marks the seventh consecutive quarter of expansion and the highest level in four years. Management narrowed full-year margin guidance to about 16.1%, trimmed the tax-rate outlook to roughly 25%, and lowered the expected Project Leap cost to $180 million to $250 million from $230 million to $320 million, crediting reskilling and redeployment. The AI story also gained substance:
- More than 50% of code is now AI-assisted, up from about 40% last quarter.
- AI engagements rose to 8,500 from 8,000.
- New and expansion work climbed to roughly 60% of bookings.
- AI-tailwind service lines, about 40% of the business, are growing at two to three times the organic rate.
The demand side is where bears have legitimate ammunition. Full-year constant-currency revenue guidance is now 4.0% to 4.4%, down from 4% to 5.5% in Q2 and 4% to 6.5% in February. Q4 guidance of 3.2% to 4.7% constant-currency growth sits below what the Street expected. Management cited three pressures:
- macro uncertainty weighing on discretionary spending in healthcare and consumer-facing sectors;
- Medicaid and Medicare regulatory uncertainty;
- heavier Q4 furloughs than assumed, plus lower resale contribution.
Bookings fell 7% in the quarter. Trailing 12-month bookings growth decelerated to 4%, from 5% in Q2 and 11% in Q1, with only three large deals versus seven in each of the prior two quarters, and annual contract value declined modestly. Project Leap savings landed at about $200 million, the low end of the prior $200 million to $300 million range. Cash quality also softened. Q3 free cash flow of $925 million rebounded from Q2 but trailed last year's $1.16 billion, and DSO rose five days to 89. Long-term debt has tripled to $1.55 billion since year-end after acquisitions and $1.9 billion of year-to-date buybacks.
The market setup is more complicated than the surprise implies. Investor sentiment swung meaningfully from slightly negative (-0.06) after the July report to moderately positive (0.23) heading into this one. Shares rallied 26.9% from the post-July open of $52.31 to $66.36, trading nearly 12% above the 200-day moving average. Price, sequential-growth and AVWAP trend readings were positive. Yet the stock had already retreated about 10% from its October 22 inter-earnings high of $73.92 before the release, suggesting some of the enthusiasm had begun to fade. Investors arriving with improved expectations now face a guidance cut and a decelerating organic exit rate, not the acceleration the headline growth figure suggested.
The bottom line is that Cognizant is executing well on what it controls: margins, cost programs, capital return and AI delivery capability. The revenue engine underneath is weakening. Acquisitions, third-party resale and buybacks are carrying much of the headline growth, while bookings momentum and the Q4 outlook point to roughly 2% organic growth. Until Financial Services strength broadens and bookings reaccelerate, the record margin is the quarter's strongest feature, not proof that demand has turned.
Read our earnings preview for Cognizant Technology Solutions Corporation: https://www.earningswhispers.com/article/CTSH/21055
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 5 hours | |
| 6 hours | |
| 6 hours | |
| 7 hours | |
| 8 hours | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-19 |
