Enterprise Products Must Prove Fee Growth Can Replace Fading Hormuz Windfall
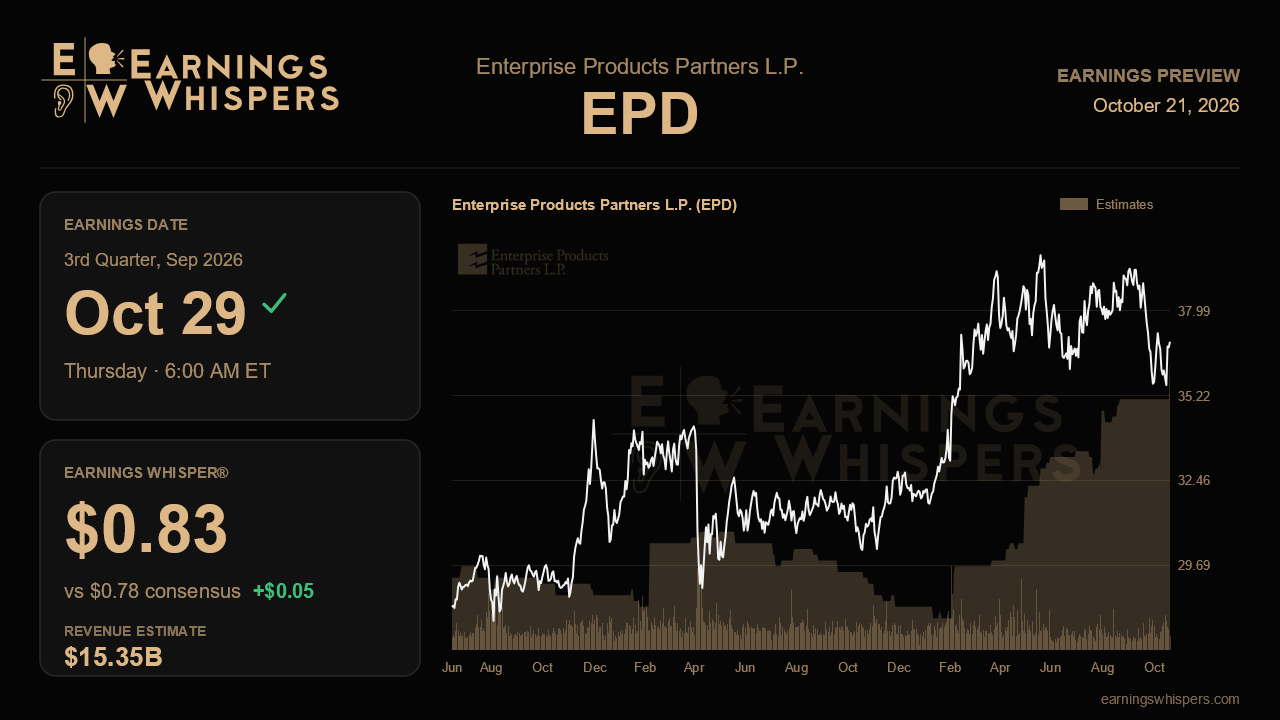
Enterprise Products Partners heads into its third-quarter report with a question that its record second quarter could not answer: how much of that strength was the durable, fee-based machine, and how much was a one-time gift from a disrupted Strait of Hormuz? Management said roughly $200 million of spread capture tied to the Iran conflict had largely normalized by the time it spoke in the summer. That makes the coming release, due before the open on October 29, the first clean look at the partnership's earnings power without that tailwind.
Wall Street expects earnings of $0.78 per unit on revenue of about $15.35 billion. Both figures imply growth of roughly 28% from the year-ago quarter, when Enterprise earned $0.61 on $12.02 billion in revenue. That is a strong comparison, helped by a soft prior-year base, when EBITDA was about $2.4 billion. The more telling comparison is sequential. Consensus sits below last quarter's $0.84, so analysts are already pricing in the loss of the windfall. The Earnings Whisper of $0.83 is meaningfully above consensus, which suggests the informal bar is closer to a repeat of the second quarter than the published estimates imply. The revenue estimate also sits well below last quarter's $18.27 billion. That gap likely reflects commodity prices more than activity, since revenue for a midstream marketer moves with the barrels it resells.
The call laid out a clear set of claims to test. Permian processing inlet volumes rose 14% from a year earlier and marine terminal volumes jumped 33%. Those rates should not fully persist, but solid volume growth on a higher base would confirm that the core engine is still expanding. The weak spot is LPG exports. Management now expects lower spot lifting rates and less fee volatility over the next 12 to 18 months as more than 300,000 barrels a day of new industry export capacity is absorbed. That is a notable retreat from the optimism voiced earlier in the year. Commentary on contracted versus spot dock utilization, and on whether the EHT expansion is filling as planned at roughly 90% contracted, will show how much margin pressure is real. Waha basis is another swing factor, since about 2 Bcf/d of curtailed Permian gas returning could tighten the spreads Enterprise has profited from. Reliability at PDH-2, which went down in July, also bears watching in the petrochemical segment.
Capital spending deserves equal attention. Management raised 2026 net growth capex three straight quarters, to $2.9 billion to $3.4 billion, and pushed 2027 to around $3 billion, about 80% committed. It also hinted that $3 billion may be the new normal rather than the old $2 billion to $2.5 billion mid-cycle range. Investors will want to know whether discretionary free cash flow is still approaching $1 billion. They will also look at whether leverage holds at the 3.0x target and whether the distribution keeps rising from 56 cents. Any further capex increase without matching EBITDA guidance would challenge the case that growth spending is self-funding. Updates on CEO succession following Jim Teague's retirement announcement will add color but should not change the numbers.
The market has not been generous. Units have fallen 5.7% since the last report while the S&P 500 gained 4.5%, and at $36.98 they sit just below the 200-day moving average, toward the lower half of the post-earnings range of $35.37 to $39.69. Sentiment has improved modestly, to 13.7% bullish from 7.3%, but remains lukewarm. That leaves room for relief if the fee-based business shows it can stand on its own.
In the end, the report turns on whether EBITDA holds near the $2.7 billion to $2.8 billion run rate once spread gains are gone. If it does, the reaffirmed 10% annual EBITDA growth framework through 2027 looks credible, and the heavier backlog looks like an asset. If it falls back toward older levels, investors may conclude the record quarter flattered a business now spending more to grow.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 9 hours | |
| Oct-16 | |
| Oct-15 | |
| Oct-12 | |
| Oct-12 | |
| Oct-08 | |
| Oct-05 | |
| Aug-26 | |
| Aug-26 | |
| Aug-18 | |
| Aug-10 | |
| Aug-10 | |
| Jul-31 | |
| Jul-31 | |
| Jul-30 |
