Enterprise Products Edges Consensus But Misses The Whisper As Record Volumes Meet A Cooler 2027 Outlook
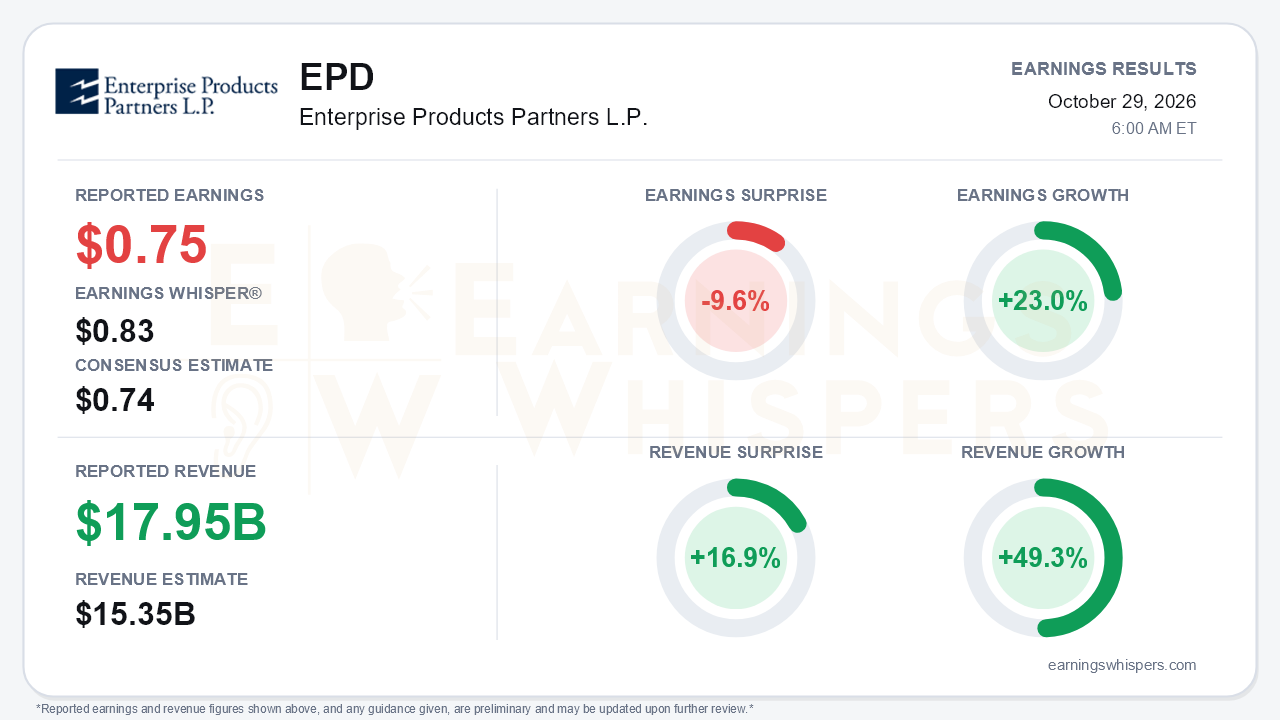
Enterprise Products Partners delivered third-quarter earnings of $0.75 per unit, a penny above the $0.74 consensus but well short of the $0.83 Earnings Whisper number, a 9.6% miss against the expectation that mattered most to engaged investors. Revenue of $17.948 billion beat the $15.35 billion consensus by 16.9% and grew 49.3% year over year. Earnings grew 23.0%. The central tension is that the partnership's long-term volume story has rarely looked stronger, yet management signaled that 2026's outsized growth will be hard to repeat in 2027. The whisper miss suggests investors were already pricing in more of this year's strength than the quarter delivered.
The revenue beat should be read cautiously. Enterprise notes that marketing revenue rises with commodity prices without necessarily lifting margin, and WTI averaged $85.79 versus $64.93 a year ago. The better measure is total gross operating margin, which rose 15% to $2.7 billion. Adjusted EBITDA increased 16% to $2.8 billion, essentially matching the second quarter's record pace of about 17% and well above the 10% gain in the first quarter. Growth held steady at an elevated level rather than accelerating further. Operational DCF jumped 27% to $2.3 billion, covering the distribution 1.9 times. That figure was helped by a $100 million collection of receivables tied to income recognized in a prior period, so the underlying cash-flow gain was strong but somewhat smaller than the headline. Mark-to-market swings contributed only $21 million to the margin improvement, a minor factor. Unitholders received a distribution of $0.56, up 2.8%, along with $112 million of buybacks.
The operating detail was broadly healthy. Permian processing inlet volumes hit a record 4.6 Bcf/d, up 12% and up from 4.3 Bcf/d in the second quarter. Total processing inlet volumes reached a record 8.5 Bcf/d, and equivalent pipeline volumes set a record at 14.8 MMBPD. New assets did much of the work:
- Frac 14 lifted fractionation margin to $262 million from $203 million.
- The second phase of the Neches River terminal raised ethane and LPG export volumes.
- The eleventh Delaware Basin processing plant and the Bahia NGL pipeline added capacity.
The softer parts of the quarter were more commodity- and spread-sensitive. NGL marketing margin rose $75 million on higher sales margins, and natural gas marketing added $31 million. Crude oil margin slipped to $367 million on higher operating costs. Marine terminal volumes rose 28% year over year to 2.5 MMBPD but fell from 2.8 MMBPD in the second quarter.
The call kept the long-term growth story intact. Management raised its 2025-2030 Permian wet gas and NGL production growth forecast to 34% from 23% in April and said risks skew higher. It cited rising gas-to-oil ratios and gassier Delaware benches. Plant construction is moving toward two processing plants per year, and more fractionators beyond Frac 15 look likely. Near-term catalysts include:
- the fully contracted 300 MBPD LPG export expansion, which lifts Houston Ship Channel capacity to about 1.1 MMBPD and begins commissioning this quarter;
- the Athena plant in the Midland Basin, also due in the fourth quarter;
- the Bahia expansion beginning in late 2027.
Leverage fell to 2.9x from 3.3x at the end of last year, giving the partnership room for bolt-on deals. The trade-off is heavier spending. Net 2026 growth capital is held at $2.9 billion to $3.4 billion, and 2027 capital is now about $3 billion versus the earlier $2 billion to $2.5 billion range.
Bears have legitimate ammunition. Management now describes 2027 EBITDA growth as "more modest" than 2026, softening the roughly 10% framing it had used through the second quarter. Part of this year's surge came from geopolitical spreads, roughly $200 million in the second quarter alone, which have largely normalized. Several smaller risks add friction:
- ATEX recontracting will reflect weaker current economics, although it represents less than 3% of EBITDA.
- Fractionation lead times have stretched about six months.
- The Bahia expansion depends on permanent power.
- Industry-wide LPG export overbuilding could pressure spot terminal fees.
- Co-CEO Jim Teague is retiring, and Randy Fowler becomes sole CEO in January.
Investor sentiment slipped from mildly positive at 0.07 to slightly negative at -0.03 heading into the report. That is a modest shift, but a cooler one. Units traded at $38.06 before the release, down 3.0% from the open after the prior report and about 4% below the September 10 inter-earnings high of $39.69. They had recovered 7.6% off the October 1 low and sat 2.3% above the 200-day moving average. The Earnings Whispers trend signals for sequential growth, momentum and AVWAP are positive, while price trend is neutral, consistent with a stock that has held up without breaking out.
The bottom line is that Enterprise produced a high-quality quarter built on record volumes, new assets and steadily falling leverage. However, the whisper miss and the softer 2027 framing shift attention from how strong 2026 has been to how much of it was borrowed from unusual market conditions. The raised Permian outlook and the coming LPG and processing start-ups preserve a credible multi-year growth story. The near-term debate now centers on whether volume growth can offset fading spreads and heavier capital spending.
Read our earnings preview for Enterprise Products Partners L.P.: https://www.earningswhispers.com/article/EPD/21066
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 8 hours | |
| 8 hours | |
| Oct-27 | |
| Oct-21 | |
| Oct-16 | |
| Oct-15 | |
| Oct-12 | |
| Oct-12 | |
| Oct-08 | |
| Oct-05 | |
| Aug-26 | |
| Aug-26 | |
| Aug-18 | |
| Aug-10 |
