TechnipFMC Must Prove Subsea Margin Breakout Holds As Stock Lags Despite Raised Guidance
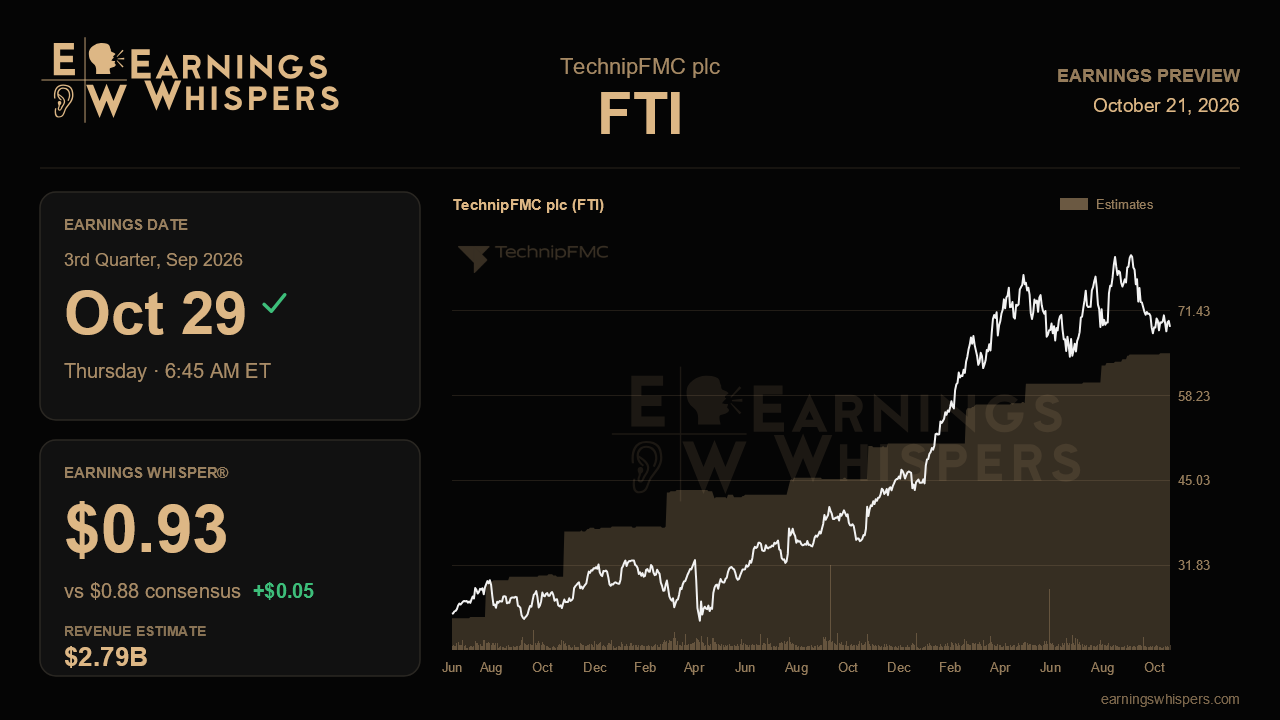
TechnipFMC heads into its third-quarter report with an unusual disconnect. Last quarter, management raised full-year EBITDA guidance, pushed its free cash flow outlook to the top of the range and delivered its best subsea margin since the demerger. Yet the stock has slipped 3.6% since then while the S&P 500 gained 4.5%. The October 29 release, due before the open, is the first real test of whether the second-quarter step-up was a new baseline or a high-water mark.
The Street expects earnings of $0.88 a share on revenue of $2.79 billion. That would be a 17.3% increase in profit from a year ago against only 5.4% revenue growth, which is the margin-expansion story in a single comparison. Notably, the consensus sits below the $0.91 the company earned last quarter, so analysts are effectively modeling a modest sequential pullback in profitability even as revenue edges higher. The whisper number of $0.93 suggests some investors expect TechnipFMC to at least match its second-quarter run rate. On the top line, management's reaffirmed 2026 revenue range of $10.35 billion to $10.90 billion has a midpoint almost exactly at the $10.64 billion consensus, so the Street is not leaning on the company to stretch.
The more important numbers sit beneath revenue. Management lifted its full-year adjusted EBITDA outlook to about $2.19 billion from a previous framing of more than $2.1 billion, and said subsea revenue and margins should land near the top of their ranges. Subsea EBITDA margin climbed to 23.2% in the second quarter, up from 20% in the first quarter and 18.9% in the fourth quarter of last year. A third-quarter subsea margin in the low 20s or better would validate the raised guide and suggest operating leverage on better-priced backlog is durable. A slide back toward 20% would raise doubts about whether the second quarter benefited from favorable project timing, particularly since management flagged softer activity in Africa and the US Gulf.
Orders are the second pillar. TechnipFMC reiterated a $10 billion subsea inbound target for 2026 and pointed to a strengthening second half, after booking $2.5 billion in the second quarter with a book-to-bill above one. Hitting that target implies a solid third and fourth quarter, so a light inbound figure now would put pressure on the year. Investors should also look for progress on the newer catalysts: the VarEnergi and Equinor tieback portfolio awards, the global collaboration agreement that brings the company into projects a year earlier, and early traction for the IEPCI 2.0 concept. The caveat management offered is that 2026 orders lean toward many smaller awards, with larger greenfield projects slipping to 2027, and that some opportunities remain slow to reach final investment decision. Any commentary affirming the promised 2027 step-up in inbound, revenue and margins will matter as much as the quarter itself.
Surface Technologies remains the soft spot. Revenue there fell 3% sequentially to $276 million, and management now expects the segment to finish near the low end of its range because of reduced Middle East activity tied to the ongoing conflict. Because it is a small piece of the total, further weakness is unlikely to derail results, but it bears watching for whether margin discipline keeps segment EBITDA steady.
Sentiment has warmed sharply from the near-neutral reading ahead of last quarter, even as the share price has gone the other way. The stock, at $68.93, sits just above its 200-day moving average and near the bottom of its post-earnings range of $67.00 to $80.70. That leaves room for a rebound if subsea margins and orders confirm the bullish narrative, but little technical cushion if they do not. Ultimately, the report hinges on one question: can TechnipFMC show that subsea profitability above 20% and a back-half acceleration in orders are real enough to support the raised full-year targets?
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 8 hours | |
| Oct-20 | |
| Oct-13 | |
| Oct-06 | |
| Sep-17 | |
| Sep-15 | |
| Sep-03 | |
| Aug-31 | |
| Aug-21 | |
| Aug-12 | |
| Aug-11 | |
| Jul-30 | |
| Jul-30 | |
| Jul-28 | |
| Jul-22 |
Oil Shocks Spur Energy Name To Highs; Stock Nears Pivot With Earnings Ahead
FTI
Investor's Business Daily
|
