TechnipFMC Beats And Raises, Issues First 2027 Subsea Outlook, But Order Book Shrinks For A Second Straight Quarter
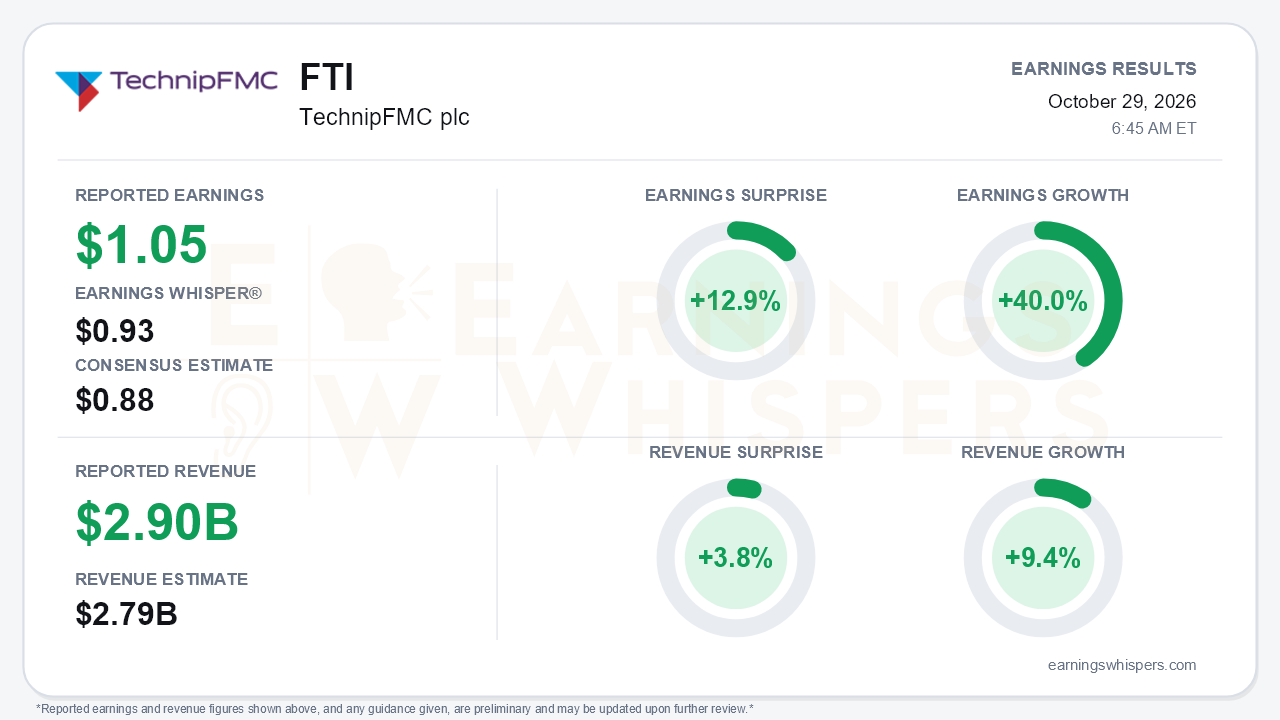
TechnipFMC delivered a clean beat-and-raise for the third quarter. Adjusted EPS of $1.05 topped the $0.88 consensus by 12.9% and cleared the $0.93 Earnings Whisper number. Revenue of $2.896 billion beat by 3.8%. Earnings grew 40.0% year over year on 9.4% revenue growth, and both figures improved sequentially: revenue rose from $2.76 billion in Q2 and roughly $2.5 billion in Q1. Management raised 2026 Subsea revenue and free cash flow guidance and issued preliminary 2027 Subsea targets. The central tension is what the income statement and the order book now say. Execution and margins are clearly improving, but inbound orders fell short again, and the company softened its 2026 orders target just as it extended its growth outlook.
The quality of the beat is high. Subsea drove it, with revenue of $2.6 billion, up 12.1% year over year. Subsea operating profit rose 30.2%, and its adjusted EBITDA margin reached 23.5%, extending a steady climb from 18.9% in Q4 2025 to 20% in Q1 and 23.2% in Q2. GAAP and adjusted EPS were identical at $1.05, so the beat did not depend on add-backs. Foreign exchange was a modest headwind of $8.6 million.
Two factors flattered per-share growth:
- Diluted share count fell about 4% year over year after $320 million of buybacks in the quarter. As a result, net income grew 35.1% while EPS grew 40%.
- The tax provision declined sequentially even though pretax income was higher.
Cash generation was strong. Free cash flow was $470 million for the quarter and $1.23 billion year to date, net cash rose to $645 million, and roughly 86% of nine-month free cash flow was returned to shareholders.
The weak spot is orders, and bears have legitimate ammunition here:
- Subsea inbound of $2.05 billion fell 18.2% sequentially and 13.9% year over year, for a book-to-bill of 0.8x.
- Year-to-date Subsea orders of $6.46 billion trail the $7.72 billion booked in the same period last year.
- Subsea backlog slipped to $15.5 billion, and that total includes a $202 million currency benefit.
- Surface Technologies backlog is down 25.4% year over year.
On the call, management moved its $10 billion 2026 Subsea inbound target from a firm commitment to "more likely than not," citing two or three large awards that could slip into 2027. Hitting the target would require roughly $3.5 billion of Q4 orders. Management replaced the single-year target with a five-quarter framing of at least $14.5 billion through 2027. That framing is a credible bridge, but it is also a convenient one.
The forward narrative strengthened in other respects:
- **Opportunities pipeline:** The Subsea opportunities list rose for a ninth straight quarter to $32 billion.
- **Customer agreements:** The PETRONAS strategic collaboration agreement names TechnipFMC as that company's deepwater development partner. A bp memorandum of understanding positions TechnipFMC as preferred supplier of 20K systems for the Paleogene program.
- **Order quality:** Three iEPCI awards in the quarter, including Limbayong, support management's claim that more Subsea 2.0, iEPCI and direct awards will lift the quality of future inbound.
- **Tone:** Management's language shifted from anticipating a 2027 step-up to declaring the step-up has arrived, framing the cycle as a wave extending beyond the decade.
The 2027 guide calls for Subsea revenue of $10.0-$10.4 billion and margins of 22.5%-24%. That implies better-than-10% Subsea EBITDA growth on only about 5% revenue growth, with upside from iEPCI 2.0 explicitly excluded. Near term, management guided to a seasonal Q4 Subsea decline: revenue down mid-to-high single digits and margin falling about 250 basis points to roughly 21%.
Investor sentiment improved meaningfully into the report, rising from near-neutral 0.04 to 0.32. That is a positive but not euphoric reading. Price action tells a more complicated story. Shares hit a 52-week high of $80.70 in early September, then slid to $63.95 on October 22, just a week before the report. They entered earnings at $71.40, essentially unchanged from the $71.50 open after the July report. The stock sits 3.5% above its 200-day moving average and near the midpoint of its inter-earnings range, 11.5% below the September peak. The market has already pulled back from peak enthusiasm, likely reflecting the order shortfall, so the report lands on a stock that is not stretched. The Earnings Whispers trend readings are mixed, with momentum positive and AVWAP still negative.
The bottom line is that TechnipFMC's earnings engine is performing better than ever. Margin expansion, cash conversion and buybacks are compounding, and the early 2027 guide extends that trajectory. The unresolved question is timing on orders. Two consecutive quarters of shrinking backlog and a hedged $10 billion target mean the thesis now leans on Q4 and 2027 awards materializing as promised. If the large awards land, the softened language will look like conservatism; if they slip again, the growth story will rest on margins alone.
Read our earnings preview for TechnipFMC plc: https://www.earningswhispers.com/article/FTI/21072
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 12 hours | |
| 17 hours | |
| Oct-27 | |
| Oct-21 | |
| Oct-20 | |
| Oct-13 | |
| Oct-06 | |
| Sep-17 | |
| Sep-15 | |
| Sep-03 | |
| Aug-31 | |
| Aug-21 | |
| Aug-12 | |
| Aug-11 | |
| Jul-30 |
