Phathom's Prescribing Friction Faces Its First Test After Guidance Cut Rattled Investors
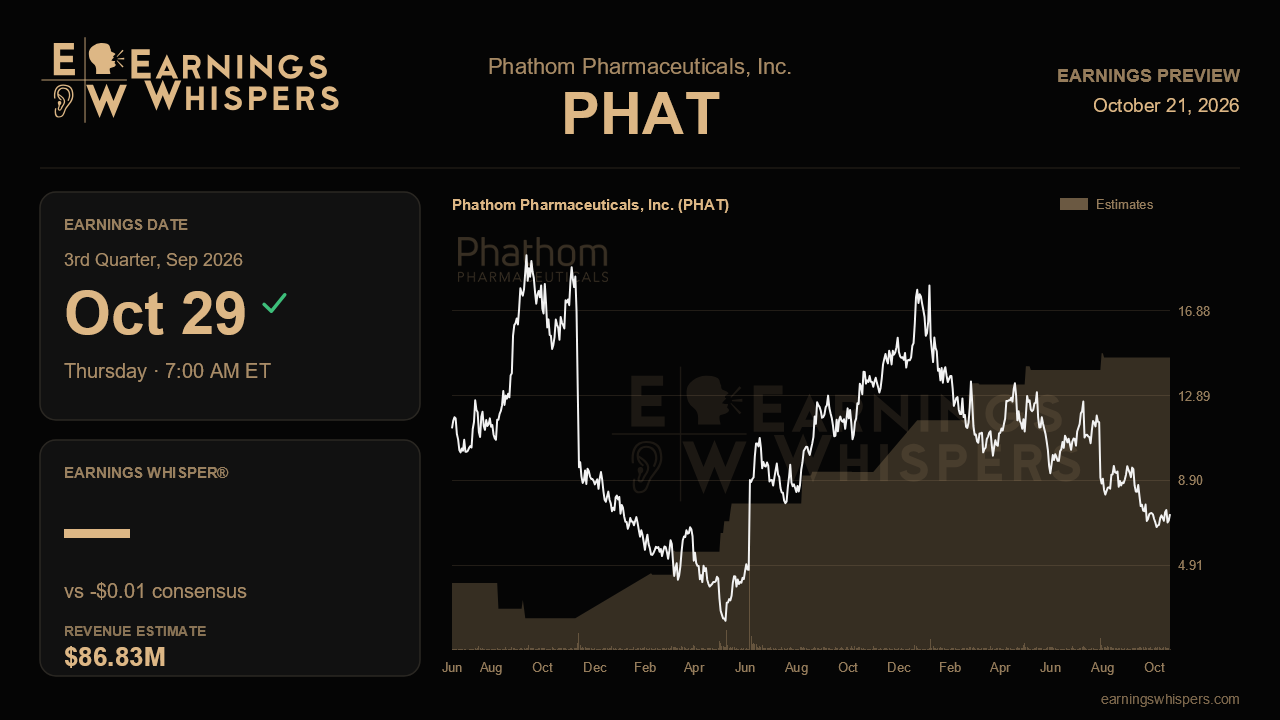
Last quarter Phathom Pharmaceuticals delivered the kind of financial milestone small-cap drugmakers dream about, reaching operating profitability excluding stock compensation and generating cash from operations a full quarter ahead of plan. Then it cut its full-year revenue outlook and introduced a new word to its vocabulary: friction. The market listened more closely to the second part. When the company reports third-quarter results before the open on October 29, the question is whether the slowdown in Voquesna's trajectory was a one-time reset or the start of a flatter curve.
Wall Street expects revenue of about $86.8 million, up roughly 75% from $49.5 million a year ago, with a loss of about a penny per share compared with a 28-cent loss in the year-ago quarter. That growth rate is still eye-catching, but the sequential math is more revealing. Hitting consensus means adding roughly $12.5 million over the second quarter's $74.3 million, a step down from the $16 million sequential gain management celebrated last time as its largest ever. In other words, the Street is already modeling some deceleration, which gives the company a reasonable bar to clear.
The full-year picture is where things get awkward. Management now guides to $310 million to $325 million in 2026 revenue, down from $320 million to $345 million, a range it had reiterated twice before trimming it. With about $132.6 million booked in the first half, the new range implies second-half sales of roughly $177 million to $192 million. Yet full-year consensus sits near $335 million, above the top of management's range, suggesting some estimates have not fully caught up with the cut. If the third quarter lands near $86.8 million, the fourth quarter would need somewhere around $91 million to $106 million to fit inside guidance. A third-quarter figure that keeps the high end in play would go a long way toward restoring credibility; one that points toward the low end could force another round of estimate cuts.
The operational details matter more than the headline number. Management blamed the guidance reduction on physicians balking at prior authorization and documentation hurdles for patients with milder GERD, a headwind absent from the uniformly upbeat commentary of earlier calls. Evidence that this is being solved would include continued growth in covered prescriptions, which rose 24% sequentially last quarter, along with early signs that the omnichannel marketing push slated for the second half is moving new prescriptions. Gross-to-net, which has held in a 55% to 59% band, and gross margin near 80% should stay steady; any slippage would suggest the company is buying volume with price. On costs, the tightened cash operating expense range of $235 million to $245 million and continued positive operating cash flow would confirm that the profitability story is durable rather than a one-quarter event. Updates on the eosinophilic esophagitis Phase II readout, now expected in the fourth quarter, and the planned Phase III non-erosive GERD as-needed trial will also help frame the longer-term opportunity, particularly with a second potassium-competitive acid blocker, tegoprazan, potentially arriving in 2027.
Investors have not been patient. The stock has fallen about 18% since the last report while the S&P 500 gained 4.5%, and at $7.31 it trades well below its 200-day moving average of $10.85 and closer to the bottom of its post-earnings range of $6.52 to $10.21. That entire range sits beneath the prior quarter's lows. Sentiment remains bearish, though slightly less so than heading into the last report, hinting that much of the disappointment may already be priced in.
The central issue is simple: Phathom has proven it can control costs, and now it must prove that prescribing friction is a manageable obstacle rather than a ceiling on demand. Sequential growth that keeps the upper half of guidance within reach would validate the profitable-growth narrative; another visible slowdown would confirm the market's skepticism.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-19 | |
| Oct-12 | |
| Oct-08 | |
| Sep-29 | |
| Sep-09 | |
| Sep-01 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-29 | |
| Jul-20 | |
| Jun-23 | |
| May-22 | |
| May-20 |
