Phathom Misses On A Decelerating Quarter As Cash-Flow Progress Collides With A New VOQUEZNA Exclusivity Overhang
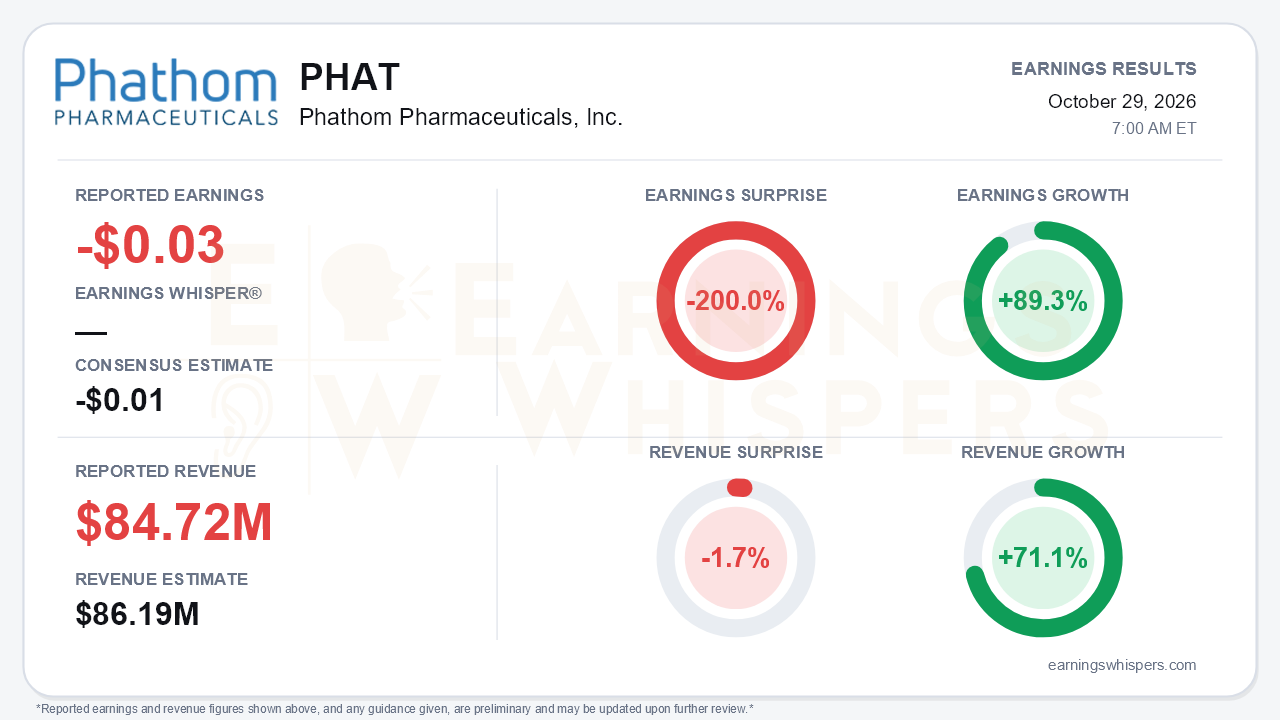
Phathom Pharmaceuticals (NASDAQ: PHAT) missed on both lines in the third quarter. The company reported a loss of $0.03 per share on the Earnings Whispers normalized basis, against a consensus estimate for a $0.01 loss. That is a 200.0% negative surprise, although earnings still improved 89.3% from a year ago. Revenue of $84.72 million rose 71.1% year over year but fell 1.7% short of the $86.19 million consensus. The central tension is that Phathom's financial transformation is real, while its growth rate is cooling just as the durability of VOQUEZNA's exclusivity has come under legal attack. Management reaffirmed full-year guidance, but that guidance had already been cut last quarter. Reaffirming a lowered bar is not the same as regaining momentum.
The quality of the quarter depends on which earnings lens you use, and the bases differ materially. The company's GAAP net loss narrowed to $13.9 million, or $0.16 per share, from $30.0 million, or $0.41, a year ago. On the company's own non-GAAP measure, which excludes stock-based compensation and non-cash financing interest, Phathom earned $3.0 million, or $0.04 per share. The operating line is the more telling improvement. The GAAP operating loss shrank to just $85,000 from $15.3 million, and operating profit excluding stock compensation was $5.8 million, the second straight positive quarter. Operating cash flow was positive again at about $2.1 million, which contrasts with management's Q2 expectation of cash use for the rest of the year. Cash rose to $184.6 million.
The blemishes sit in gross margin and growth.
- **Gross margin:** About 78%, below the roughly 80% guide, which management attributed to one-time manufacturing charges.
- **Revenue:** Sequential growth slowed to 14% from 27% in Q2.
- **Covered prescriptions:** Sequential growth eased to 19% from 24%.
- **Cash-pay prescriptions:** Growth dropped to 6% from 16%, partly clouded by an IQVIA methodology change.
Covered scripts now represent about 65% of the roughly 380,000 prescriptions filled. That mix shift supports pricing quality but limits volume upside from the cash channel.
Management's forward commentary preserved a credible, if slower, growth story. The Access First initiative and a $0 copay offering through BlinkRx for eligible commercially insured patients are designed to remove prescribing friction, and management called the gross-to-net impact insignificant. Executives framed the access benefits as gradual and weighted toward 2027. Expense discipline is a genuine positive. Cash operating expenses are tracking toward the low end of the $235-$245 million range, and management said 2027 revenue growth will outpace operating expenses, with business development capacity beginning that year. Full-year gross-to-net is now expected near the low end of 55-59%, partly helped by lower wholesale inventory. Q4 gross-to-net, however, rises seasonally with Medicare Part D catastrophic coverage. Reaching the $310-$325 million revenue range implies Q4 revenue of roughly $93 million to $108 million, a step-up that leaves little room for further deceleration.
Bears have legitimate ammunition beyond the growth slowdown. On October 21, BDR Pharmaceuticals sued the FDA, challenging the GAIN Act extension that gives VOQUEZNA NCE exclusivity through May 2032. A second ANDA filer is seeking to join, and the FDA opened a public comment docket with comments due November 23. Phathom has won the right to intervene and says it will vigorously defend its exclusivity, but any reversal would open the door to earlier generic filings. Separately, a competing PCAB, tegoprazan, could be approved as early as January 2027, and management declined to forecast the pricing impact. Near-term catalysts include:
- Phase 2 EoE topline data due in Q4 2026, which could support a written request for pediatric exclusivity.
- The enrolling Phase 3 as-needed NERD trial, with data guided to Q1 2028.
The market has been pricing these risks aggressively. Shares stood at $6.28 heading into the report, down 29.4% since the open after the July report. That leaves the stock about 40.5% below its 200-day moving average of $10.56. The stock set a 52-week low of $5.02 on October 23, two days after the BDR lawsuit, and has since rebounded about 25% off that low while remaining 38.5% below its inter-earnings high. Investor sentiment was negative and became slightly more negative, slipping from -0.22 to -0.25, a modest shift rather than a capitulation. The trend readings are mixed: sequential growth is positive, momentum is neutral, and price and AVWAP trends remain negative.
The bottom line is that Phathom delivered a self-funding quarter that turnaround skeptics would have doubted a year ago, but it did so with slowing script growth, a modest revenue miss, and a margin hiccup. The fundamental question has shifted from whether VOQUEZNA can reach profitability to whether its growth and exclusivity runway are durable enough to justify the investment. Until the exclusivity dispute and the tegoprazan timeline come into clearer focus, cash-flow progress alone is unlikely to fully reset the investment setup.
Read our earnings preview for Phathom Pharmaceuticals, Inc.: https://www.earningswhispers.com/article/PHAT/21118
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| 13 hours | |
| Oct-26 | |
| Oct-23 | |
| Oct-23 | |
| Oct-21 | |
| Oct-19 | |
| Oct-12 | |
| Oct-08 | |
| Sep-29 | |
| Sep-09 | |
| Sep-01 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 |
