PBF Energy Must Prove Its Martinez-Fueled Profit Surge Can Nearly Double Again
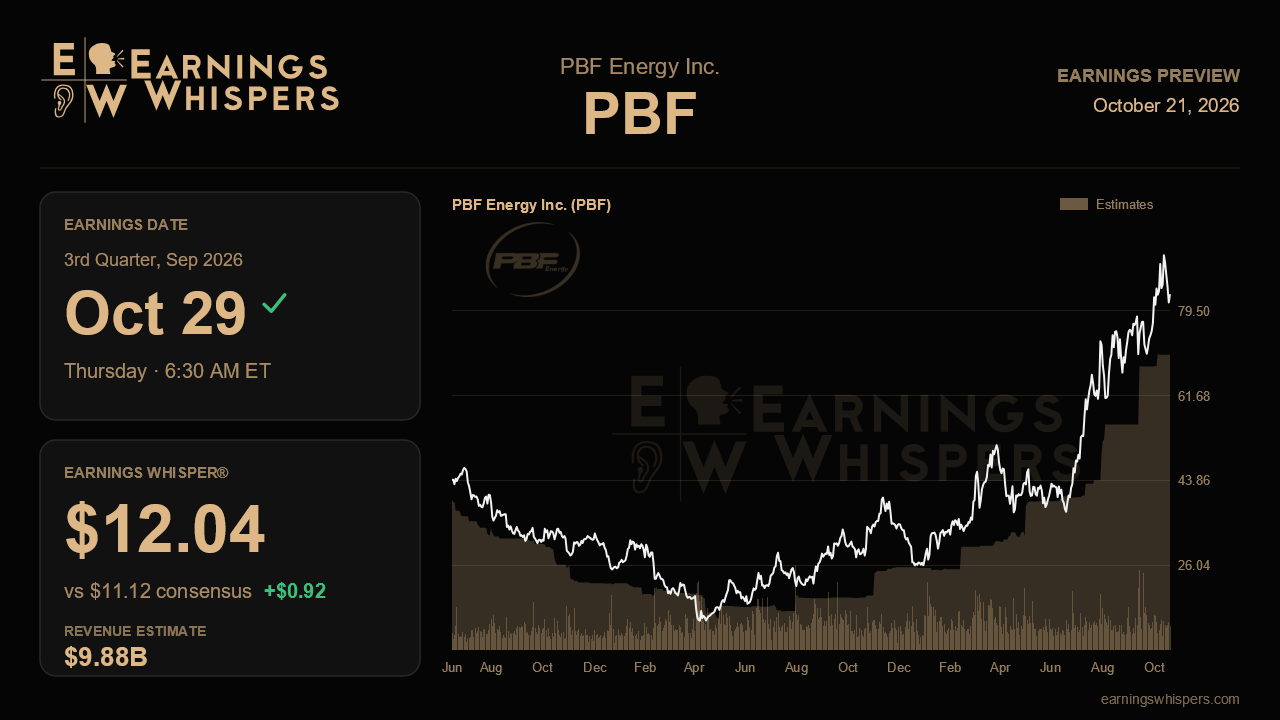
Last quarter PBF Energy finally delivered the clean quarter shareholders had waited for, with Martinez back online just as global refining margins exploded. The upcoming report asks a harder question. Can a company that just posted $6.22 in adjusted earnings per share nearly double that figure in a single quarter, with two of its refineries still nursing operational problems?
Wall Street thinks so. Consensus calls for $11.12 a share on revenue of $9.88 billion, against a loss of $0.52 a share and $7.65 billion in revenue a year ago. That is a 29% revenue gain and a swing in earnings so large that the percentage growth figure is mostly arithmetic. The more telling detail is the sequential picture: analysts expect revenue to fall from last quarter's $11.68 billion while profit climbs sharply. The Street is effectively betting on wider margin capture per barrel rather than more volume or higher selling prices. The Earnings Whisper of $12.04 sits about 8% above consensus, a meaningful gap that suggests the informal bar is higher still. Management did not issue formal earnings guidance, so the forecast rests on the margin backdrop management described rather than a company target.
That backdrop is the core of the bull case. Management argued that roughly 5 million barrels a day of global refining capacity is offline because of conflicts in the Middle East and Eastern Europe, some of it physically damaged and needing years to repair, and that elevated margins should persist into 2027. The company also pushed fourth-quarter turnarounds at Toledo and Chalmette into 2027, trimming capex guidance to about $850 million so it could run hard through peak conditions. This report is the first full test of that decision. Strong throughput and high capture rates would validate it. Lower volumes would raise questions, because Chalmette's pre-treater and reformer were expected to stay offline into the third quarter, cutting gasoline yield, and Toledo's unplanned FCC work dented throughput in the second quarter. If either issue lingered longer than expected, that is the most obvious way PBF could fall short of a number that assumes nearly everything runs well.
Beyond margins, several threads from the last call deserve follow-up. Management expected cash to reach roughly $1.5 billion by the end of July after cutting net debt by more than 62%, and confirmation of that trajectory would show the windfall is reinforcing the balance sheet rather than simply flattering the income statement. The cost program also matters: the RBI savings target was raised to $350 million by year-end, with a new $60 million a year of procurement savings layered on top. Progress there would help support earnings once margins normalize, which management openly acknowledged will happen eventually. One more sizable insurance payment related to Martinez is still pending, and any update on the Torrance hydrogen plant repurchase will show whether reliability investments are on track. On the risk side, renewable fuel compliance costs of around $14 a barrel and crude sourcing in disrupted markets remain swing factors.
The market has already priced in plenty of optimism. Shares have gained nearly 28% since the last report, outpacing the S&P 500 by more than 23 percentage points, and at $83 the stock sits far above its 200-day moving average of $51.67. It has, however, pulled back roughly 10% from its post-earnings high of $92.46, hinting that some investors are already weighing how long the margin spike lasts. Sentiment has moved from mildly bearish to mildly bullish, a modest shift rather than a rush of enthusiasm.
The central issue is whether PBF converted an extraordinary margin environment into extraordinary earnings without operational leakage. If Chalmette and Toledo ran cleanly and Martinez delivered a full quarter at scale, the transformative-moment narrative stays intact. If outages ate into capture, a beat on paper may still feel like a miss against the whisper.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 7 hours | |
| Oct-14 | |
| Oct-07 | |
| Oct-02 | |
| Sep-28 | |
| Sep-28 | |
| Sep-24 | |
| Sep-23 | |
| Sep-14 | |
| Sep-14 | |
| Sep-11 | |
| Sep-03 | |
| Aug-28 | |
| Aug-28 | |
| Aug-17 |
